Getting car insurance quotes in Olympia doesn’t have to be complicated. We at Cross Insurance Agency help drivers compare rates from multiple carriers and find coverage that fits their budget and needs.

Shopping around for quotes takes time, but it pays off. Most Olympia drivers who compare rates end up saving hundreds of dollars per year on their premiums.

How Car Insurance Quotes Work in Olympia

What Information Insurers Need From You

Insurers ask for accurate details about your driving history, vehicle, and coverage needs to generate a quote. You’ll provide your driver’s license number, vehicle identification number (VIN), current coverage limits if you have existing insurance, and your driving record from the past three to five years. Insurers also request your annual mileage, how you use your vehicle, and any accidents or violations on file.

Precision matters here. Vague or incomplete answers force insurers to make assumptions, which often results in inflated estimates that don’t reflect your actual risk profile. Washington State Department of Insurance requires minimum liability coverage of $25,000 per person, $50,000 per accident, and $10,000 in property damage, but insurers will ask whether you want to exceed these minimums-most financial advisors recommend 100/300/100 if you have assets worth protecting.

You’ll also need to decide on optional coverages like collision, comprehensive, uninsured motorist protection, and rental reimbursement. Local Olympia agents understand how ZIP code, local traffic patterns, and commuting distance affect your quote, so share specific details about where you drive and park your vehicle.

How Local Agents Pull Multiple Quotes

Independent agents in Olympia access multiple carrier systems simultaneously, which means they can generate three to five competing quotes without you having to contact each insurer separately. Agents enter your information once into their system and retrieve quotes from carriers like State Farm, Geico, Progressive, and regional providers within minutes.

The process typically takes one to two business days because agents verify your information and cross-check coverage options before presenting results. You’ll receive side-by-side comparisons showing premiums, deductibles, limits, and available discounts for each carrier. Rate differences between carriers for identical coverage can exceed 40 percent annually, according to typical market variations in Washington.

Agents also flag which carriers offer usage-based discounts through telematics programs, where safe driving habits lower your premium. They identify multi-policy bundling opportunities, student discounts, and anti-theft device incentives specific to your situation. Local agents have relationships with underwriters and know which carriers are most competitive in the Olympia market right now, rather than relying on generic online comparison tools that may be outdated or incomplete.
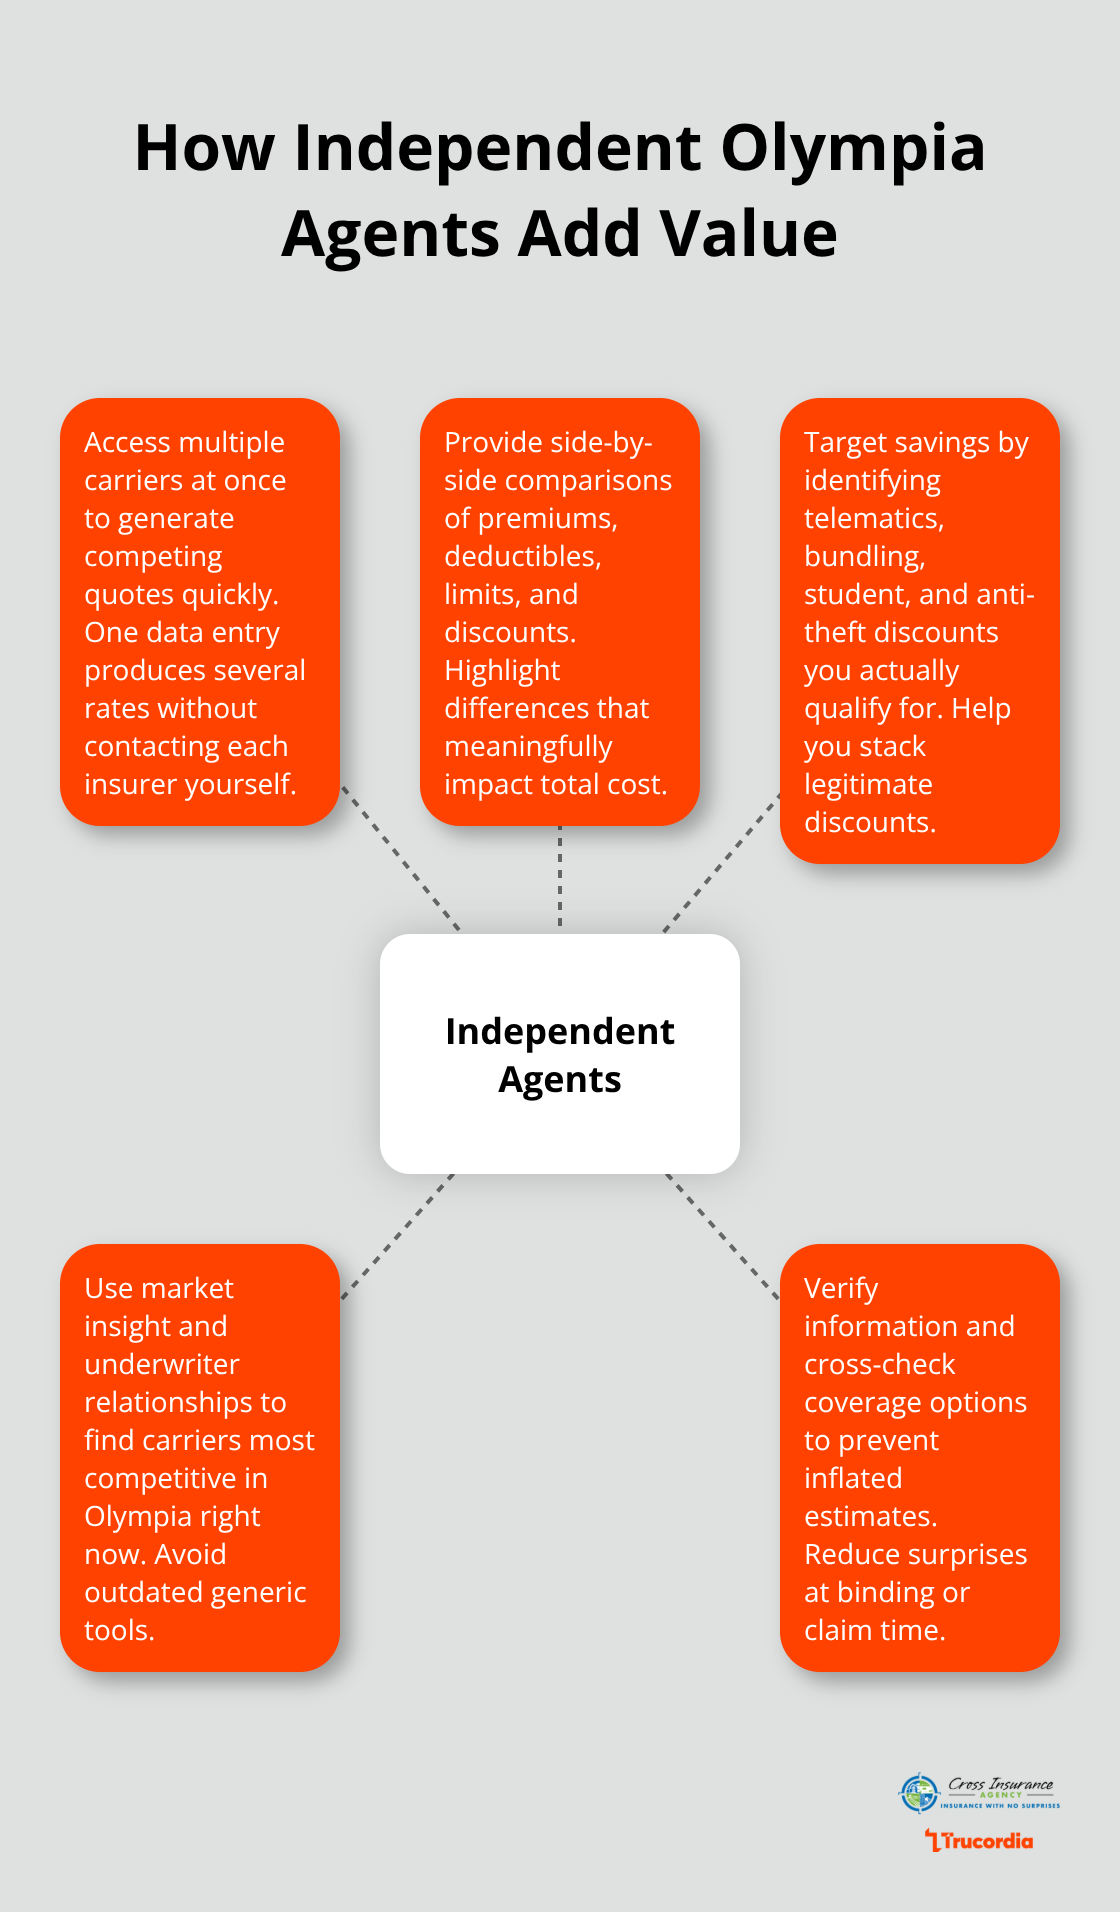
Visual showing how independent Olympia insurance agents add value when pulling multiple quotes. - car insurance quotes Olympia

What Happens Next With Your Quotes

Once agents present your quotes, you’ll evaluate coverage options and ask clarifying questions about deductibles, limits, and exclusions. This is when you compare not just price, but also claims service quality and financial strength of each carrier.

Why Comparing Car Insurance Rates Saves Money

Understanding Price Variations Between Carriers

Rate differences between insurers for identical coverage in Washington are substantial. Two drivers with the same vehicle, driving record, and coverage limits can pay premiums that differ by 40 percent or more annually, depending on which carrier quotes them. Insurers use different risk models, claim experience in specific regions, and pricing algorithms to calculate premiums.
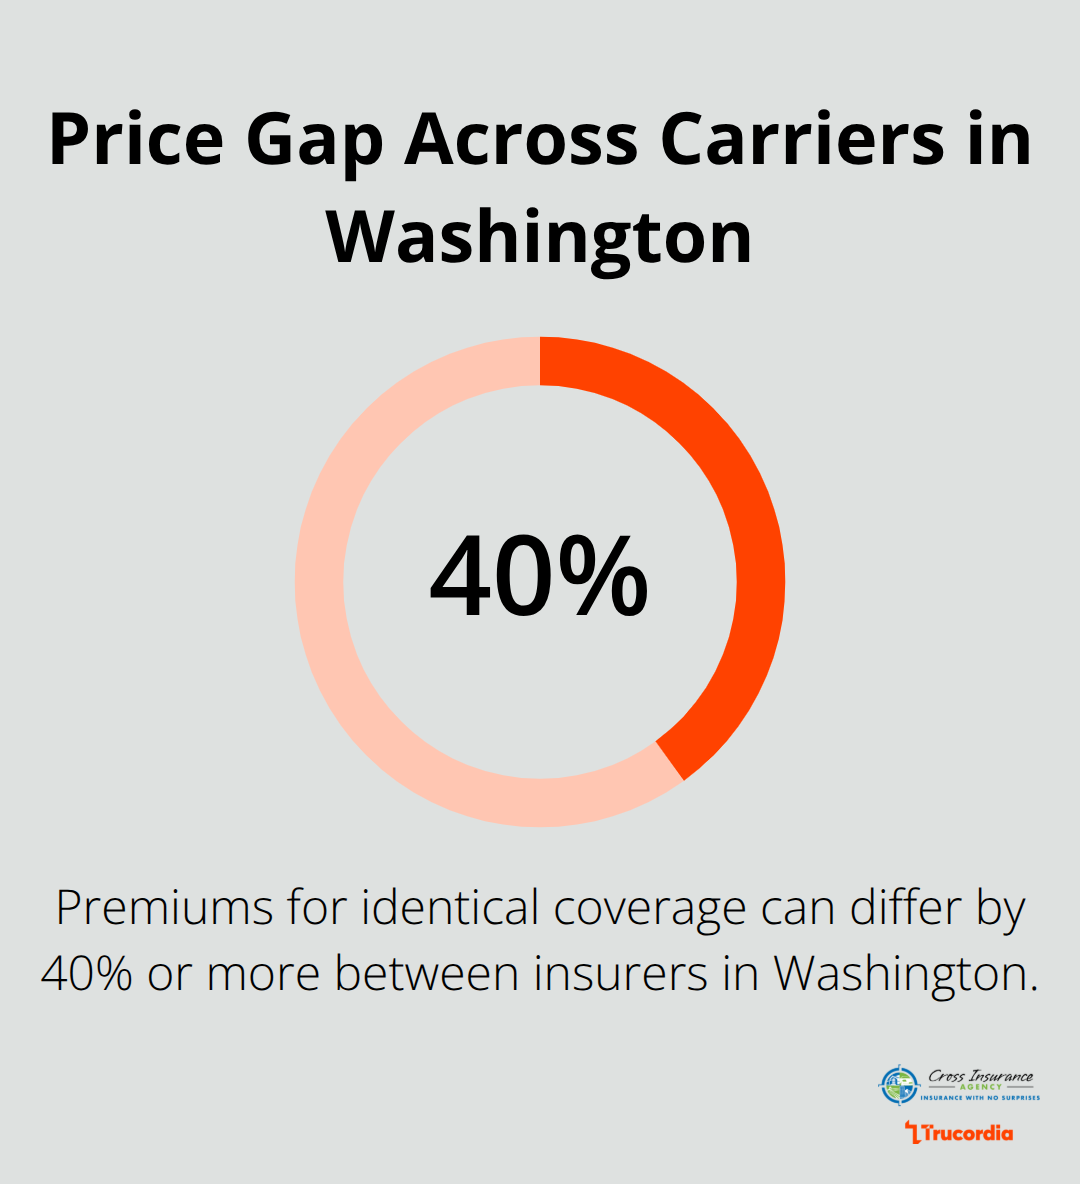
Chart highlighting that identical coverage can vary by 40% or more between insurers in Washington. - car insurance quotes Olympia

Some carriers weight traffic violations more heavily; others prioritize accident history. A few focus aggressively on Olympia and the surrounding areas, while national companies apply broader state-level pricing that doesn’t account for local conditions.

One Olympia driver discovered a $600 annual difference between the lowest and highest quote for the exact same 100/300/100 liability coverage with $500 collision deductible. That gap represents money you leave on the table if you accept the first quote without shopping around.

Discount Opportunities Available to Olympia Drivers

Discounts stack quickly when you know where to look. Bundling your auto policy with homeowners or renters insurance can save money on your auto premium, according to standard multi-policy discount structures across major carriers. Safe driver discounts reward three to five years without violations or accidents. Student away at school discounts apply if you have a child in college who doesn’t drive your vehicle year-round.

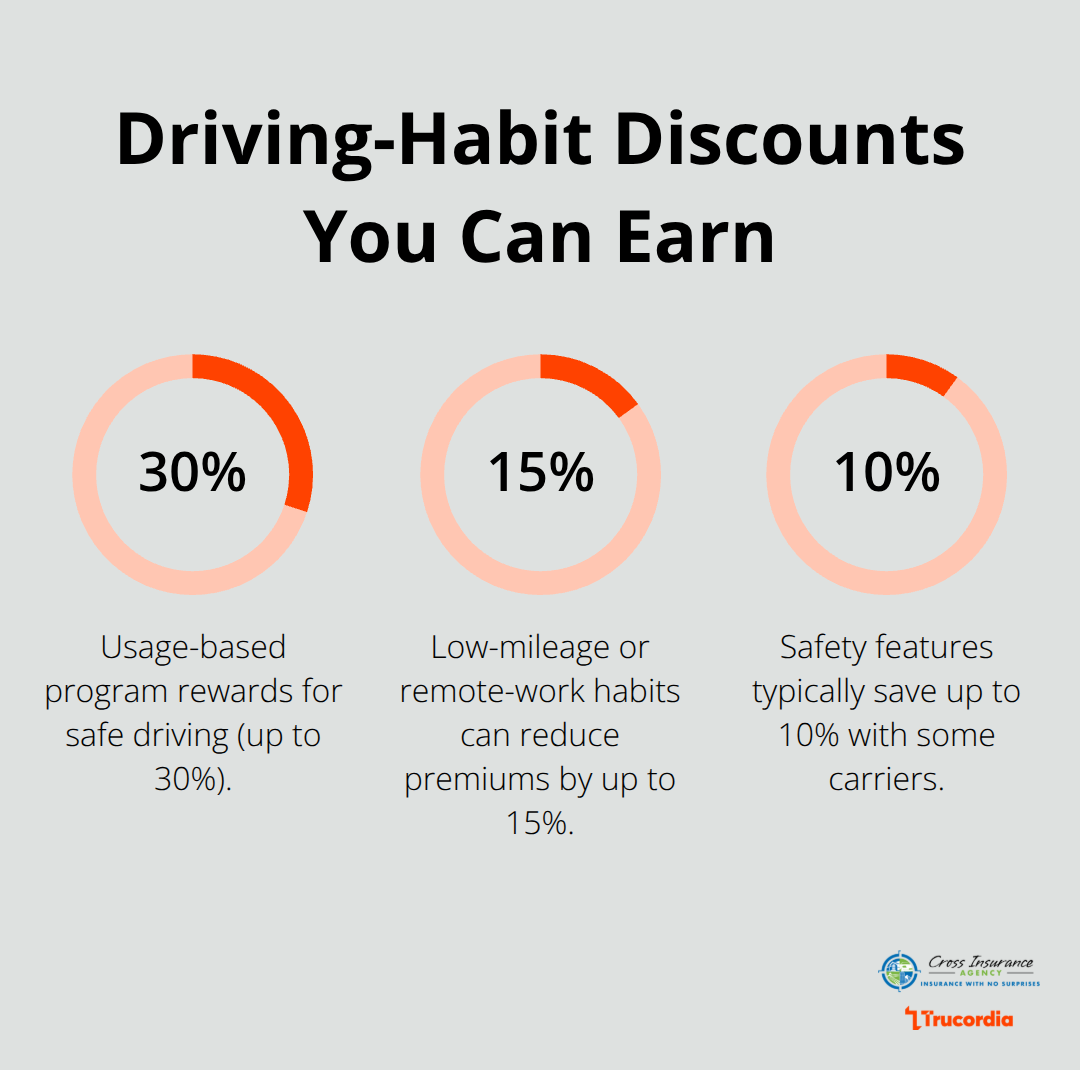
Anti-theft device discounts range from 5 to 15 percent depending on the device type and carrier. Telematics programs, where you opt into usage-based monitoring through a mobile app or vehicle plug-in device, can reduce premiums by 10 to 30 percent for safe drivers who maintain low annual mileage. Low-mileage discounts specifically benefit Olympia residents who work from home or use public transit for commuting.

How Bundling Policies Reduces Your Premium

Not all carriers offer all discounts, and not all agents inform you which discounts apply to your specific situation. Local agents in Olympia know which carriers are most generous with each discount type right now, whereas online quote tools often hide discount eligibility until after you’ve committed to a quote. When you bundle multiple policies with one carrier, you unlock savings that compound across your entire insurance portfolio.

The real advantage comes from working with someone who understands your local market and can match you with carriers that reward your specific situation-whether that’s your driving habits, vehicle type, or household composition.

Getting Car Insurance Quotes From Local Olympia Agents

Benefits of Working With Independent Agents

Independent agents in Olympia access multiple carrier systems simultaneously, which means you obtain competing quotes without contacting five different insurance companies yourself. One conversation with a local agent produces three to five quotes within one to two business days. Online shopping requires you to enter your information repeatedly across different websites, receive generic results, and miss carrier-specific discounts that only agents know about.

Agents catch coverage gaps you might overlook. If you finance or lease your vehicle, an agent flags that your lender requires comprehensive and collision coverage with specific limits, then shows you which carriers offer the lowest premiums for those exact requirements. Local agents understand Olympia’s traffic patterns, weather risks, and claim frequency in your specific ZIP code, so they recommend coverage levels that make sense for how you actually drive, not just what meets Washington’s minimum 25/50/10 liability requirement.

Questions to Ask When Requesting Quotes

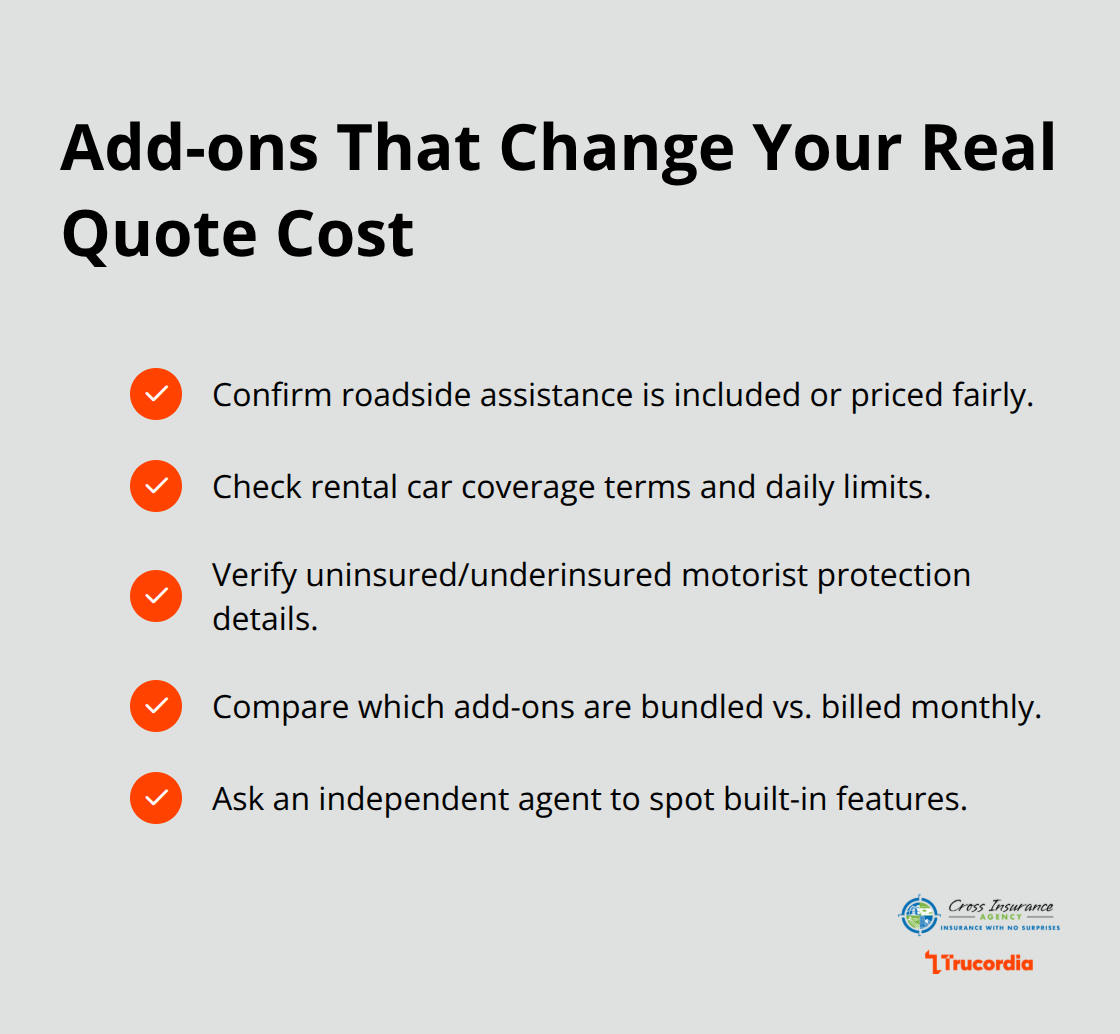
When you receive quotes, ask each agent about telematics programs that reward safe driving with 10 to 30 percent premium reductions. Inquire about low-mileage discounts if you work from home, and bundling savings if you add renters or homeowners insurance. Verify that every quote includes your chosen deductible amounts and liability limits so you compare identical coverage across carriers.
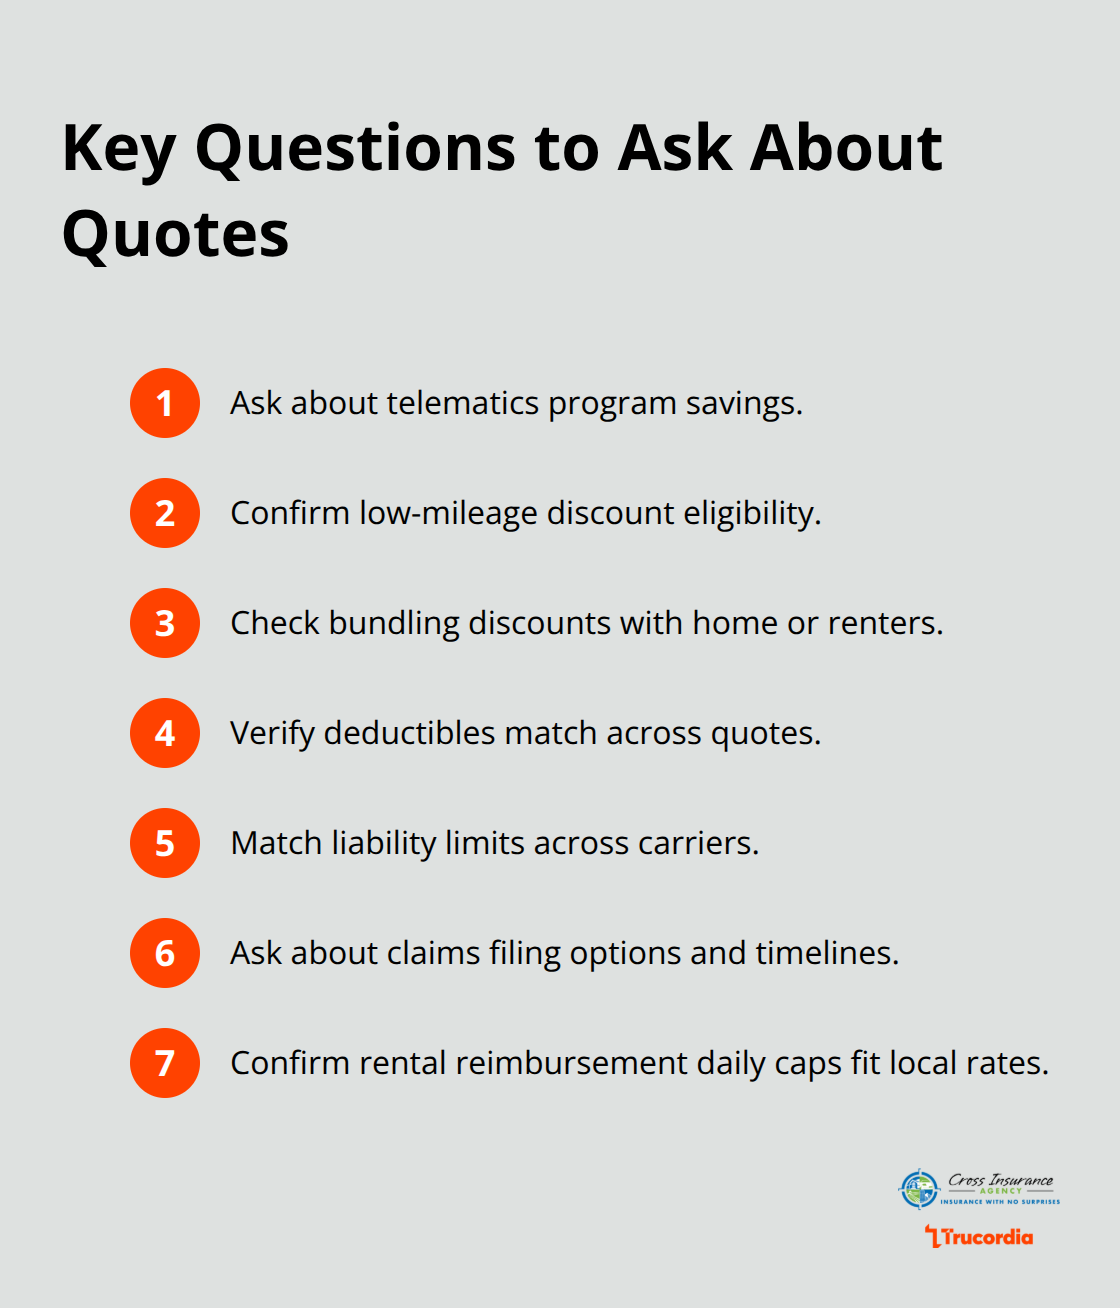
Compact checklist of essential questions to ask when reviewing car insurance quotes.

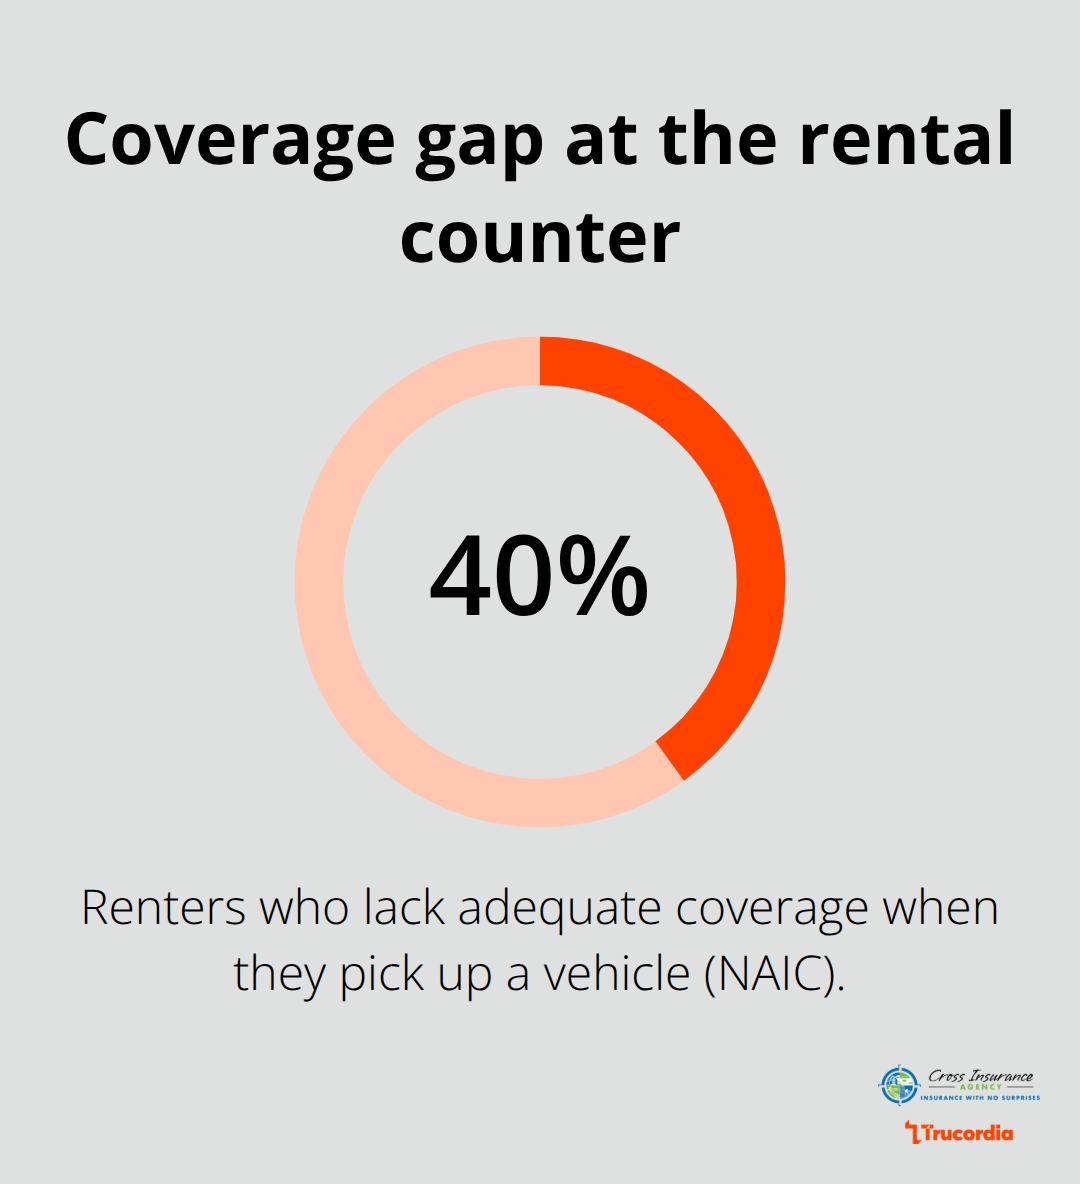
Request the agent’s claims process timeline too, since settling claims faster matters more than saving fifty dollars annually if you wait weeks for reimbursement after an accident. Ask whether the carrier offers rental reimbursement at rates that cover actual daily rental costs in your area, since some policies cap reimbursement at thirty dollars per day while local rental agencies charge forty-five to sixty dollars.

How to Evaluate Quotes and Coverage Options

Evaluating quotes means looking beyond price alone. Check the financial strength ratings of each carrier through A.M. Best, which grades insurers on their ability to pay claims during economic stress or natural disasters. Read the policy exclusions carefully because some carriers limit coverage in specific scenarios common to Olympia commuters (like coverage gaps if you drive for rideshare services occasionally or transport passengers for compensation).

Compare cancellation terms too, because some carriers charge fees if you leave within six months, while others allow penalty-free cancellation. Once you narrow your options to two or three carriers, contact each one directly with questions about their customer service availability, whether they offer online claims filing, and what their average claims settlement time is according to J.D. Power ratings. The cheapest quote means nothing if the carrier denies your claim or takes ninety days to process payment.

Final Thoughts

Comparing car insurance quotes in Olympia pays off financially and protects you from coverage gaps that cost far more than premium savings. Rate differences between carriers for identical coverage exceed 40 percent in Washington, which means shopping around consistently saves hundreds annually. Those who accept the first quote leave money on the table, while drivers who evaluate multiple options make informed decisions about their protection.

Local agents access multiple carrier systems at once, so you provide your information one time and receive three to five competing quotes within one to two business days. Ask about telematics programs, bundling savings, and low-mileage discounts specific to your situation, then verify that every quote includes your chosen deductible amounts and liability limits. Check financial strength ratings and read policy exclusions carefully to avoid surprises when you file a claim.

Local agent support matters most after you purchase a policy, since accidents and claims require someone in your community who advocates on your behalf. Contact an independent agent in Olympia to request car insurance quotes from carriers competitive in your area, and let them handle the comparison work while you focus on finding the right coverage for your needs.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
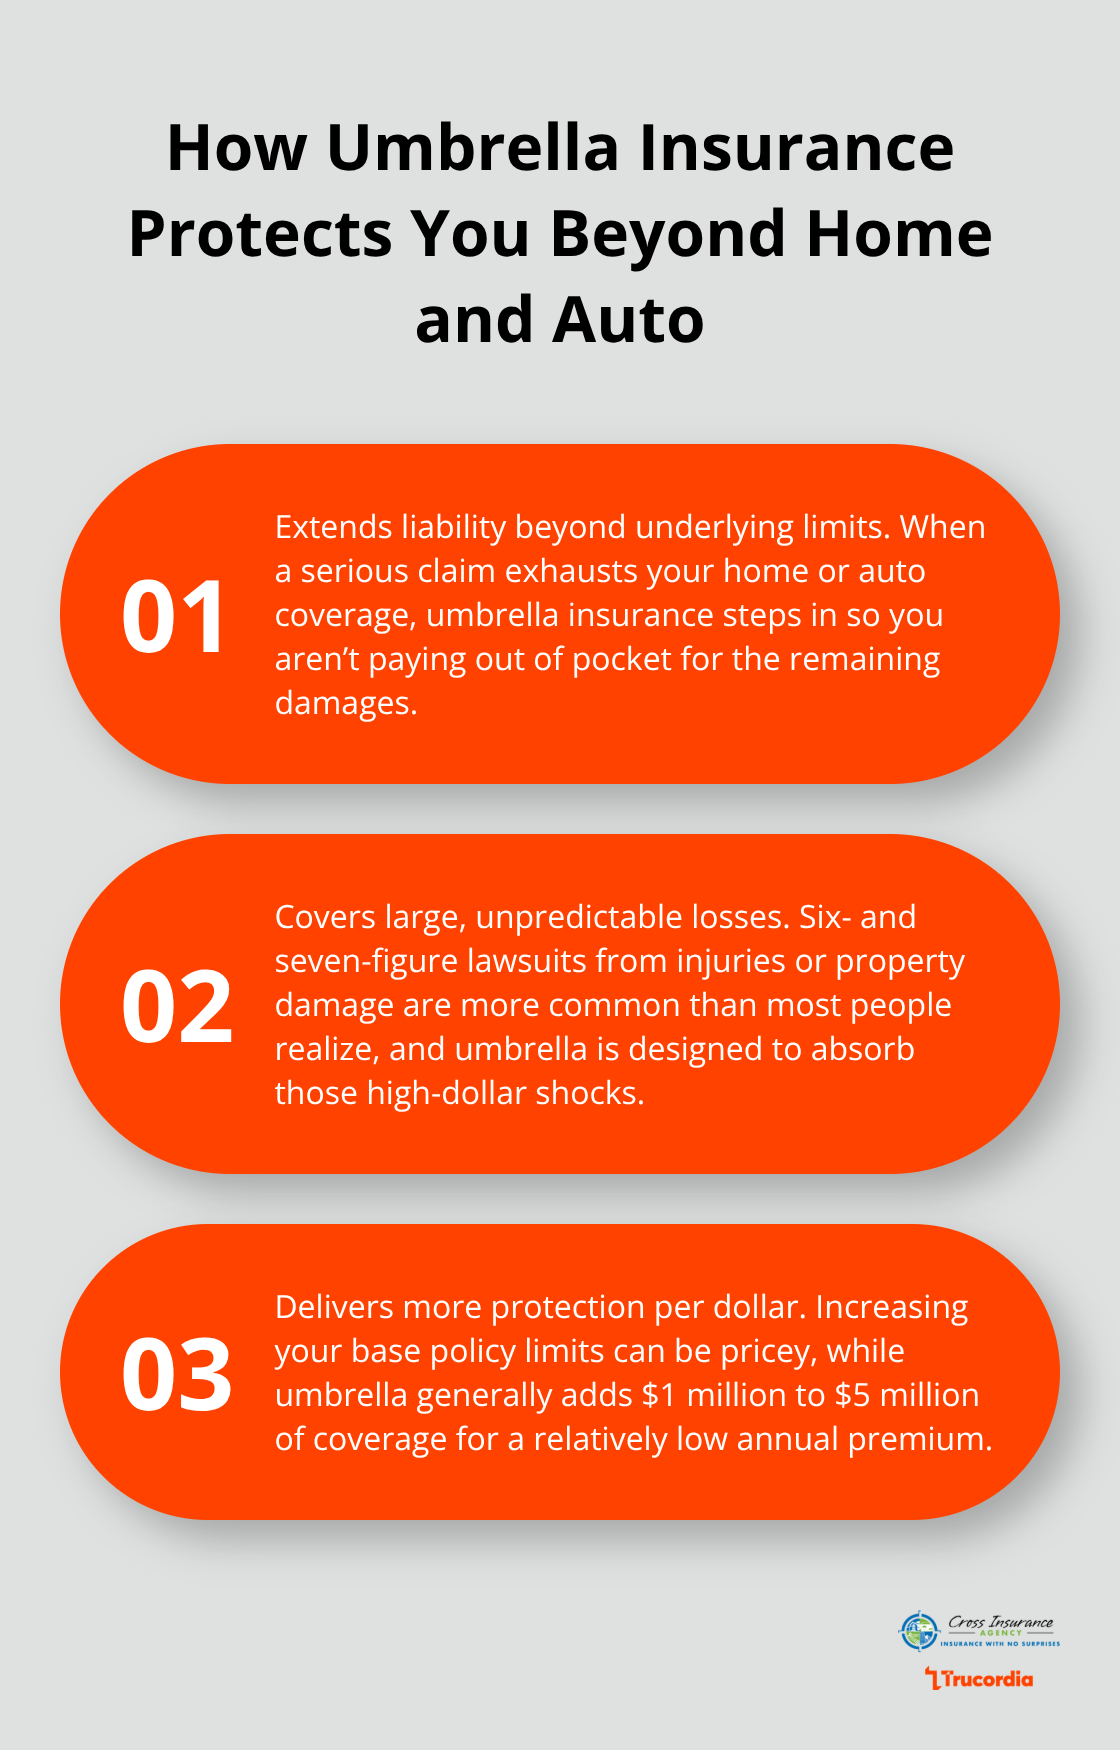
One lawsuit or accident could wipe out years of savings. Standard homeowners and auto insurance policies cap coverage at $300,000 to $500,000-far below what you might owe if someone is seriously injured on your property or in a car accident you cause.

Affordable umbrella insurance in WA fills that gap. At Cross Insurance Agency, we help Washington residents add $1 million to $5 million in liability protection for just $150 to $300 per year. It’s the simplest way to guard your assets and future income without spending a fortune.

What Umbrella Insurance Actually Covers

How Umbrella Insurance Fills the Gap

Your homeowners policy includes at least $1,000 of coverage, though you can get higher limits. Your auto policy typically maxes out at $250,000 to $500,000. These limits sound reasonable until someone files a lawsuit against you. A serious injury at your home, a car accident where you’re at fault, or damage you cause to someone else’s property can easily result in claims exceeding $1 million. Umbrella insurance sits on top of your existing policies and activates when those limits are exhausted. It provides an additional layer of protection-typically $1 million to $5 million-without requiring you to increase your underlying policy limits. This matters because raising homeowners or auto coverage limits often costs significantly more than adding umbrella protection.

Three key ways umbrella insurance adds affordable protection above home and auto policies

Why Washington Residents Face Higher Exposure

Washington residents face particular exposure because of our state’s legal environment and property values. A 2023 analysis by the Insurance Information Institute found that the average jury verdict in personal injury cases exceeded $1.2 million nationally, with some claims reaching $5 million or higher. Our state’s courts have awarded substantial settlements in cases involving serious injuries and property damage. These verdicts reflect the real financial stakes you face as a property owner or driver in Washington.

Real Claims That Exceeded Standard Coverage

One Washington homeowner learned this lesson when a guest fell on an icy walkway and suffered permanent injuries. The homeowner’s homeowners liability limit covered only a fraction of the $2.1 million settlement. Had umbrella insurance been in place, that additional million-dollar gap would have been protected. Another example: a driver caused a multi-car accident on I-405 near Seattle, injuring four people. Medical bills, lost wages, and pain-and-suffering claims totaled $1.8 million. The driver’s auto policy paid $500,000; umbrella insurance covered the remaining $1.3 million. Without it, the driver faced wage garnishment and asset seizure for years.

The Affordability Factor

These scenarios happen regularly in Washington, yet many residents hesitate to add protection because they assume it costs too much. The cost to add $1 million in umbrella coverage typically runs $150 to $300 annually, making it one of the most cost-effective protections available. This price point means you can protect yourself against catastrophic liability claims without straining your budget. When you compare that annual cost to the potential financial devastation of an uninsured claim, the value becomes clear. Understanding what umbrella insurance covers is only half the equation-the next step involves calculating how much coverage actually makes sense for your specific situation.

How Much Umbrella Coverage Makes Sense for You

Calculate Your Total Exposure

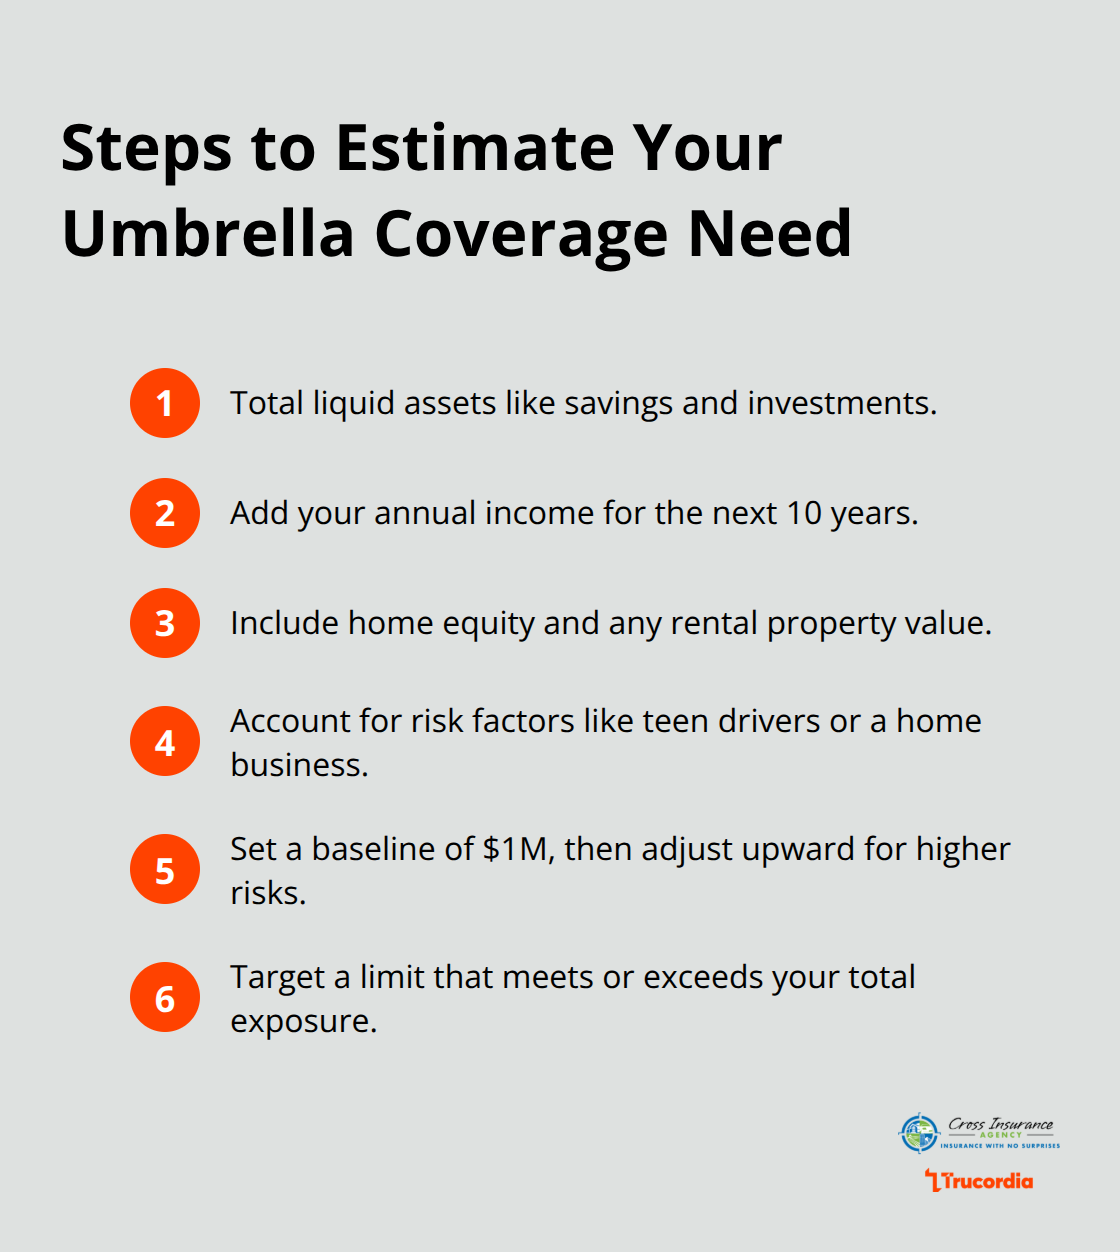
The answer depends on what you own and what you could lose in a lawsuit. Start by adding up your liquid assets-savings accounts, investment portfolios, rental income-plus your annual income for the next 10 years. If you own a home worth $600,000, have $200,000 in investments, and earn $80,000 annually, your total exposure exceeds $1.4 million. That figure should guide your umbrella limit. Washington homeowners with significant assets typically need $1 million to $2 million in umbrella coverage, while those with investment property or rental income often benefit from $3 million to $5 million limits.

Quick steps to total your exposure and pick an umbrella limit - affordable umbrella insurance WA

The National Association of Insurance Commissioners reports that median umbrella policies in the Pacific Northwest range from $1 million to $3 million, reflecting the region’s property values and litigation patterns. Your specific number depends on whether you have rental properties, host frequent gatherings, operate a home-based business, or drive regularly-each activity increases your liability risk and justifies higher limits.

Rental Properties and Multiple Income Streams

If you own a rental property, your liability exposure doubles because tenants and their guests can sue you, and your homeowners policy typically excludes rental activities. Drivers with multiple vehicles or teenage drivers face higher auto-related claims risk; teen drivers experience higher crash risk than experienced adult counterparts. Professional licenses matter too-if you’re a contractor, consultant, or operate any business from home, standard homeowners coverage excludes business activities, making umbrella protection essential.

High-Risk Features and Lifestyle Factors

If you have a swimming pool, trampoline, or frequently entertain guests, umbrella coverage becomes more valuable because premises liability claims spike around these features. The age of your assets also factors in; newer homes and vehicles in high-value neighborhoods attract larger claims. These variables compound your exposure and push your coverage needs upward.

Determining Your Ideal Coverage Limit

Try $1 million as your baseline, then increase to $2 million if you own rental property, operate a home business, or live in a neighborhood where home values exceed $750,000. Jump to $3 million or higher if you have multiple income sources, significant investment accounts, or frequently host events. Once you’ve identified your coverage target, the next challenge becomes finding that protection at a price that fits your budget-which is where shopping strategy makes all the difference.

How to Find Affordable Umbrella Insurance in Washington

Shop Multiple Carriers for the Best Rates

Once you know how much coverage you need, the real work starts: finding that protection without overpaying. Most Washington residents make the mistake of calling one or two insurers and accepting the first quote they receive. This approach leaves hundreds of dollars on the table annually. Umbrella insurance rates vary dramatically between carriers because each company prices risk differently. A policy that costs $250 with one insurer might cost $400 with another, even though the coverage is identical. Rate differences are consistently shocking when you compare options side by side. One Seattle homeowner received quotes ranging from $180 to $520 per year for $1 million in coverage from six different insurers. That $340 annual difference compounds to $3,400 over a decade.

The carrier you choose matters far less than the strategy you use to find it. Most people assume umbrella insurance costs the same everywhere, but pricing depends on how each company evaluates your home value, claims history, credit score, and the underlying limits on your existing policies. Some carriers specialize in high-net-worth clients and offer better rates for homes over $800,000, while others focus on standard homeowners and provide the cheapest coverage for typical Washington properties. Your specific situation determines which carrier offers the best rate, which is why generic online quotes rarely match what a broker can find.

Bundle Your Policies for Maximum Savings

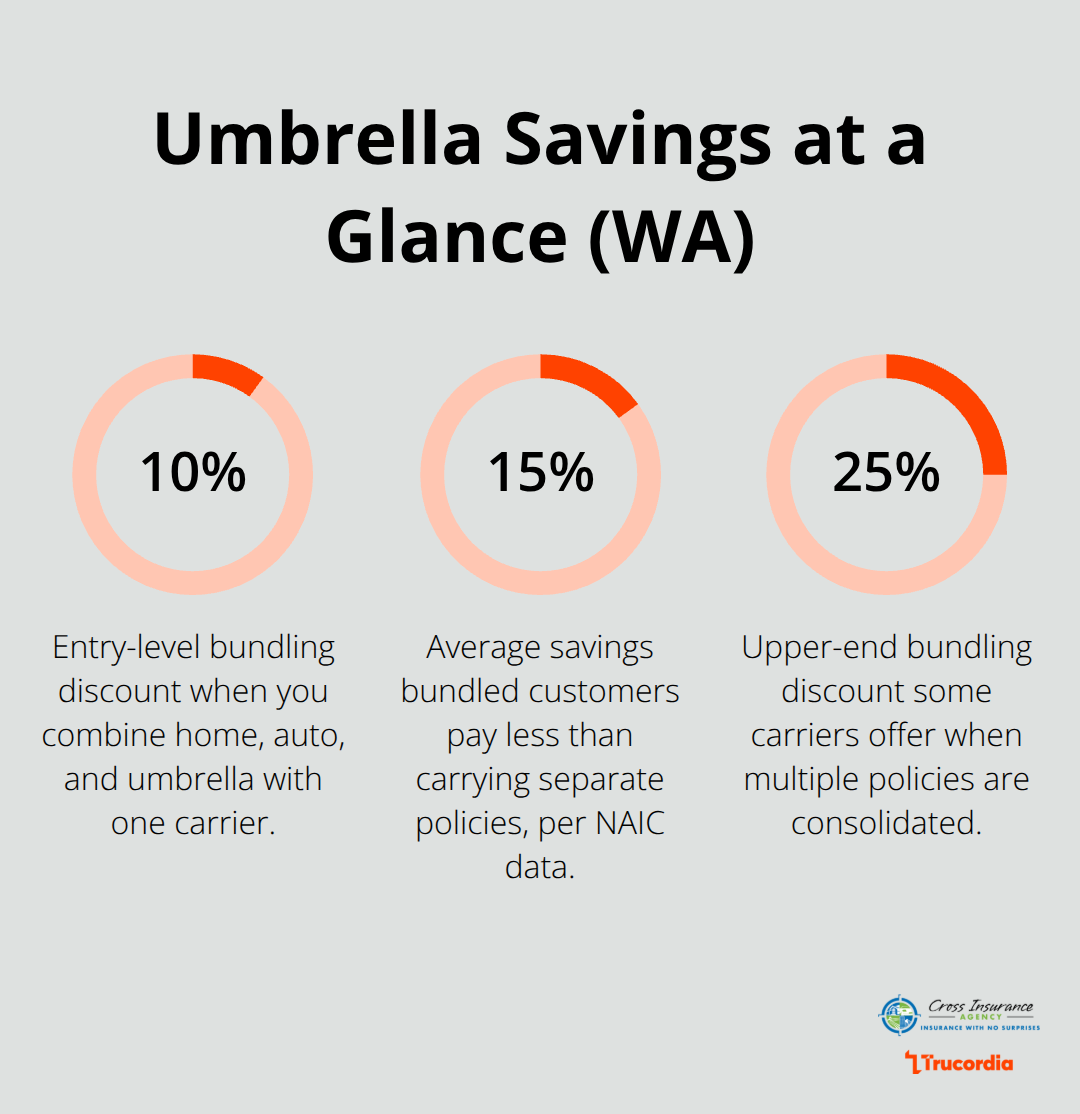
Bundling your umbrella policy with your homeowners and auto insurance typically produces the biggest savings. Carriers like State Farm, Allstate, and USAA offer bundling discounts ranging from 10 to 25 percent when you consolidate multiple policies. If you currently split your homeowners and auto coverage between two different companies, consolidating everything with one insurer can reduce your umbrella premium by $50 to $100 annually while simplifying your billing and claims process.

Percent savings from bundling and typical average discount for umbrella insurance in Washington - affordable umbrella insurance WA

The National Association of Insurance Commissioners data shows that bundled customers pay approximately 15 percent less on average than those who carry separate policies.

Work With a Local Broker to Compare Options

Shopping independently through online quote tools like The Zebra or Insurify gives you a starting point, but these platforms don’t capture regional carriers or the specialized pricing that independent brokers access. Local brokers in Washington maintain direct relationships with insurers and can negotiate rates that aren’t publicly available. An independent broker can access pricing from carriers that online tools never show, which means your actual lowest rate often sits outside what you find through standard quote websites. The process takes about 30 minutes: you provide your home value, auto information, claims history, and desired coverage limit, then a broker compares quotes from eight to twelve carriers simultaneously. This approach eliminates the tedious back-and-forth of calling individual companies and ensures you see every realistic option.

Optimize Your Deductible and Lock in Your Rate

After securing your quotes, review each policy’s deductible options. Most umbrella policies carry $0, $1,000, or $2,500 deductibles. Choosing a $2,500 deductible instead of $0 typically saves 10 to 15 percent on your premium, a worthwhile reduction if your underlying homeowners and auto policies have high deductibles. The final step involves locking in your rate before renewal periods pass. Umbrella insurance rates increase approximately 3 to 7 percent annually according to the Insurance Information Institute, so shopping every two to three years keeps your coverage competitive and prevents rate creep from eroding your savings.

Final Thoughts

Umbrella insurance isn’t a luxury reserved for the wealthy. At Cross Insurance Agency, we’ve helped hundreds of Washington residents add substantial liability protection for less than the cost of a monthly coffee subscription. A $1 million umbrella policy costs $150 to $300 annually, yet a serious injury lawsuit or multi-car accident can easily exceed $1 million in damages. Standard homeowners and auto policies leave you exposed once their limits are exhausted, and that gap represents your real financial risk.

Your next step is straightforward: calculate your total assets and income, determine how much coverage makes sense for your situation, then shop multiple carriers to find the best rate. Rate differences between insurers consistently exceed $300 annually for identical coverage, which means shopping strategically saves real money over time. Bundling your umbrella policy with your homeowners and auto insurance typically produces the biggest discounts, often reducing your total premium by 10 to 25 percent.

We at Cross Insurance Agency shop multiple top-rated carriers to find you the coverage and price that fit your specific situation. Contact us to review your coverage gaps and get quotes from carriers that match your needs and budget for affordable umbrella insurance in WA.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Your standard homeowners or auto insurance policy has limits. When a major accident happens, those limits can leave you exposed to significant out-of-pocket costs.

Umbrella insurance fills that gap by providing additional liability coverage above your existing policies. At Cross Insurance Agency, we help Olympia residents get umbrella insurance quotes that match their actual protection needs without overpaying.

What Umbrella Insurance Actually Covers

How Umbrella Policies Work

Umbrella insurance sits on top of your existing homeowners and auto policies, activating when liability claims exceed those policy limits. Most homeowners policies cap liability at $300,000 to $500,000. A single serious accident-a guest injured at your home, a car crash where you’re found liable-can easily generate medical bills, legal fees, and court judgments that surpass these limits.

Diagram showing how umbrella insurance adds extra liability protection above homeowners and auto policies, covering large claims and legal costs.

According to the Insurance Information Institute, the average homeowners liability claim runs around $17,059, but catastrophic cases routinely reach $1 million or more. Umbrella policies typically start at $1 million in coverage and extend to $5 million or higher, filling that dangerous gap between your standard policy limits and actual financial exposure.

Why the Cost Stays Low

The premium for $1 million in umbrella coverage typically runs $150 to $300 annually for most Olympia residents, making it one of the cheapest forms of comprehensive protection available. The cost remains surprisingly low because the umbrella only pays after your underlying policies are exhausted. A single lawsuit can cost far more in legal defense alone, so the math is straightforward: umbrella insurance is affordable protection against financial catastrophe.

Who Actually Needs This Coverage

Your actual risk profile determines whether umbrella coverage makes sense. If you own a home, drive regularly, or have significant savings or retirement accounts, a major liability judgment can wipe out years of financial progress. A jury award of $2 million for a serious injury happening on your property would devastate most households. Umbrella policies also protect against certain liability gaps your standard policies might not cover, and they provide legal defense coverage that activates immediately (without waiting for your underlying policy to respond first).

Moving Forward With Protection

The financial exposure from a major accident is real, not theoretical. Waiting until after an accident to wish you had umbrella coverage means waiting too long. Your next step involves understanding what coverage limits actually make sense for your specific situation and assets.

How to Get Umbrella Insurance Quotes in Olympia

Gather Your Current Policy Information

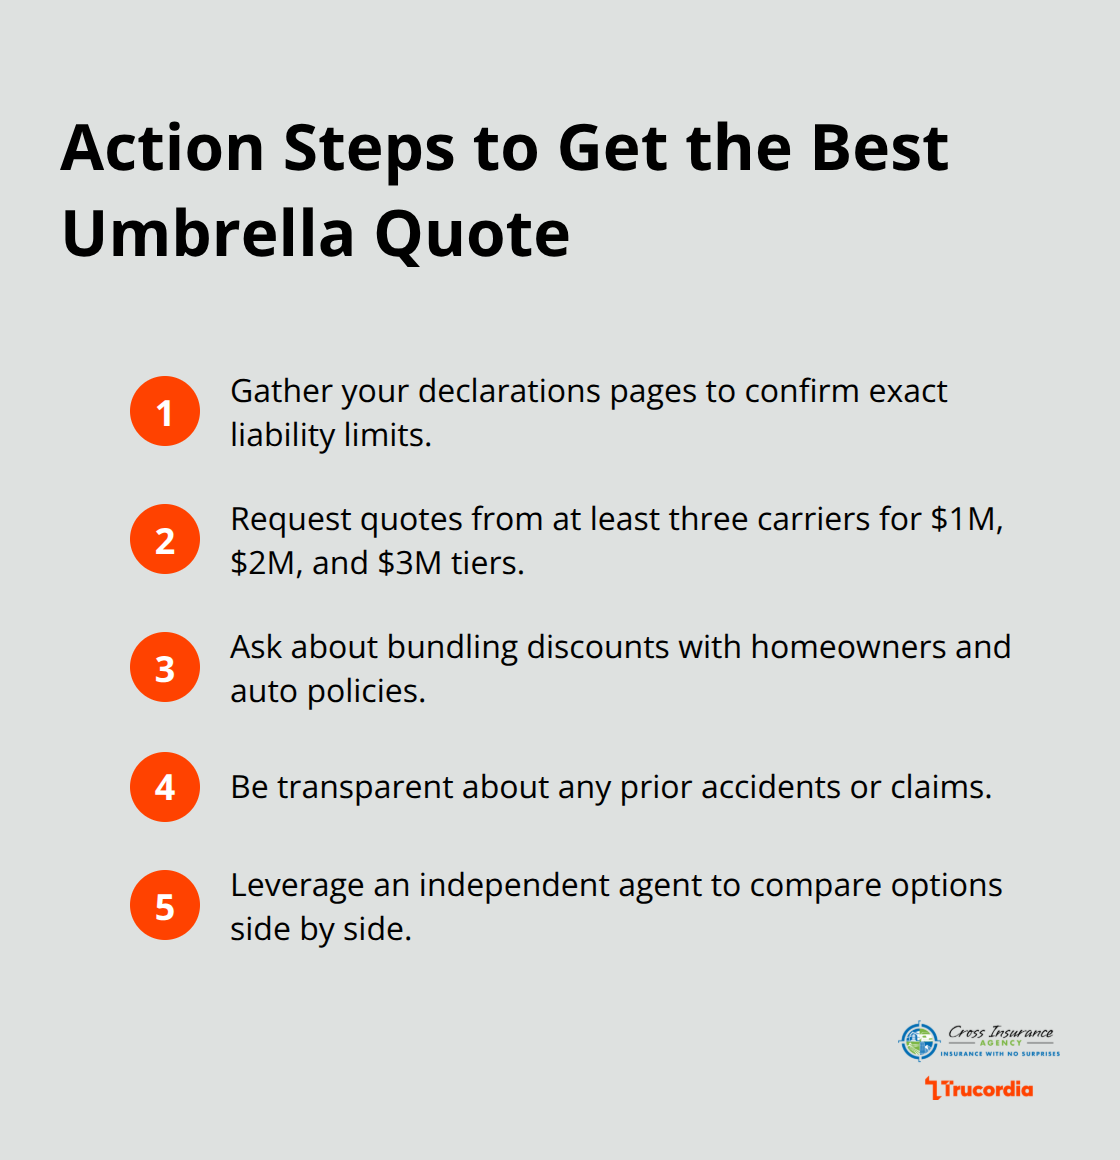
Pull together your current policy documents from your homeowners and auto insurance. You need the exact liability limits on each policy-not estimates, but the actual numbers from your declarations pages. Contact your existing insurers directly and ask them to list your current coverage limits in writing. This takes fifteen minutes and eliminates guesswork when you approach umbrella carriers.

Many insurers require that you maintain minimum underlying coverage before they’ll write an umbrella policy, typically $300,000 for homeowners and $250,000 for auto liability. Knowing your exact numbers prevents wasted conversations with carriers who won’t quote you.

Compare Multiple Carriers and Coverage Levels

Shopping multiple carriers for umbrella coverage reveals significant price differences. Contact at least three carriers and request quotes for $1 million, $2 million, and $3 million coverage levels so you understand how premiums scale with higher limits. This comparison shows you exactly what each coverage tier costs and helps you identify which carrier offers the best value for your needs.

Some insurers focus heavily on bundling discounts, offering substantial savings if you purchase umbrella coverage alongside your existing homeowners and auto policies. Others price aggressively on standalone quotes.

Compact checklist of steps to gather limits, compare carriers and tiers, consider bundling, disclose claims, and work with an independent agent. - umbrella insurance quotes Olympia

Understand How Your History Affects Your Rate

Your claims history matters for umbrella pricing. Insurers view your past behavior as a predictor of future risk, so transparency about any accidents or claims works in your favor when carriers evaluate your application.

Work with an Independent Agent

An independent agent shops top-rated carriers and presents you with multiple options showing exact premiums for each coverage level. This approach eliminates the need to contact insurers independently and ensures you’re comparing apples to apples across different companies. Your agent also identifies which carriers offer the best rates for your specific risk profile and can explain any coverage differences between quotes.

The quotes you receive will vary based on your assets, location, and claims history-but the process itself remains straightforward. Once you’ve collected multiple quotes and understand how your risk profile affects pricing, you’re ready to evaluate which coverage limits actually protect your financial situation.

Factors That Affect Your Umbrella Insurance Cost

Your Existing Liability Limits Set the Foundation

Your umbrella insurance cost reflects specific factors that insurers measure and price accordingly. Your existing liability limits on your homeowners and auto policies form the foundation of umbrella pricing. Carriers require minimum underlying coverage before they quote you, typically $300,000 for homeowners liability and $250,000 for auto liability. If your current limits fall below these thresholds, you must increase them first, which costs money upfront. However, this creates an advantage: carriers often bundle discounts when you increase underlying coverage and add umbrella protection simultaneously, sometimes offsetting the cost of raising those base limits. The higher your underlying limits already sit, the lower your umbrella premium typically runs, because the insurer’s actual exposure diminishes.

Claims History and Risk Profile Impact Your Rate

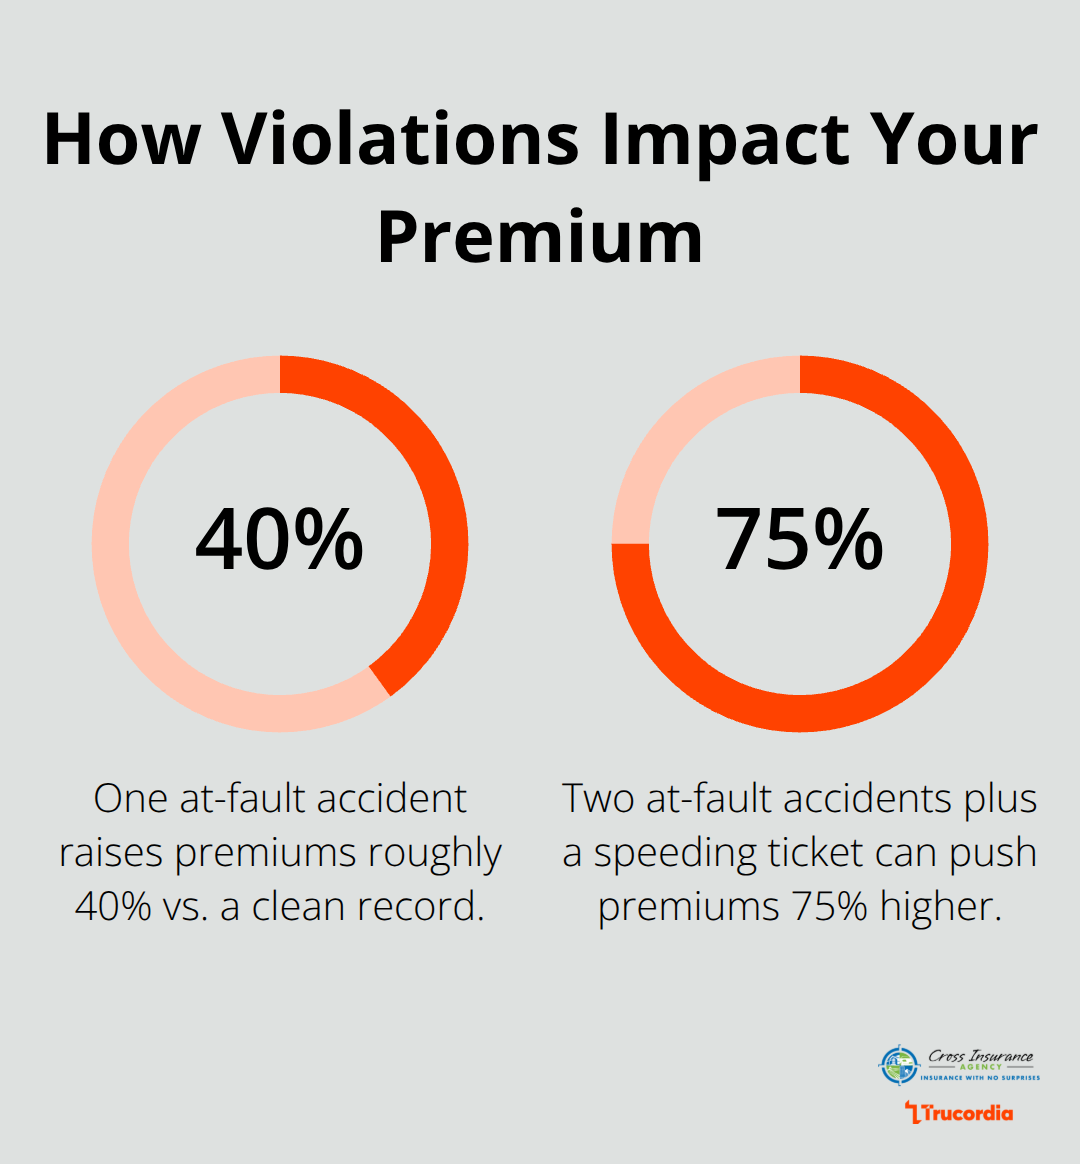
Your claims history and risk profile directly impact what you pay. Insurers pull your loss history from the Comprehensive Loss Underwriting Exchange, a database that tracks insurance claims across the industry. A single at-fault accident or homeowners claim from the past three to five years can increase your umbrella quote by 15 to 25 percent. Multiple claims signal higher risk and generate premiums that reflect that exposure.

Bar chart showing premium increase percentages tied to past claims over the last 3–5 years. - umbrella insurance quotes Olympia

Your occupation matters too-contractors, landlords, and business owners face higher rates than salaried employees with comparable assets.

Property Features and Liability Exposure

Homeowners with swimming pools, trampolines, or rental properties on their property see higher premiums because these features create documented liability exposure. These additions represent measurable risk that insurers price into your quote. The presence of these features doesn’t disqualify you from coverage; it simply means your premium reflects the actual exposure they create.

Coverage Amount and Deductible Selection

The coverage amount you select scales the premium accordingly. A $1 million policy typically costs $150 to $300 annually for standard risk profiles in Washington, while $2 million coverage runs roughly $300 to $450, and $3 million extends to $500 to $700. The cost per million decreases as you increase limits, making higher coverage tiers more economical than they initially appear. Deductible selection affects your rate as well-choosing a $10,000 deductible instead of $1,000 can reduce your premium by 10 to 15 percent, though this means you absorb more of smaller claims yourself.

Final Thoughts

Getting umbrella insurance quotes in Olympia takes less time than most people expect, and the protection costs far less than you anticipate. Start by gathering your current homeowners and auto policy documents, then contact at least three carriers for quotes at $1 million, $2 million, and $3 million coverage levels. This comparison reveals exactly how premiums scale and which carrier offers the best rate for your risk profile.

Your specific situation-your assets, your claims history, your property features-determines which coverage level actually protects you. An agent who understands Olympia’s market and knows multiple carriers identifies which companies offer the best rates for your profile and explains coverage differences you might otherwise miss. This personalized approach prevents you from either overpaying for unnecessary coverage or underbuying protection that leaves you exposed.

Contact Cross Insurance Agency for umbrella insurance quotes in Olympia and let us show you how affordable comprehensive protection actually is. A major liability judgment can wipe out years of financial progress, but umbrella coverage prevents that outcome for a surprisingly low annual cost. The time to act is now, before an accident forces you to wish you had this protection in place.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.

Your standard renters insurance policy has limits. Once you exceed those limits after an accident or injury on your rental property, you’re personally responsible for the rest.

A renters umbrella policy in WA fills that gap by providing additional liability coverage when your base policy maxes out. At Cross Insurance Agency, we see tenants underestimate their exposure to serious claims all the time.

This guide walks you through what umbrella coverage actually protects, why Washington renters need it, and how to get the right limits for your situation.

How Umbrella Coverage Works Beyond Your Base Policy

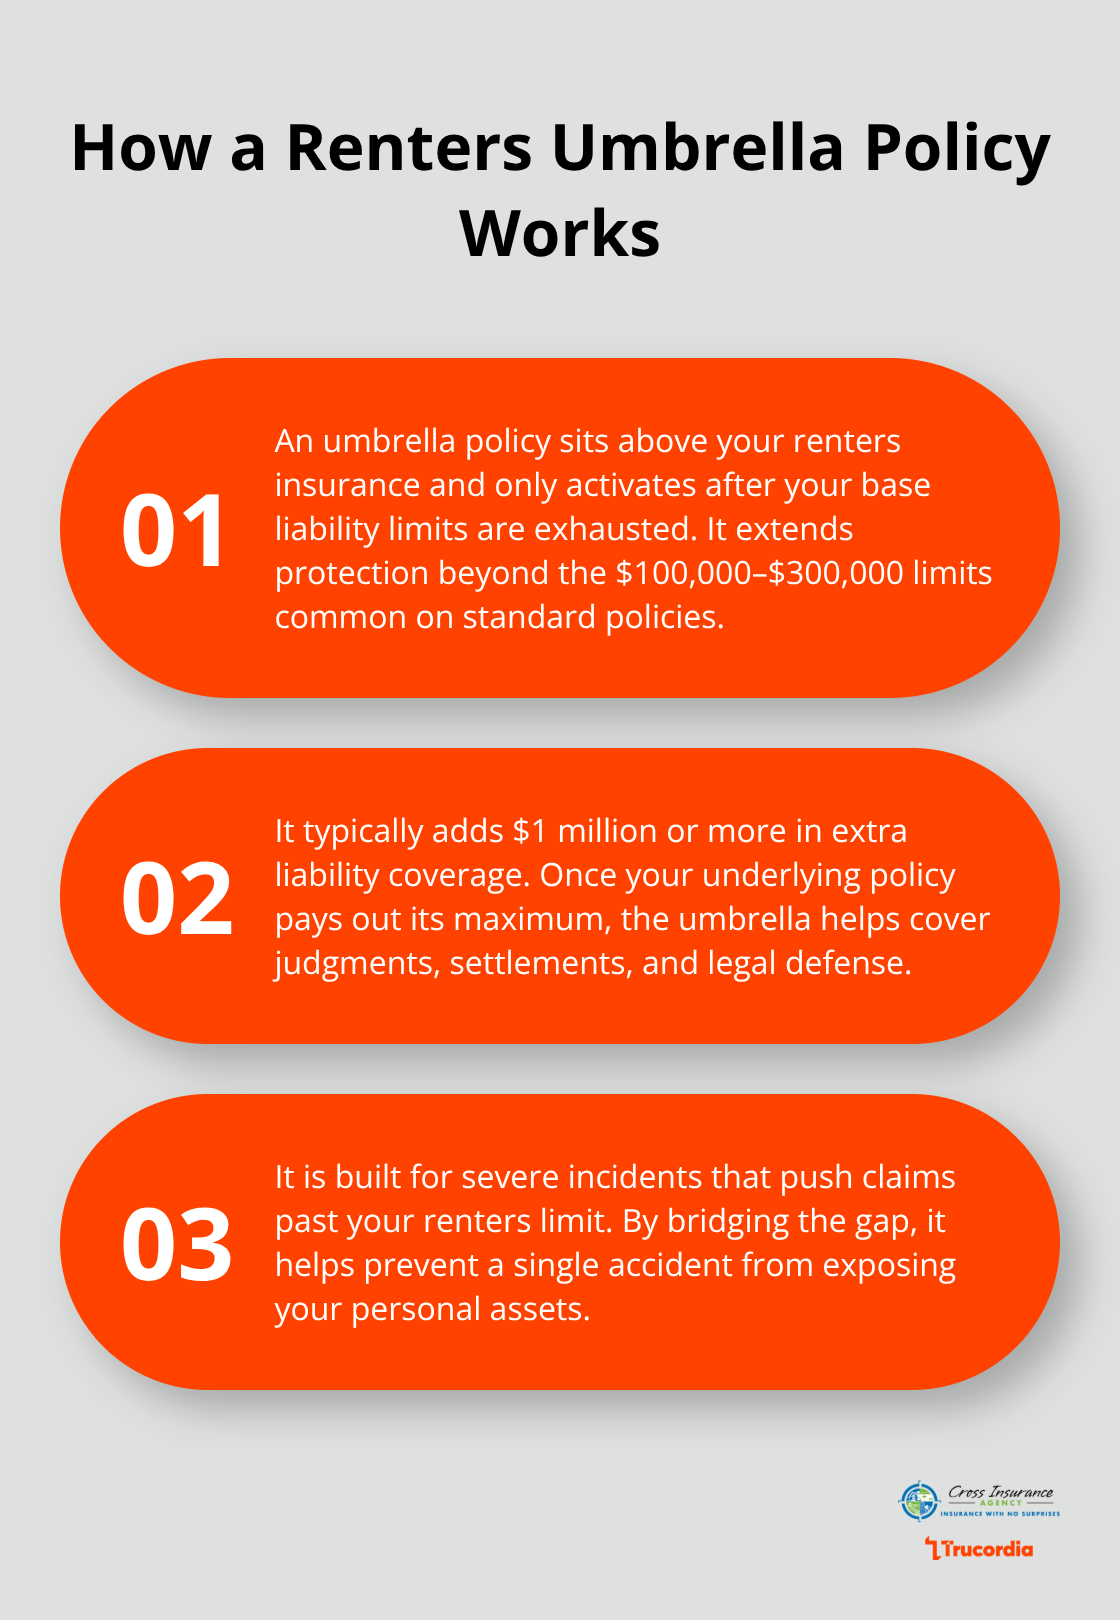
An umbrella policy sits on top of your renters insurance and activates only when your base coverage limits are exhausted. Your standard renters policy typically covers liability up to $100,000 or $300,000 depending on what you selected. Once you hit that ceiling after a serious accident or injury claim, the umbrella kicks in and provides an additional layer of protection-commonly $1 million or more.

One slip-and-fall incident with multiple injuries or significant property damage can easily push claims past a $300,000 threshold. Medical expenses alone accumulate fast: a single hospital stay combined with ongoing physical therapy and lost wages for an injured guest can exceed standard coverage in weeks. The umbrella policy covers the gap between what your renters insurance pays out and what the injured party receives in a judgment or settlement.

Three key ways an umbrella policy extends protection beyond a standard renters insurance policy. - renters umbrella policy WA

What Umbrella Coverage Actually Protects

Your umbrella policy covers the same types of liability your renters insurance does-bodily injury to someone on your rental property, property damage you cause to a neighbor’s home or belongings, and legal defense costs. If a guest slips on your kitchen floor and suffers a serious back injury, or if you accidentally damage your landlord’s walls during a party, umbrella coverage steps in once your base limits run dry.

The umbrella also covers some incidents your base renters policy might exclude or limit, though you should always verify the exact terms with your agent.

One critical difference: umbrella policies require that you maintain minimum liability limits on your underlying renters insurance-usually at least $300,000-before the umbrella will pay anything. You cannot purchase umbrella coverage in isolation; it depends entirely on your base renters policy being in place and active.

Renters Insurance Versus Umbrella Protection

Renters insurance and umbrella coverage serve different functions, and most Washington tenants need both. Your renters policy covers your personal belongings inside the rental unit (furniture, electronics, clothing) plus provides that baseline liability protection. An umbrella policy never covers your belongings; it only adds extra liability protection when your base policy limits are maxed out.

Think of renters insurance as your foundation and umbrella as your reinforcement. The cost difference is substantial: renters insurance in Washington averages around $15 to $25 monthly, while umbrella coverage typically runs $100 to $300 annually for $1 million in additional limits.

Many tenants assume their renters policy is enough because they focus on the personal property coverage, but they overlook how quickly liability claims escalate. A dog bite, a guest injury, or accidental damage to the rental unit itself can generate legal fees and medical costs that demolish standard coverage limits within days. Bundling renters and umbrella policies through one agent often unlocks discounts that reduce the total cost of both, making the extra protection affordable.

Why Your Liability Exposure Matters More Than You Think

A single serious incident can expose you to financial ruin if your coverage stops short. The gap between your base policy limit and a real-world judgment is where your personal assets become vulnerable. Understanding this gap is the first step toward protecting yourself-and it’s exactly what the next section addresses as we look at the specific liability risks Washington renters face.

Why Washington Renters Face Real Liability Exposure

The True Cost of a Single Claim

Washington renters underestimate their exposure to serious liability claims because they assume worst-case scenarios happen to other people. They don’t. A guest fractures their ankle on your apartment stairs and sues. Medical bills plus lost wages quickly climb to $250,000. Your standard renters policy maxes out. You now face personal liability for everything above that threshold, and Washington courts award substantial damages.

Hub-and-spoke view of the key cost drivers that make liability claims large for Washington renters.

A single incident-a dog bite requiring reconstructive surgery, a party guest injured in a fall, water damage you cause to a neighbor’s unit-generates medical expenses, legal fees, and settlement costs that demolish $100,000 or $300,000 limits in weeks.

How Quickly Property Damage Claims Escalate

Property damage claims escalate just as fast as injury claims. If you accidentally damage your landlord’s walls during a move or a guest spills wine on expensive flooring, repair costs combined with liability for the landlord’s lost rental income during repairs easily exceed standard coverage. Washington’s higher cost of living means medical care and property values drive claim amounts higher than the national average. Renters in Seattle, Tacoma, and Vancouver face even steeper exposure because housing costs and associated property values inflate damage assessments.

The Gap Between Coverage and Reality

Standard renters insurance was designed decades ago when liability claims averaged far less. Today’s medical costs, legal fees, and jury awards have outpaced those old limits. A serious claim doesn’t require a catastrophic accident-it requires one guest injury, one property damage incident, or one liability lawsuit that your base policy cannot fully cover. Washington renters who carry only standard renters insurance gamble that they’ll never face a claim large enough to expose their personal assets. Tenants with umbrella coverage eliminate that gamble entirely.

The Real Price of Protection

The cost of umbrella coverage is modest: policies run $100 to $300 yearly for $1 million in additional limits, yet they protect everything you own from judgment creditors. Without that protection, a single claim triggers wage garnishment, asset seizure, and years of financial recovery. Washington renters who work hard to build savings and own vehicles or investments cannot afford to skip this layer of protection. What separates renters who stay protected from those who face financial devastation is whether they acknowledge this gap exists and take action to close it. The next section shows you exactly how to assess your own liability exposure and determine what coverage limits make sense for your situation.

Getting the Right Umbrella Coverage for Your Situation

Calculate Your Actual Liability Exposure

Start by calculating what you actually own and what a serious claim could cost you. Most Washington renters focus only on their renters insurance deductible and forget that liability exposure extends far beyond that. If someone sues you after an injury on your rental property, they’re not just claiming medical bills-they’re claiming lost wages, pain and suffering, and punitive damages in cases of gross negligence. A jury in King County or Pierce County can award six figures easily. Add legal defense costs (which umbrella policies cover) and you’re looking at totals that shred a $300,000 limit.

What are your monthly earnings? What assets do you own-savings, a vehicle, investments? What’s your net worth? That number determines your minimum umbrella limit. If you earn $4,000 monthly and have $50,000 in savings plus a vehicle worth $15,000, you need enough coverage to protect that $65,000 base plus future earnings.

Determine Your Umbrella Limit

Most Washington renters should carry at least $1 million in umbrella limits, and many should consider $2 million. The annual cost difference between $1 million and $2 million is roughly $100 to $150, making the upgrade nearly negligible compared to the protection it provides. Your renters insurance agent can help you determine exact limits, but don’t accept their first recommendation without pushback. Agents often suggest $1 million as a default, which works fine for renters with minimal assets but leaves others exposed.

Tell your agent your income, your assets, and ask them to calculate what a worst-case liability claim could look like in your specific situation. Then ask what umbrella limit covers that exposure completely.

Bundle Coverage and Shop Multiple Carriers

When you bundle renters and umbrella coverage through one agent or carrier, discounts typically drop your combined annual cost to $200 to $400-far cheaper than the financial devastation of a single uninsured claim. Independent brokers shop multiple carriers to find the best rates, which matters because umbrella pricing varies dramatically between insurers. A policy that costs $300 annually through one carrier might cost $150 through another.

Get Multiple Quotes and Verify Your Foundation

Don’t settle for the first quote. Get three quotes minimum before deciding, and verify that your base renters policy maintains the minimum liability limits your umbrella requires-usually $300,000. Without that foundation, your umbrella won’t activate when you need it most.

Checklist of practical steps to size and buy umbrella coverage for Washington renters. - renters umbrella policy WA

Final Thoughts

A renters umbrella policy in WA protects your financial future when a single liability claim exceeds your base renters insurance limits. Standard renters coverage maxes out fast, medical costs and legal fees escalate quickly, and Washington courts award substantial damages. Without umbrella protection, your personal assets face seizure and wage garnishment after a serious claim.

The cost of inaction far outweighs the cost of coverage-umbrella policies run $100 to $300 annually for $1 million in additional limits, yet they protect everything you own. Most Washington renters should carry at least $1 million in umbrella limits, and many benefit from $2 million. Bundling renters and umbrella coverage through one agent typically reduces your combined annual cost to $200 to $400 while delivering the protection you actually need.

Your next step is simple: calculate what you own, determine your liability exposure, and contact Cross Insurance Agency to get multiple quotes from top-rated carriers. Our licensed agents work with you to assess your actual liability exposure and recommend limits that match your situation, not generic defaults. We handle the complexity so you can focus on what matters.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Driving in Centralia, WA comes with its own set of challenges-from wet winter roads to local traffic patterns that demand the right coverage. At Cross Insurance Agency, we know that driver insurance in Centralia isn’t one-size-fits-all.

This guide walks you through the coverage types that matter, how to find the right local provider, and what questions to ask before you commit to a policy.

Why Driver Insurance Matters in Centralia

Washington State’s Legal Requirements for Auto Insurance

Washington State requires every driver to carry a minimum of $25,000 in bodily injury liability per person, $50,000 per accident, and $10,000 in property damage liability. This is the floor, not a recommendation. Most drivers in Centralia operate below adequate protection levels at these minimums.

Comparison of Washington State minimum auto liability limits versus recommended coverage levels for Centralia drivers. - driver insurance Centralia WA

If you cause an accident that injures multiple people or damages expensive property, personal liability will far exceed what state minimums cover. We recommend liability limits of at least $100,000 per person and $300,000 per accident for most drivers, especially those with assets worth protecting.

How Local Driving Conditions Affect Your Coverage Needs

Centralia’s location on Interstate 5 creates specific driving hazards that affect what coverage you actually need. Winter weather brings wet roads from November through March, and the National Highway Traffic Safety Administration reports that wet pavement contributes to nearly 1.2 million crashes annually across the United States. Rain-related accidents spike significantly in this region. The I-5 corridor near Centralia also experiences heavy commercial truck traffic, which increases the severity of collisions when they occur.

Collision and comprehensive coverage become more valuable here than in drier climates because weather-related claims happen frequently. Local claims data shows that comprehensive coverage claims in Washington increase substantially during winter months, making this protection practical rather than optional for Centralia drivers.

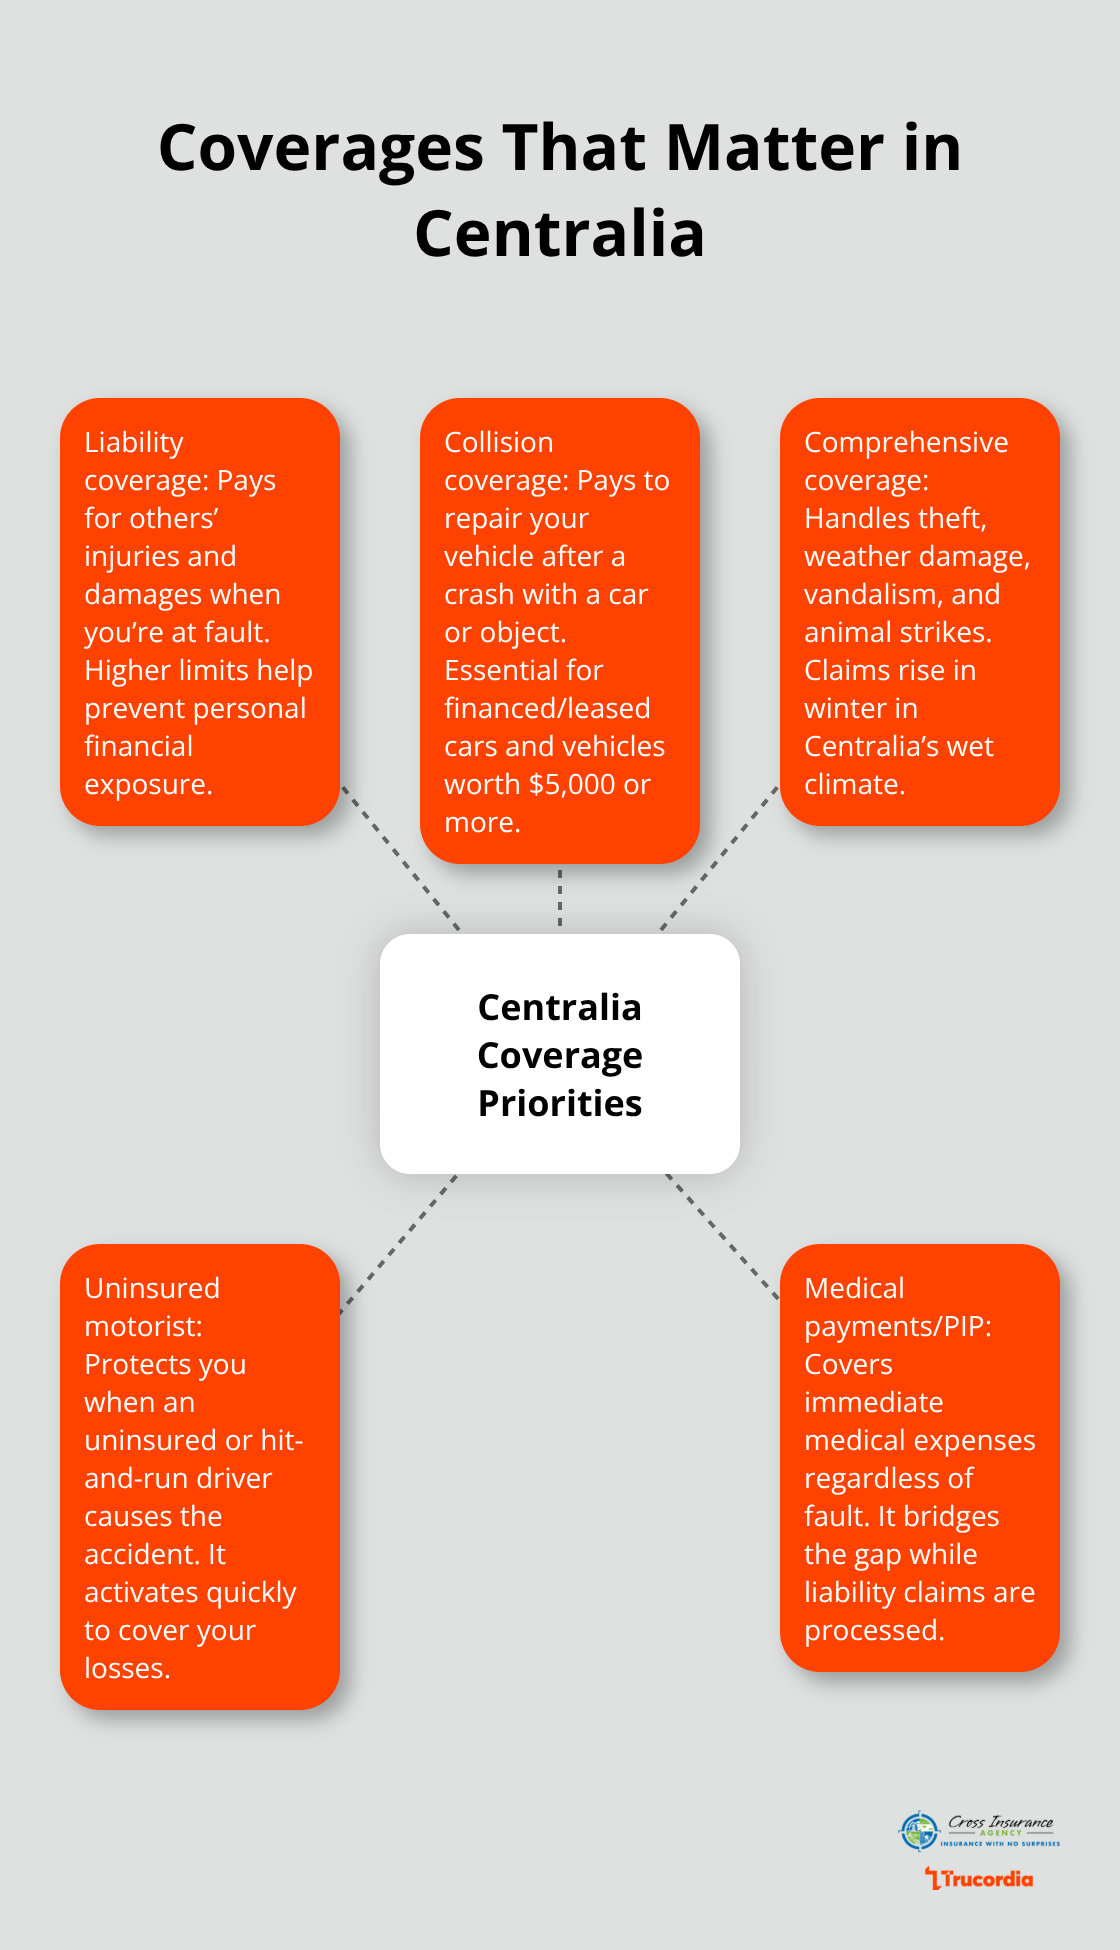
Hub-and-spoke visual showing key auto coverages for Centralia drivers and what each protects. - driver insurance Centralia WA

Common Accidents and Claims in Centralia

Common accidents in the Centralia area include rear-end collisions during wet conditions, weather-related single-vehicle accidents, and multi-vehicle pile-ups on I-5 when visibility drops. Property damage claims from hail and falling debris also appear regularly in this region.

Uninsured motorist protection matters more in Washington than many drivers realize because approximately 12 percent of drivers on Washington roads carry no insurance at all. If an uninsured driver hits you, your own coverage fills the gap. Without this protection, you would have to pursue the other driver through civil court, which is expensive and often unsuccessful if they lack assets.

Personal injury protection or medical payments coverage handles your medical bills immediately after an accident, regardless of fault, and prevents you from relying on your health insurance for accident-related injuries. These coverage types transform from optional add-ons into practical necessities when you drive regularly in Centralia’s traffic environment. Understanding what each type protects sets the foundation for selecting the right policy-and knowing which coverage options actually fit your situation requires looking at the specific types available to you.

Coverage Types That Protect You

Liability Coverage: Your Legal Foundation

Liability coverage is where your legal obligation begins, and Centralia drivers frequently underestimate how quickly claims exceed state minimums. When you cause an accident, liability covers the other person’s medical bills, lost wages, vehicle repairs, and pain and suffering damages. Washington courts have awarded settlements exceeding $500,000 in cases involving serious injuries, yet many drivers maintain only the state minimum of $50,000 per accident. That gap creates personal financial exposure.

We recommend $100,000 per person and $300,000 per accident as the practical floor for anyone with a home, savings, or regular income. The cost difference between minimum and adequate coverage runs typically $15 to $30 monthly, which is negligible compared to the protection gained.

Collision and Comprehensive: Protecting Your Vehicle

Collision and comprehensive coverage protects your vehicle itself rather than others’ property. Collision pays for damage when you hit another car or object, while comprehensive handles theft, weather damage, vandalism, and animal strikes. In Centralia’s wet climate, comprehensive claims spike during winter months when hail, falling branches, and flooding damage vehicles regularly.

Collision becomes essential if you financed or leased your vehicle because lenders require it, but it matters equally for owned vehicles worth $5,000 or more. The deductible you choose directly impacts your premium-raising it from $500 to $1,000 typically saves $100 to $150 annually. Only choose a deductible you can actually pay out of pocket when a claim occurs.

Uninsured Motorist Protection: Covering the Gaps

Uninsured motorist coverage protects you when an uninsured or hit-and-run driver causes the accident. In 2023, 15.4 percent of motorists, or more than one in seven drivers, were uninsured, according to a 2025 Study by the Insurance Research Council (IRC). This coverage activates quickly and prevents you from bearing the financial burden of someone else’s lack of insurance.

Medical Payments and Injury Protection

Medical payments or personal injury protection covers your immediate medical expenses after any accident, regardless of fault, which prevents gaps between accident treatment and health insurance processing. This coverage activates within days while liability claims take months to resolve, making it valuable for accident-related injuries requiring immediate care. These coverage types transform from optional add-ons into practical necessities when you drive regularly in Centralia’s traffic environment, and selecting the right combination requires understanding how each one works with your specific situation and driving habits.

Finding the Right Local Insurance Provider

Why Independent Agents Understand Centralia’s Specific Risks

Independent agents in Centralia operate differently than national call centers or online quote engines because they carry relationships with multiple carriers and understand local claims patterns. Licensed agents shop coverage options across top-rated carriers rather than pushing you toward one company’s products. This matters in Centralia because weather-related claims spike predictably each winter, and agents who handle these claims regularly know which carriers respond fastest and which ones have stricter underwriting for drivers in high-risk corridors like I-5. When you call a national insurer’s 1-800 number, the representative rarely knows whether hail damage claims in your zip code take three weeks or three months to settle. Local agents do.

Comparing Quotes Requires More Than Price

Comparing quotes requires more than checking lowest price because the cheapest option often excludes coverage you actually need or includes deductibles that make claims impractical. When you request quotes from three different agents or carriers, bring the same coverage limits and deductibles to each one so you’re comparing apples to apples. A $500 deductible collision policy at $95 monthly means nothing if another quote offers $1,000 deductible at $75 monthly because the monthly savings disappear after your first accident.

Ask each agent to explain what their lowest quote excludes and why their recommended option costs more. The agent who takes time to explain the gaps rather than just showing you numbers will likely serve you better when you file a claim.

Key Questions Before You Commit to a Policy

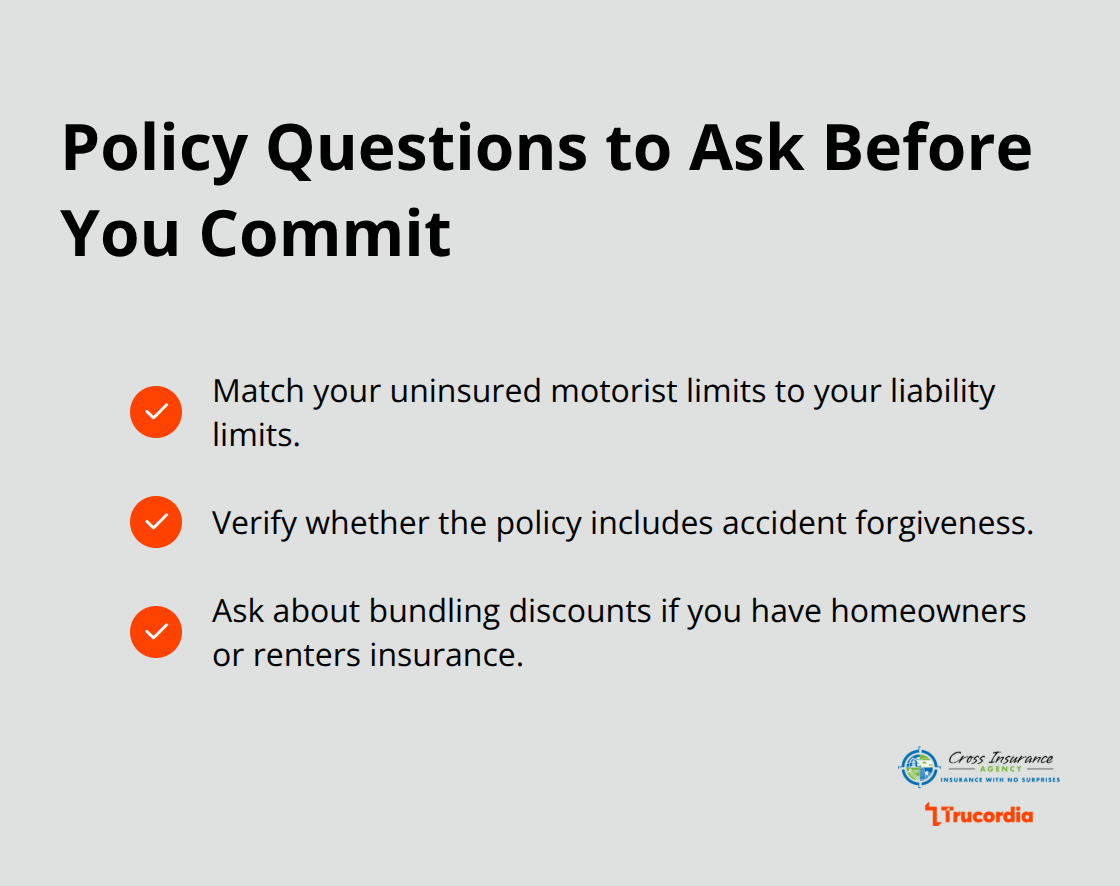
Before you commit to any policy, confirm that uninsured motorist coverage limits match your liability limits because having $100,000 liability protection but only $25,000 uninsured motorist coverage leaves you unbalanced. Also verify whether the policy includes accident forgiveness, which prevents your rates from jumping after your first claim. Ask about bundling discounts if you carry homeowners or renters insurance (these discounts often range from 10 to 25 percent depending on the carrier). These details separate policies that merely meet legal requirements from policies that actually protect you through Centralia’s specific driving environment.

Checklist of key questions to ask an agent before buying an auto policy in Centralia, WA.

Final Thoughts

Driver insurance in Centralia, WA protects your financial future against the specific risks you face on I-5 and local roads. State minimum coverage of $50,000 per accident leaves most drivers dangerously exposed, especially when wet winter conditions make collisions more severe and frequent. Adequate liability limits of $100,000 per person and $300,000 per accident cost only $15 to $30 more monthly than minimums, yet that difference prevents catastrophic personal liability if you cause a serious accident.

Collision and comprehensive coverage matter in Centralia’s climate because weather-related claims happen predictably each winter, while uninsured motorist protection addresses the reality that one in seven drivers on Washington roads carry no insurance at all. Medical payments coverage pays your accident-related medical bills immediately rather than waiting months for liability claims to resolve. These coverage types work together to create actual protection rather than just legal compliance.

Finding the right provider means working with someone who understands Centralia’s specific driving environment rather than relying on national call centers that treat your zip code like any other. Independent agents shop multiple carriers, know which companies respond fastest to local claims, and explain why certain coverage combinations make sense for your situation. Contact us today to get quotes tailored to Centralia’s specific driving environment.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.

Running multiple vehicles for your Olympia business creates complexity. Fuel costs, maintenance, insurance paperwork-it piles up fast.

Fleet insurance in Olympia, WA consolidates all your vehicles under one policy, cutting through the administrative headache. At Cross Insurance Agency, we help local businesses simplify their coverage and reduce costs.

Why Fleet Insurance Costs Less Than Multiple Individual Policies

Separate Policies Create Separate Expenses

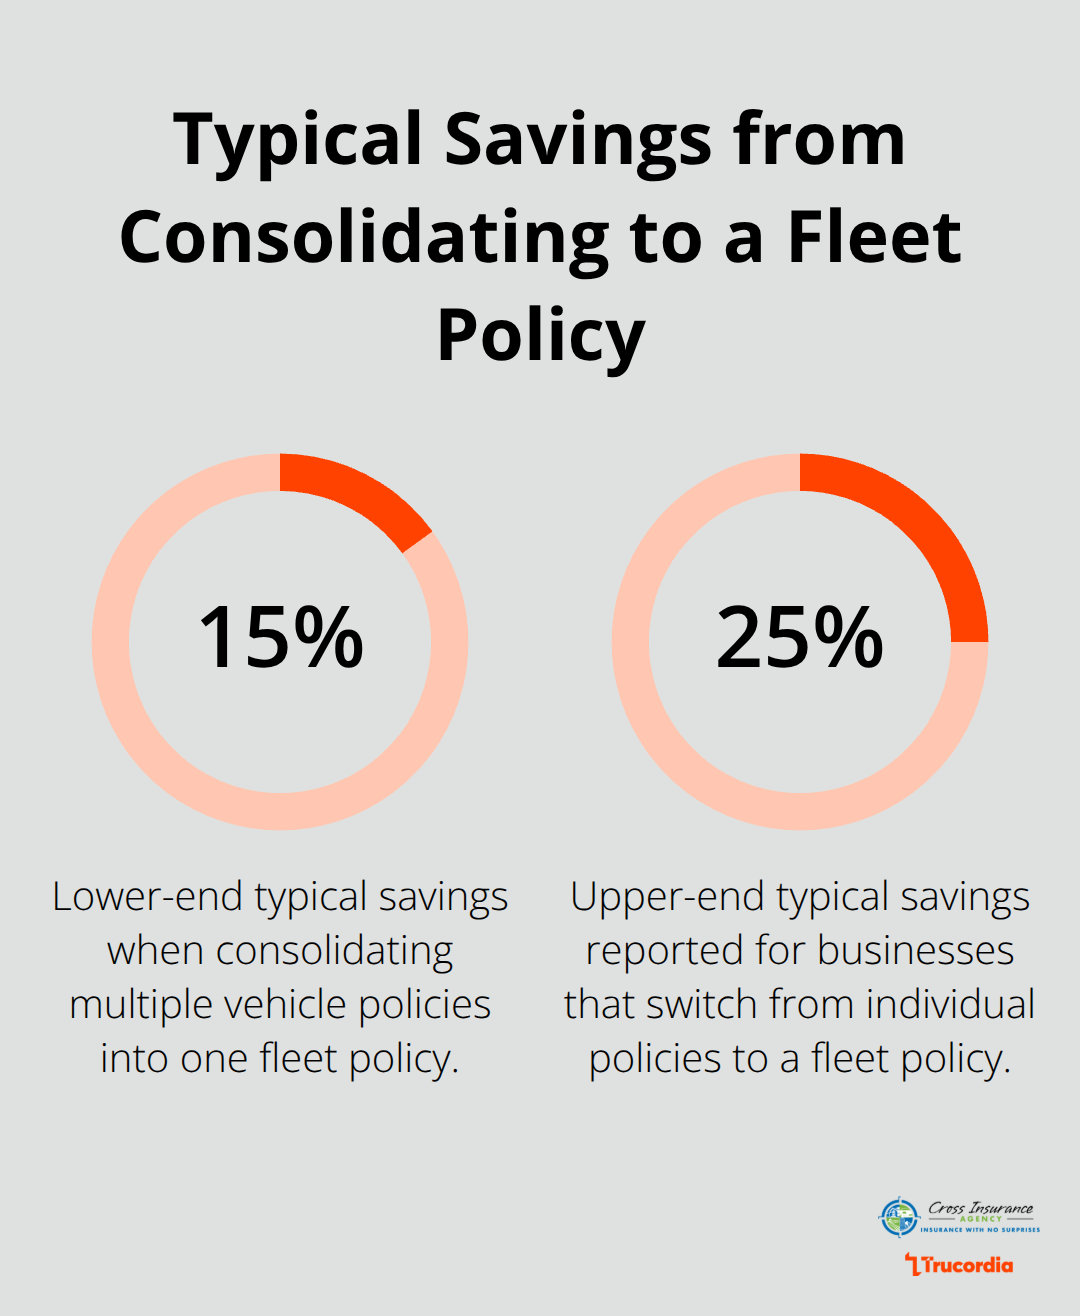
Managing vehicles separately means paying separate premiums, separate deductibles, and separate administrative fees for each vehicle. A business with five vehicles pays five different policy renewal dates, five separate invoicing processes, and five individual claims procedures. That’s inefficient and expensive. According to the National Association of Insurance Commissioners, businesses that consolidate their auto coverage typically save 15-25% compared to maintaining individual policies. The savings come from several sources: insurers offer volume discounts for fleets, you eliminate redundant administrative overhead, and you reduce the likelihood of coverage gaps between policies.

Chart showing 15% to 25% typical savings when businesses in Olympia, WA consolidate vehicles under one fleet insurance policy. - fleet insurance Olympia WA

Liability Exposure Multiplies Across Your Fleet

When you operate multiple vehicles, each one represents a separate liability risk. A delivery driver causes an accident. A service vehicle hits someone’s property. An employee uses a company vehicle for business purposes. If these vehicles sit on individual policies, you manage different coverage limits, different deductibles, and potentially different exclusions across your entire operation. One underinsured vehicle can expose your whole business to financial catastrophe. Fleet policies establish consistent liability protection across all vehicles, so you know exactly what protection you have, regardless of which vehicle is involved in an incident.

Washington state requires minimum liability coverage of $25,000 per person and $50,000 per accident, but most Olympia businesses operating multiple vehicles should carry higher limits. A commercial auto incident can easily exceed minimum requirements, and medical costs in Washington continue climbing.

One Point of Contact Accelerates Claims Resolution

When an accident happens, you don’t want to spend hours figuring out which policy covers which vehicle. Fleet insurance means one point of contact, one claims file, and one agent who understands your entire operation. This matters tremendously when you’re running a tight schedule. A plumbing company with four service vans loses productivity every minute those vehicles sit idle. A fleet policy speeds up the claims process because the carrier sees your entire business relationship, not just one vehicle. You also avoid the frustration of coverage disputes between multiple carriers.

As you evaluate fleet options for your Olympia operation, the next step involves understanding exactly what coverage types protect your business and how these policies actually work in practice.

What Your Fleet Policy Actually Protects

Commercial Auto Liability Covers Injuries and Property Damage

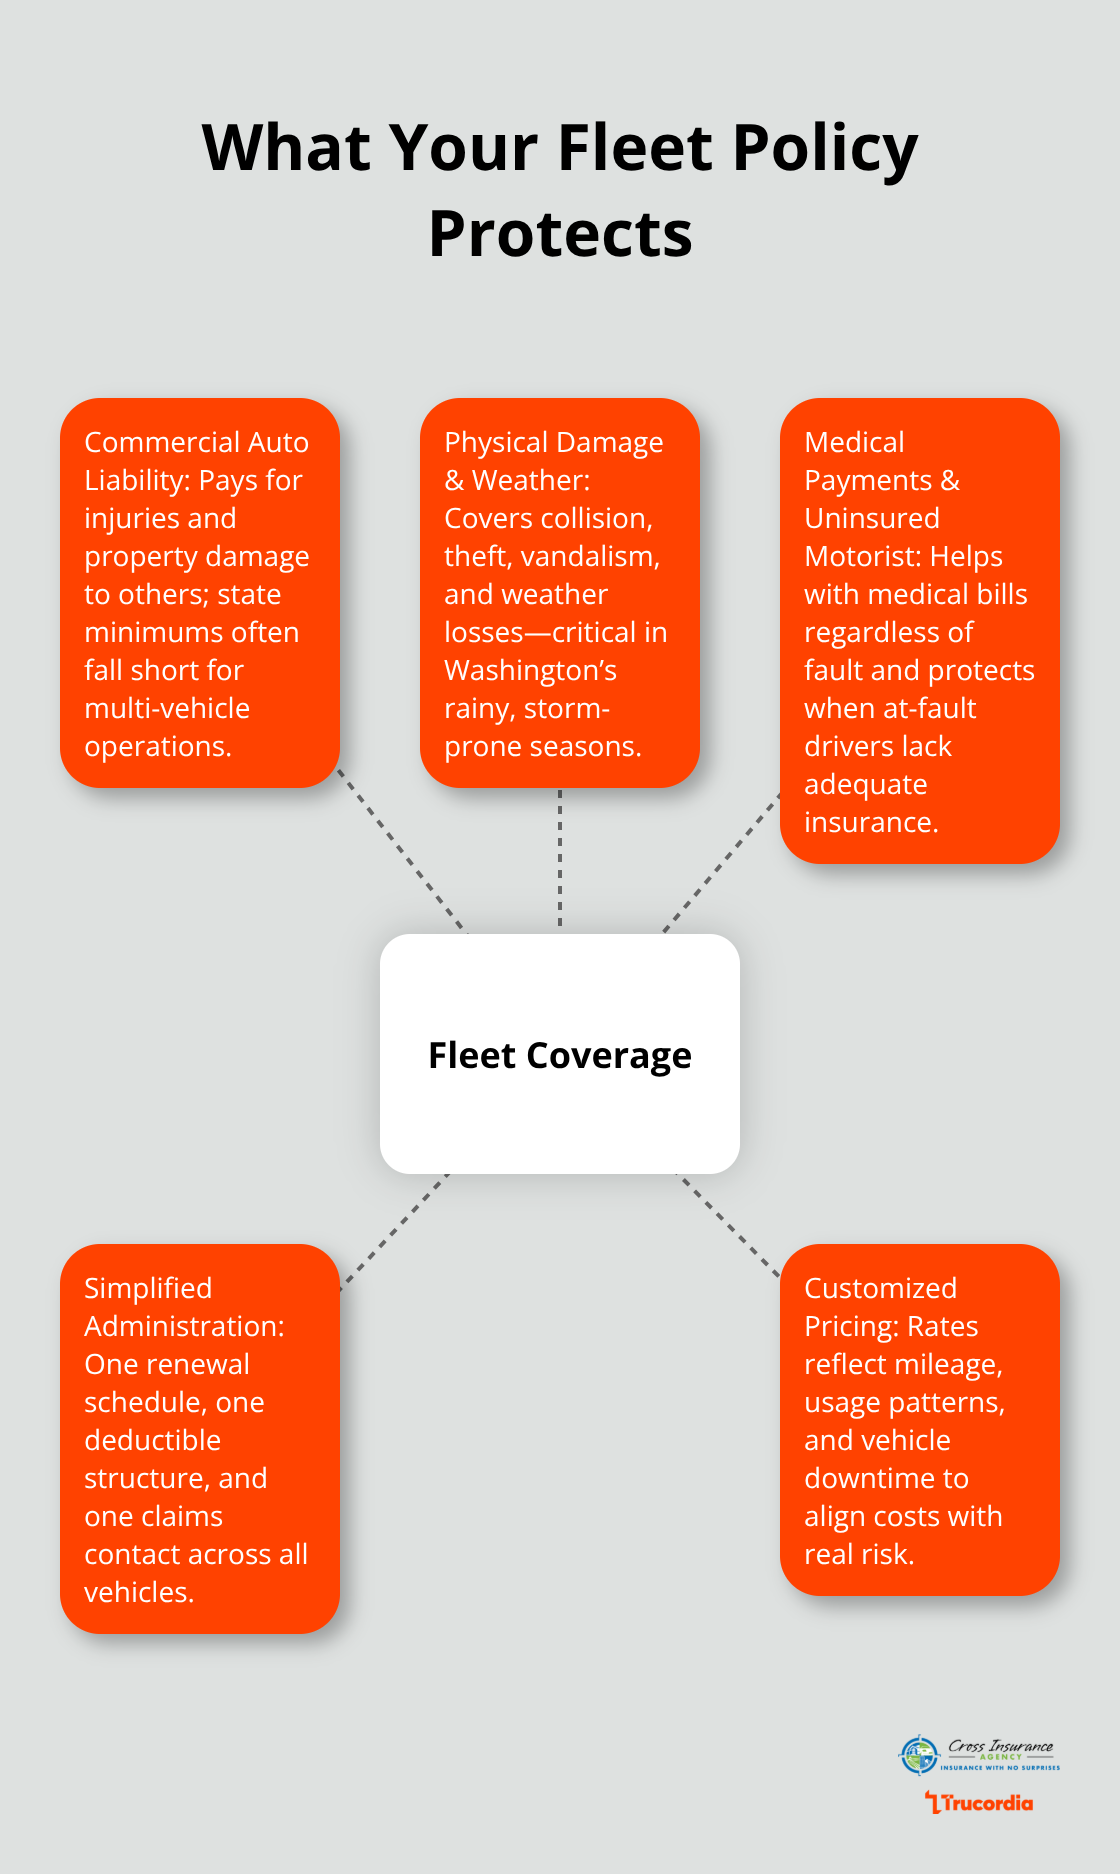
Commercial auto liability pays for injuries and property damage your vehicles cause to others, and this protection layer handles most claims. Washington’s minimum liability requirement of $25,000 per person and $50,000 per accident falls short for businesses running multiple vehicles. A serious accident involving a commercial vehicle generates medical bills exceeding $100,000 within hours, and jury awards in commercial liability cases frequently reach $250,000 to $500,000 or higher. Your fleet policy should carry limits that match your actual exposure, not just meet the state minimum.

Physical Damage and Weather Protection Matter in Washington

Physical damage coverage protects your own vehicles from collisions, theft, vandalism, and weather damage-a significant concern in Washington’s rainy climate where weather-related claims spike during fall and winter months. Your vehicles face constant exposure to rain, hail, and wind damage that individual drivers might ignore but fleet operators cannot afford to overlook. This coverage keeps your vehicles operational and prevents weather events from sidelining your business.

Hub-and-spoke diagram outlining key protections in a fleet insurance policy for Olympia, WA businesses.

Medical Payments and Uninsured Motorist Protection

Medical payments coverage pays hospital and medical bills for your drivers and passengers regardless of fault, which accelerates recovery and prevents employees from filing personal injury lawsuits against your business. Uninsured motorist protection covers your drivers when another vehicle hits them but that driver lacks adequate insurance-a situation that happens more frequently than most business owners realize. According to the Insurance Research Council, approximately one in eight drivers nationwide operates without insurance, and those uninsured drivers often cause accidents that leave your business footing the bill without this protection.

Simplified Administration Across Your Entire Fleet

Fleet policies consolidate all coverage types under a single renewal date, single deductible structure, and one point of contact for claims. Instead of managing five separate policies with different renewal dates scattered throughout the year, you handle one renewal cycle and one set of deductibles across your entire fleet. When a driver gets in an accident, you contact one agent who has immediate access to all your vehicle information, driver records, and coverage details rather than hunting through multiple policy documents. This operational efficiency means your office staff spends less time on insurance administration and more time running your business.

Customized Pricing Reflects Your Actual Operations

Fleet policies allow carriers to account for operational differences in your business. A delivery company with high-mileage vehicles pays different rates than a service company where vehicles sit parked most days. Pricing that reflects your real risk profile (rather than charging a generic commercial rate) means you avoid overpaying for coverage that doesn’t match your actual operations. Understanding how carriers evaluate your specific fleet sets the stage for finding the right plan that balances protection with cost.

Selecting Coverage That Matches Your Fleet’s Real Risk

The difference between adequate fleet insurance and overpaying for unnecessary coverage comes down to matching your policy to actual operations. Most Olympia businesses make one critical mistake: they accept whatever coverage limits their agent suggests without questioning whether those limits reflect their specific risk profile. A plumbing company with vehicles parked at job sites faces different exposure than a delivery service with high-mileage routes across multiple counties.

Document Your Fleet’s Actual Operations

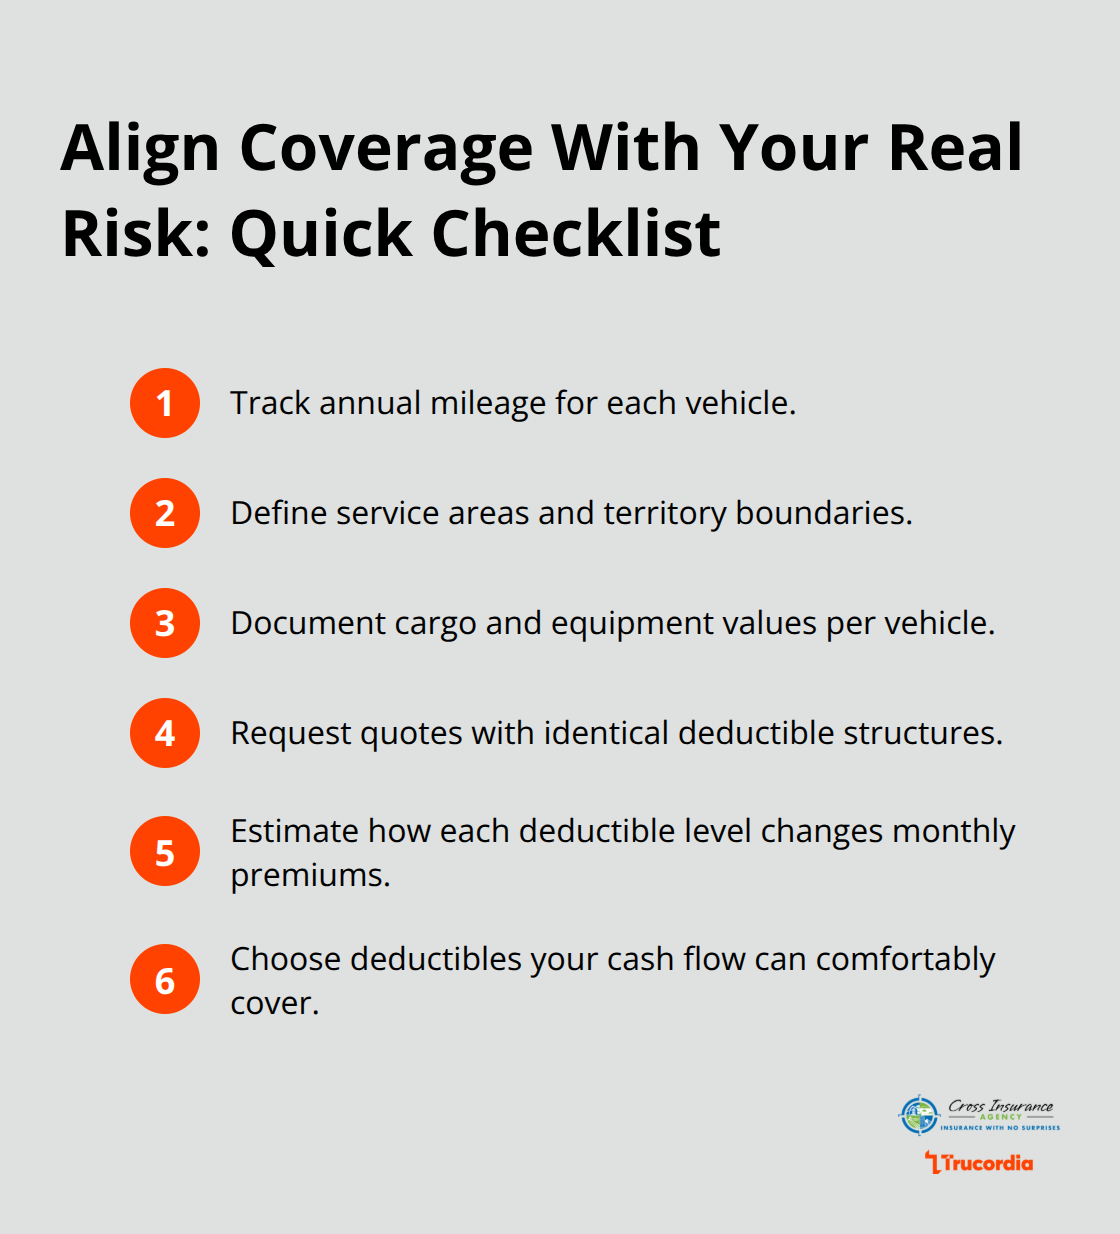
Start with your fleet’s annual mileage, typical service areas, and the dollar value of cargo or equipment your vehicles carry. This data becomes your negotiating foundation when comparing policies. Request quotes with identical deductible structures so you can see how different carriers price your specific operation. Deductibles directly affect your monthly premium-a $1,000 deductible costs significantly less than a $500 deductible-but the wrong deductible level creates financial pain when accidents happen.

Select deductibles your business can actually cover from operating cash flow without disrupting payroll or operations. If a single accident with a $2,500 deductible would strain your finances, that deductible is too high regardless of the premium savings.

Compact checklist of steps to document fleet operations and choose deductibles that fit cash flow. - fleet insurance Olympia WA

Bundling Creates Genuine Savings Beyond Fleet Coverage

Washington businesses operating multiple vehicles almost always carry general liability, commercial property, or workers compensation insurance. Bundling your fleet policy with these other coverages typically generates 10-20% discounts on your total commercial insurance spend, according to data from the National Association of Insurance Commissioners. The savings compound annually-a business saving $3,000 per year through bundling reinvests that money into operations, equipment, or hiring rather than paying unnecessary premiums.

When requesting quotes, ask carriers for their bundling discounts in writing and specify exactly which policies qualify. Some carriers advertise bundling discounts that apply only to specific coverage combinations, so you need transparency about what actually qualifies.

Local Expertise Prevents Coverage Gaps in Washington Operations

Washington’s regulatory environment differs from other states in ways that directly impact fleet insurance requirements and claims handling. An agent familiar with Washington Department of Labor regulations understands how commercial vehicle classification affects your rates and coverage options. Agents working in Olympia specifically understand local claim patterns-weather-related damage spikes during winter months, accident frequencies vary by neighborhood and highway corridor, and local repair shops have different pricing than regional chains.

This local knowledge translates into better policy recommendations and faster claims resolution when incidents occur. A carrier’s national claims adjuster might dispute a weather damage claim by applying standards from Arizona or Texas; a local agent advocates for your business using Washington-specific precedent. An independent agent who shops multiple top-rated carriers allows you to compare how different insurers handle your specific risk profile rather than accepting a single recommendation.

Final Thoughts

Consolidating your fleet under one policy eliminates the administrative chaos of managing multiple vehicles separately. You gain consistent liability protection across your entire operation, faster claims resolution when accidents happen, and genuine cost savings that compound year after year. Businesses in Olympia, WA that switch to fleet insurance Olympia WA plans typically recover their savings within the first renewal cycle through volume discounts and eliminated redundant fees.

Pull together your annual mileage data, service areas, and equipment values, then request quotes with identical deductible structures so you can compare apples to apples. This documentation becomes your foundation for negotiating better rates and identifying coverage gaps that individual policies might have left exposed. Select deductible amounts your business can actually cover without disrupting operations rather than chasing the lowest premium.

Washington’s regulatory environment and local claim patterns create advantages for businesses working with agents who understand Olympia specifically. A local agent recognizes how winter weather affects damage claims, understands Washington Department of Labor requirements that impact your rates, and advocates for your business using state-specific precedent when disputes arise. Cross Insurance Agency connects Olympia businesses with tailored commercial coverage by shopping multiple top-rated carriers and identifying bundling opportunities that reduce your total insurance spend.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Running rental properties in Washington means managing more than just tenants and maintenance. Commercial landlord insurance in WA protects your building, your income, and your finances when things go wrong.

At Cross Insurance Agency, we’ve helped countless property managers understand what coverage they actually need. This guide walks you through the essentials so you can make informed decisions about your property.

What Commercial Landlord Insurance Actually Covers

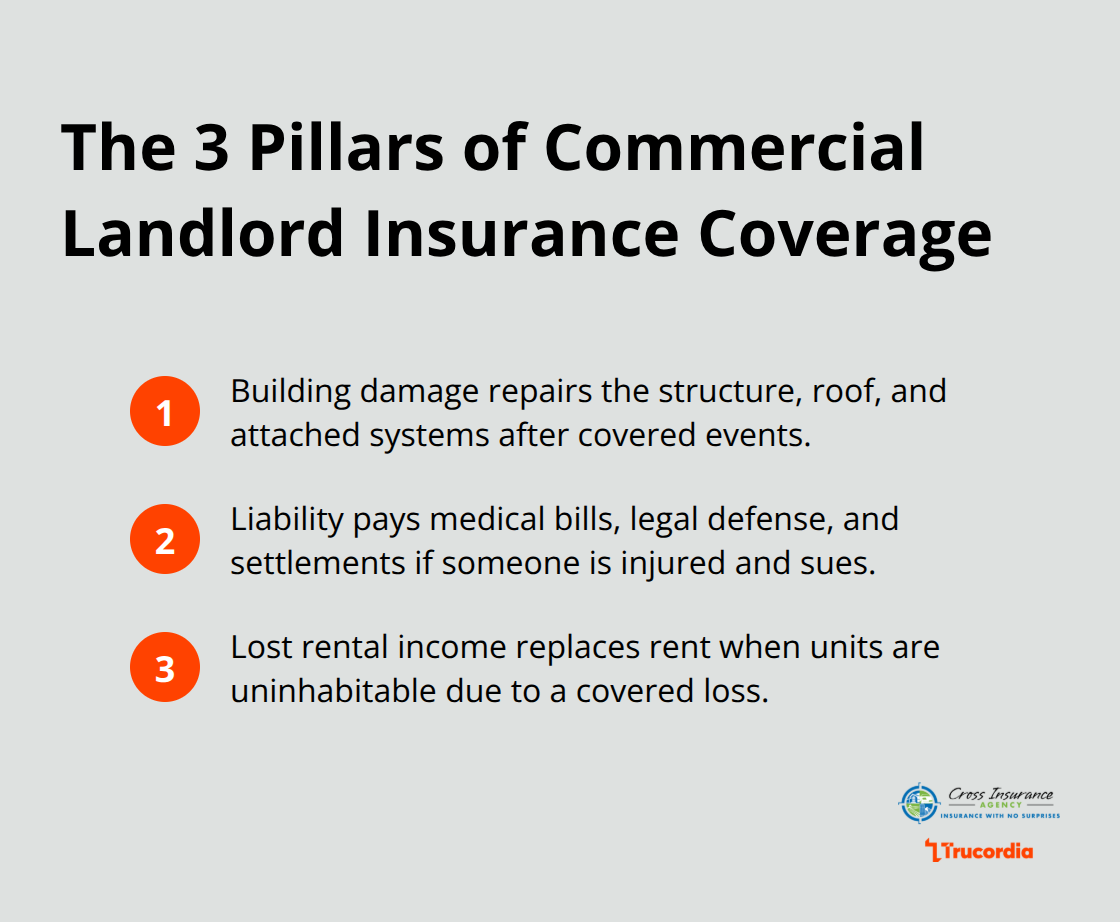
Commercial landlord insurance in Washington covers three critical areas that protect your rental property investment. First, it covers physical damage to your building structure, roof, and attached systems like HVAC and plumbing when fires, windstorms, or hail strike.

Three key protections of commercial landlord insurance: building damage, liability, and lost rental income.

Second, it protects you financially when someone gets injured on your property and sues-liability coverage pays their medical bills and legal costs up to your policy limit. Third, it replaces lost rental income if your building becomes uninhabitable due to a covered event, keeping your cash flow stable during repairs. Washington property managers often overlook how these three components work together to create a complete safety net.

Building Damage Protection Works Differently Than You Think

Property damage coverage pays to rebuild or repair your structure after covered events, but what actually counts as covered varies significantly between policies. Standard commercial policies cover fire, theft, windstorms, hail, and explosions, but they exclude floods and earthquakes-two major concerns in Washington. The Washington State Department of Commerce reports that flooding causes substantial property damage across the state each year, which means you need separate flood insurance if your property sits in a flood zone. Earthquake coverage requires an additional endorsement to your base policy. Many property managers mistakenly assume their landlord policy covers everything, then face denial when claiming water damage from a basement flood. Your agent can review your property’s flood risk and earthquake exposure before you finalize coverage limits.

Liability Protection Covers More Than You Realize

Liability coverage activates when a tenant, visitor, or delivery person injures themselves on your property and holds you legally responsible. A slip-and-fall claim can easily exceed $50,000 in medical expenses plus legal fees, and Washington courts have awarded substantial judgments in premises liability cases. Your policy typically covers medical payments, legal defense costs, and settlement amounts up to your chosen limit-often $300,000 to $1,000,000 for multi-unit properties. The coverage applies to injuries from negligent maintenance, inadequate lighting, broken stairs, or unsafe conditions you should have fixed. However, liability does not cover injuries your tenant causes to others on the property or injuries from intentional acts. Understanding these boundaries prevents costly claim denials when incidents occur.

Lost Rental Income Keeps Your Business Stable

When a covered event damages your building and forces tenants to vacate, lost rental income coverage pays you the rent you would have collected during repairs. This coverage period typically extends 12 months from the loss date, though you can adjust limits based on your expected rebuild timeline. If your property generates $5,000 monthly in rent and repairs take four months, this endorsement replaces $20,000 in lost income. Washington property managers with mortgage obligations especially need this protection since lenders still expect payments even when your building sits empty. Some policies also cover additional living expenses if you must temporarily relocate tenants, though coverage limits and terms vary by carrier.

Why Washington Property Managers Face Unique Risks

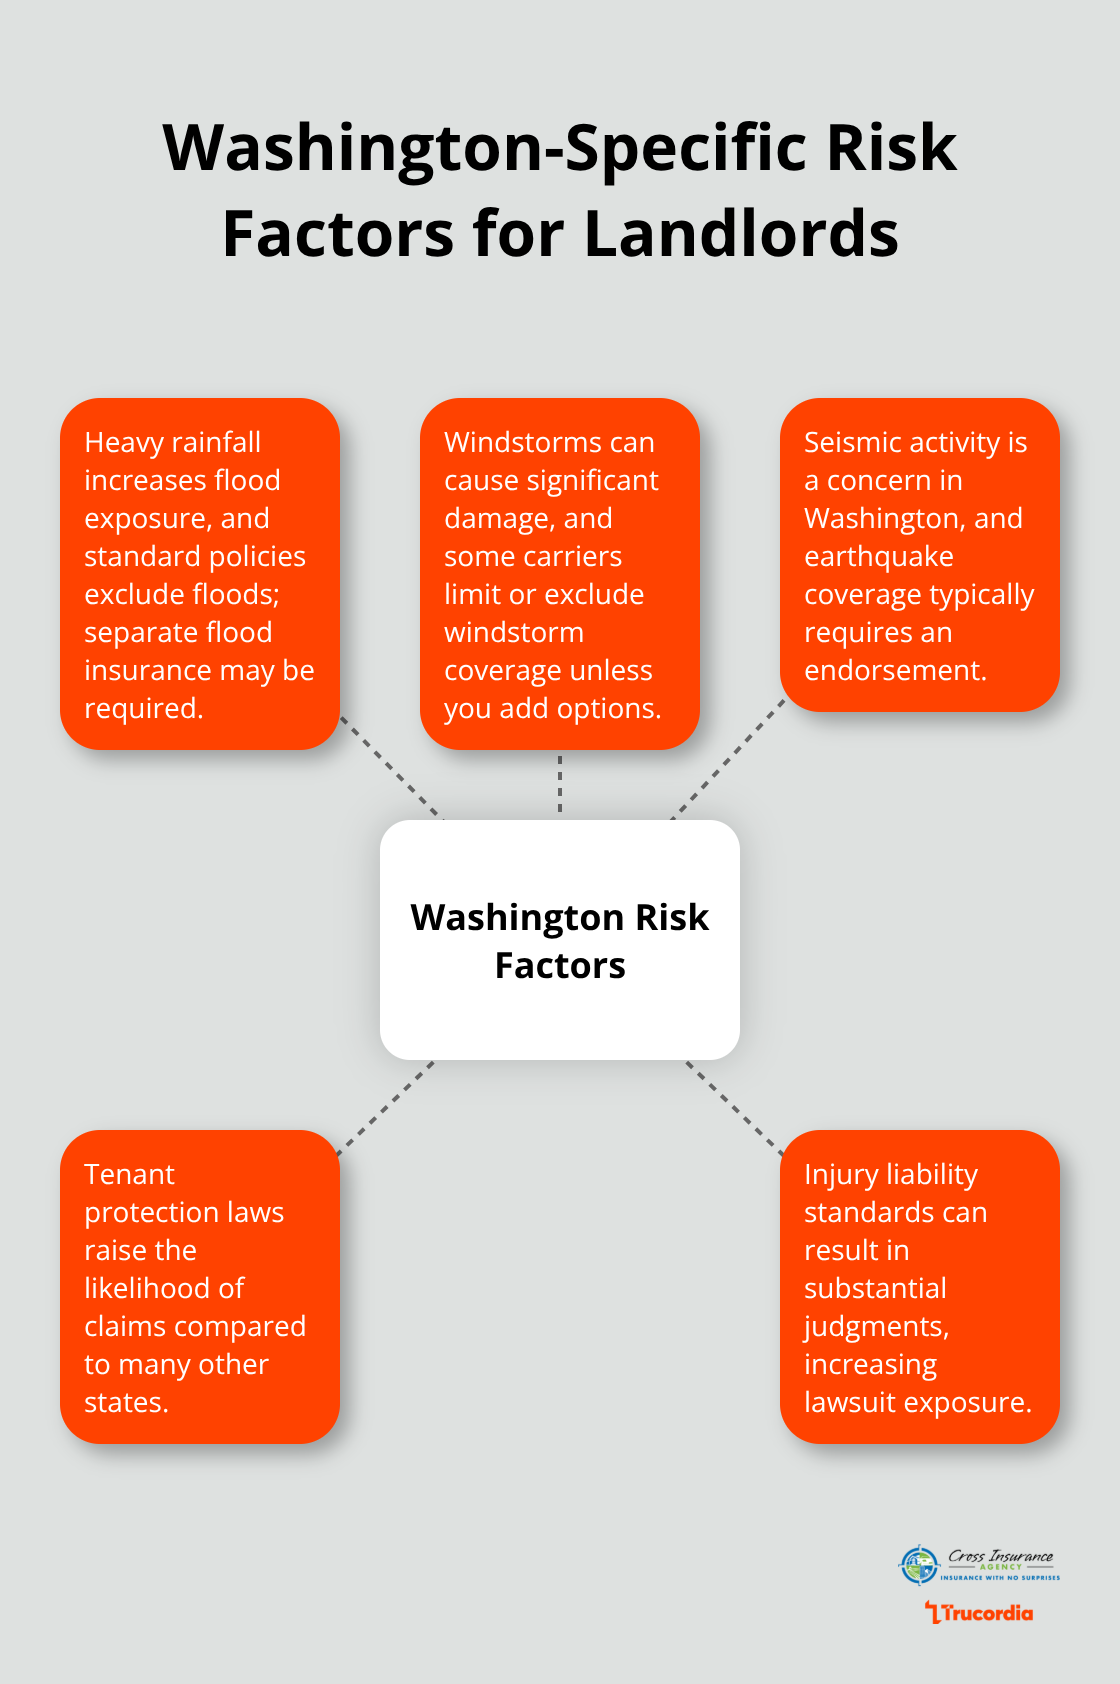
Washington’s climate and legal environment create specific insurance challenges that generic policies often miss. Heavy rainfall, windstorms, and seismic activity expose properties to damage that standard coverage excludes or limits. Additionally, Washington’s tenant protection laws and injury liability standards mean your exposure to claims runs higher than in many other states.

Hub-and-spoke diagram showing Washington landlord risk factors including rainfall, windstorms, seismic activity, and legal environment. - commercial landlord insurance WA

Property managers who understand these regional risks can select policies that actually match their exposure rather than discovering gaps when they file a claim.

Why Washington Property Managers Must Have Landlord Insurance

Mortgage Lenders Require Coverage Before You Close

Mortgage lenders in Washington mandate commercial landlord insurance before closing on any investment property, and this requirement exists for a reason. Your lender protects its financial stake by requiring you to carry coverage that rebuilds the building if disaster strikes, which means you cannot simply choose to go uninsured. Washington state law does not explicitly mandate landlord insurance for residential rental properties, but your mortgage contract does, making it a practical requirement for nearly every property manager with financing. Skipping this coverage exposes you to personal liability if someone sues after an injury on your property, and without insurance, they can pursue your personal assets, bank accounts, and future wages through a judgment.

Tenant-Related Claims Threaten Your Personal Finances

Washington courts have awarded substantial damages in premises liability cases, and a single major claim can wipe out years of rental income. Tenant-related claims represent your most frequent exposure since people spend most of their time inside your rental units, and accidents happen regardless of how well you maintain the property. A tenant’s guest slips on a wet floor, or a child falls from a balcony, and suddenly you face a lawsuit seeking hundreds of thousands of dollars. Your landlord policy covers these claims up to your policy limit, which means your personal finances stay protected.

Washington’s Climate Creates Constant Property Damage Risk

Washington experiences heavy rainfall, windstorms reaching 40+ mph in coastal and valley regions, and occasional seismic activity that damage properties regularly. Standard homeowners policies exclude commercial rental properties entirely, so you cannot insure your investment property under a personal policy. Without commercial landlord insurance, you absorb the full cost of repairs, lost rent during reconstruction, and legal defense fees if someone sues.

Your Policy Must Match Your Specific Property Risks

Your actual property location, tenant profile, and financial situation should shape your coverage rather than a generic template that leaves dangerous gaps. Properties in low-lying areas face flood exposure, while those near fault lines require earthquake protection. An independent insurance agent can assess your specific risks and recommend appropriate coverage limits and endorsements that address what your property actually faces.

How to Choose the Right Landlord Insurance Policy

Calculate Your Building’s True Replacement Cost

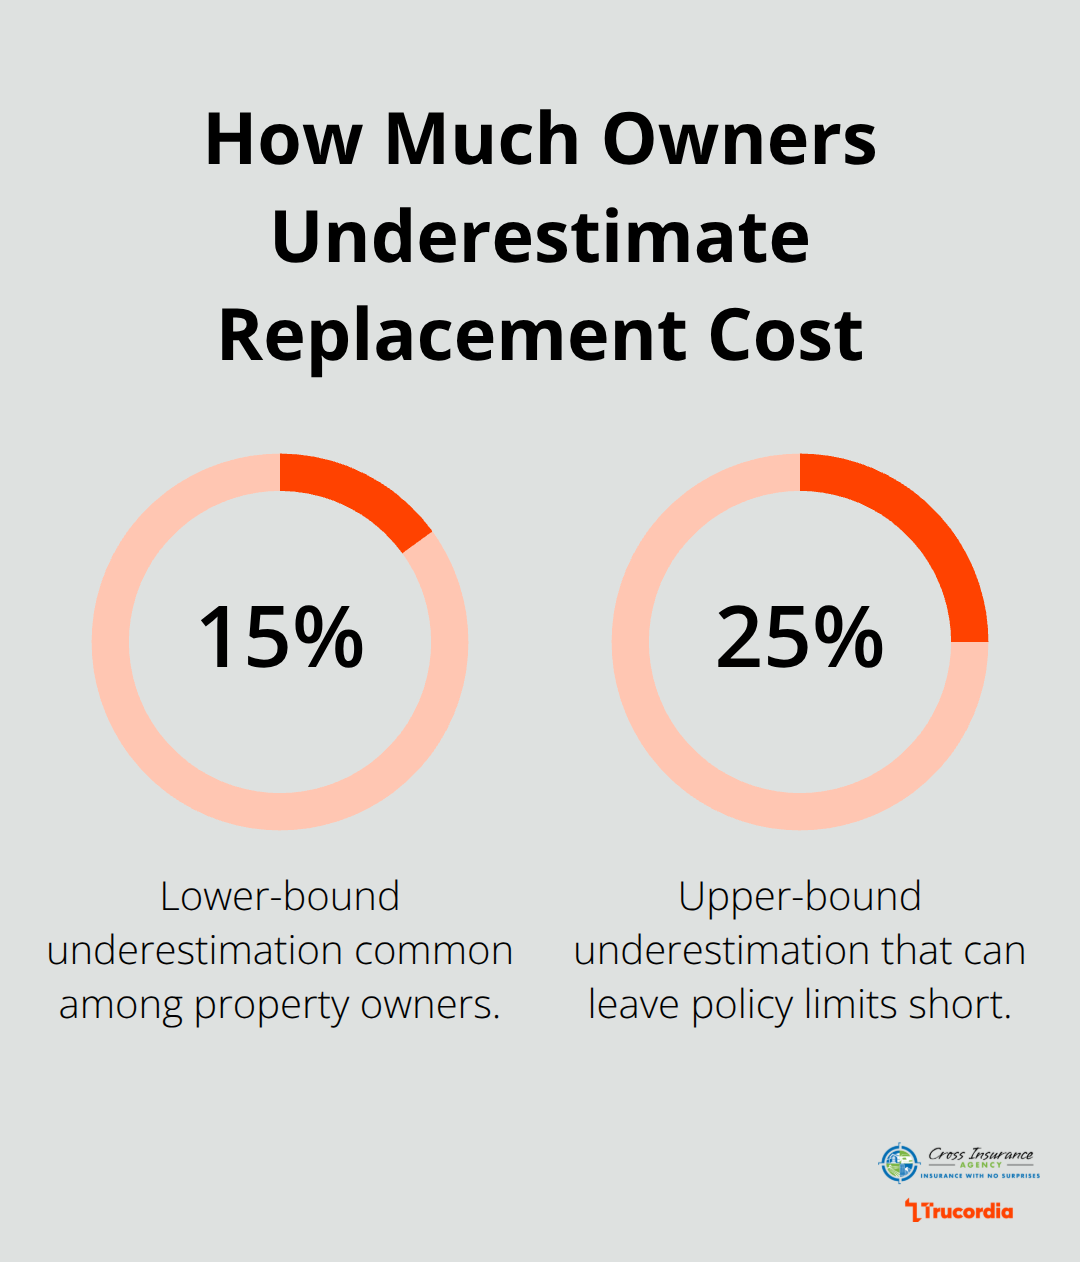
Selecting the right landlord insurance policy requires matching your coverage to what your property actually generates and what it would cost to rebuild. Start by calculating your building’s replacement cost, not its current market value-replacement cost is what it would genuinely cost to rebuild from the ground up today, including labor and materials in Washington’s current market. The National Association of Insurance Commissioners reports that most property owners underestimate replacement costs by 15 to 25 percent, which means your policy limit falls short when you file a claim. A professional property appraisal or contractor estimate provides far more accuracy than guessing based on what you paid years ago.

Bar chart showing common underestimation of replacement cost by property owners: 15% to 25%. - commercial landlord insurance WA

Account for Personal Property and Lost Income

Next, add your personal property coverage needs-if you own appliances, furniture, or equipment inside rental units, those items need separate coverage limits since standard policies exclude tenant belongings. Calculate your monthly rental income and multiply by the number of months your property would realistically sit vacant during repairs; this becomes your loss-of-income coverage limit. A four-unit building generating $8,000 monthly needs at least $32,000 in loss-of-income coverage if repairs typically take four months, though six-month coverage provides better protection given Washington’s unpredictable weather delays construction schedules.

Compare Carriers on Coverage, Not Just Price

Comparing carriers requires looking beyond premium price because the cheapest policy often excludes coverage you desperately need or sets limits so low they leave you exposed. Request quotes from at least three carriers and ask specifically what each policy excludes regarding water damage, earthquakes, and windstorm damage-these three categories account for most property damage claims in Washington. Some carriers cap windstorm coverage at 90 percent of replacement cost, while others exclude it entirely unless you pay extra, which dramatically changes your actual protection.

Set Liability Limits Based on Your Property Size

When comparing liability limits, most property managers carrying two to four units should carry at least $500,000 in coverage, while larger buildings justify $1,000,000 or more given Washington’s litigation environment. Your liability exposure grows with each additional unit and tenant, so your coverage should scale accordingly.

Bundle Policies to Save Money and Simplify Management

Bundling your commercial landlord policy with other business insurance-general liability, umbrella coverage, or commercial auto-typically saves 10 to 20 percent on premiums while consolidating your policies under one agent who understands your entire operation. This approach also simplifies renewals and claims since one agent handles coordination across all your policies rather than managing separate carriers with conflicting renewal dates.

Final Thoughts

Commercial landlord insurance in Washington protects your building structure against fire and weather damage, your finances when someone gets injured on your property, and your rental income during repairs. Without these three components working together, a single incident can drain your savings and force you to cover mortgage payments on an uninhabitable building. Most property managers discover coverage gaps only after filing a claim, which is far too late to add protection.

Start by calculating your building’s replacement cost, not its market value, since you need enough coverage to actually rebuild. Add your monthly rental income multiplied by your expected repair timeline, then request quotes from multiple carriers asking specifically about water damage, earthquake, and windstorm exclusions. Bundling your commercial landlord insurance WA with other business coverage typically saves 10 to 20 percent while consolidating your policies under one agent who understands your complete operation.

A local agent understands Washington’s specific risks and matches your coverage to your actual property exposure rather than selling you a generic template. Contact Cross Insurance Agency to discuss your commercial landlord insurance needs and protect your investment properly.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
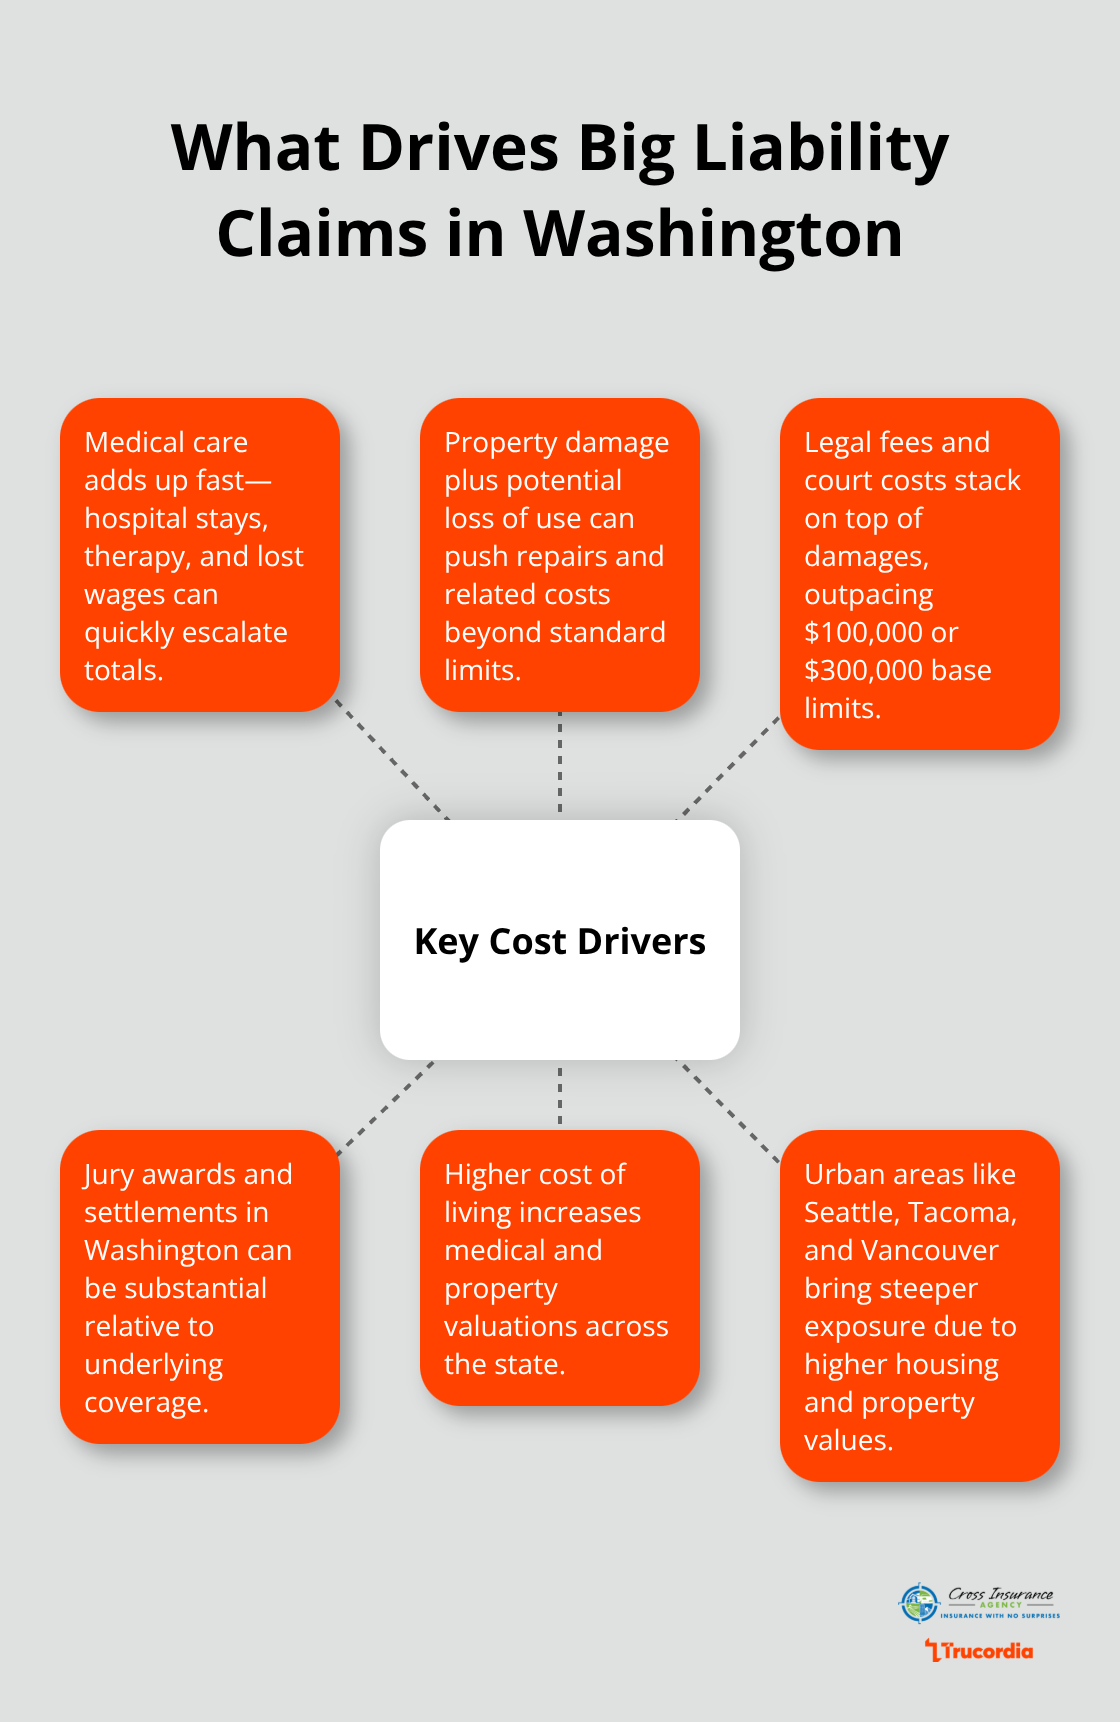
Auto insurance in Olympia doesn’t have to drain your budget. We at Cross Insurance Agency know that finding cheap auto insurance in Olympia means knowing where to look and what questions to ask.

The right strategy combines comparison shopping, smart discounts, and understanding what actually drives your rates. This guide walks you through proven methods to lower your premiums without sacrificing coverage.

How to Compare Auto Insurance Quotes the Right Way

Getting quotes from multiple insurers is the fastest way to cut your Olympia auto insurance bill, but most people stop too early in the process. Customers often grab the first three quotes they find and call it done, leaving hundreds of dollars on the table each year. The real work happens when you examine what each quote actually covers and why the prices differ so dramatically. Insurance companies price policies differently based on how they weigh risk factors, so a quote that looks cheap from one carrier might exclude coverage you need or apply stricter underwriting standards that affect future claims.

You need at least three quotes to spot real savings, but more importantly, you need to understand what makes each one different. Start with online quote tools from major carriers like State Farm, Geico, and Progressive to gather baseline numbers quickly, then add quotes from regional carriers that often compete aggressively on price in Washington state. This process takes roughly 20 to 30 minutes total, and the time investment pays off immediately when you see price variations of $400 to $800 annually for identical drivers and vehicles.

Coverage levels determine your actual protection

Once you have your quotes lined up, stop comparing just the premium amounts. The real comparison happens when you compare auto insurance quotes at identical coverage levels. A deductible may apply when you use collision coverage or comprehensive coverage, which will reimburse you for loss due to theft or damage caused. A quote that’s $50 cheaper per month often comes with a $1,500 deductible instead of $500, which means you’ll pay more out-of-pocket when you actually need to file a claim.

Washington state requires minimum liability coverage of 25/50/25 (meaning $25,000 bodily injury per person, $50,000 total per accident, and $25,000 property damage), but that bare minimum leaves you exposed if you cause serious injuries. Most Olympia drivers should carry at least 100/300/100 coverage, and comparing quotes at the same coverage level reveals which insurers actually offer the best rates for protection you’ll use.

Add-ons and bundled features shift the real cost

Look at whether quotes include roadside assistance, rental car coverage, and uninsured motorist protection, since some carriers bundle these at no extra cost while others charge $10 to $20 monthly for each add-on. The cheapest quote means nothing if it forces you to add $30 in optional coverages to match what competitors include in their base packages. This is where independent agents who shop multiple carriers become valuable-they identify which insurers bundle features that match your actual needs without padding your bill.

Key add-ons to verify in Olympia auto insurance quotes

Where Hidden Discounts Add Up Fast

Stack Multiple Policies for Maximum Savings

Bundling policies remains the single most effective way to slash your Olympia auto insurance costs, yet most drivers leave this money on the table. Insurance companies offer bundle discounts when you combine auto, homeowners, or renters coverage with the same carrier. A driver paying $1,200 annually for auto insurance alone could save $180 to $300 by adding homeowners coverage to the same policy.

Carriers reward customer loyalty across multiple products because it reduces their administrative costs and locks you in as a long-term client. When you shop for quotes, ask each insurer what their bundle discount percentages are, then calculate the total household premium rather than just the auto insurance line item. This single step often reveals that a carrier appearing expensive for auto alone becomes the cheapest option overall once bundling is factored in.

Target Discounts Based on Your Driving Habits

Low-mileage discounts apply if you drive fewer than 10,000 to 15,000 miles annually, and some carriers offer usage-based programs that track your actual driving patterns and reward safe behavior with discounts up to 30%. These programs work by monitoring acceleration, braking, and time of day you drive, then translating that data into real premium reductions. If you commute short distances or work from home several days weekly, this discount alone could cut 10% to 15% from your annual bill.

Percent savings available from usage-based and low-mileage programs for Olympia drivers - cheap auto insurance Olympia

Safety feature discounts reward you for having anti-theft devices, anti-lock brakes, or electronic stability control, typically saving 5% to 10% on your premium. Modern vehicles often come equipped with these features standard, so verify that your insurer recognizes them and applies the discount automatically. If your vehicle qualifies for multiple safety discounts, some carriers stack them while others cap the total benefit, so requesting a detailed breakdown prevents overpayment.

Loyalty Rewards and Stacking Strategies

Ask your current insurer about loyalty discounts after three to five years of continuous coverage, as many carriers offer 10% to 15% reductions for customers who stay put. These discounts accumulate quietly on your policy unless you specifically request them, which means thousands of Olympia drivers miss out simply because they never asked.

The critical difference between drivers who pay too much and those who get genuinely cheap insurance comes down to this: they actively ask about every discount their carrier offers and verify which discounts stack together. Some insurers cap stacking while others allow multiple discounts to combine, so requesting a detailed breakdown of available discounts before committing to any policy prevents surprise overpayment. Independent agents who shop multiple carriers identify which insurers bundle features that match your actual needs without padding your bill and ensure you capture every available discount.

Understanding what actually drives your rates matters just as much as finding discounts, since some factors you can control while others you cannot.

What Actually Drives Your Insurance Costs

Your Driving Record Sets Your Rate Foundation

Your driving record remains the single largest factor controlling your Olympia auto insurance rate, and the impact is severe enough that it should shape your driving decisions today. Insurance companies assign rates based on your claims history and violations over the past three to five years, with a single at-fault accident typically adding $400 to $600 annually to your premium, while a speeding ticket costs $150 to $300 per year depending on the violation severity. According to the Insurance Information Institute, drivers with one accident pay roughly 40% more than drivers with clean records, and multiple violations compound dramatically-a driver with two at-fault accidents and a speeding ticket could face premiums 75% higher than baseline rates.

Percentage increases in auto insurance premiums from accidents and violations - cheap auto insurance Olympia

The harsh reality is that your driving record impacts your insurance rate directly determines what you pay today, which means the cheapest insurance strategy involves not getting tickets or causing accidents rather than hunting for discounts.

Vehicle Type and Age Impact Your Premium

Your vehicle choice matters almost equally, since insurance companies charge significantly more for sports cars, luxury vehicles, and models with expensive repair costs compared to sedans and economy vehicles. A 2024 Honda Accord costs roughly 30% less to insure than a 2024 Dodge Charger, and older vehicles often become cheaper to insure despite higher repair costs because replacement value decreases as the car ages. Comprehensive and collision coverage specifically ties directly to your vehicle’s market value, which means a five-year-old Toyota costs considerably less to insure comprehensively than a brand-new model. Age of your vehicle matters more than most drivers realize because insurance companies tie repair expenses to current replacement parts availability and labor costs.

Coverage Limits and Deductibles Give You Control

Coverage limits and deductible selection represent the only rate factors you control directly, and these choices determine what you actually pay versus what the insurance company pays when you file a claim. Raising your deductible from $500 to $1,000 typically cuts your collision and comprehensive premiums by 15% to 25% annually, yet this strategy only works if you maintain an emergency fund to cover the higher out-of-pocket cost when damage occurs. Calculate your actual emergency savings before raising deductibles, since saving $200 per year means nothing if an accident forces you into credit card debt because you cannot afford the $1,500 deductible.

Liability coverage limits operate differently-increasing from state minimum 25/50/25 to 100/300/100 costs only $10 to $20 more monthly but protects your assets far better if you cause serious injuries. A lawsuit following a severe accident can exceed $500,000 in damages, and state minimum coverage leaves you personally liable for everything above that threshold, making higher liability limits genuinely inexpensive protection rather than optional extras. Your coverage decisions should reflect your actual situation rather than generic advice, which means comparing total out-of-pocket risk against premium savings before finalizing any deductible or coverage limit changes.

Final Thoughts

Finding cheap auto insurance in Olympia requires three concrete actions: comparing quotes at identical coverage levels across multiple carriers, stacking every discount your situation qualifies for, and understanding which rate factors you can actually control. The drivers who pay the least aren’t necessarily the safest or wealthiest-they’re simply the ones who took time to shop properly and asked their insurers direct questions about bundling, loyalty rewards, and safety feature discounts. Your driving record and vehicle choice set your baseline rate, but your deductible and coverage limit decisions determine whether you’re actually protected or just paying for a policy number.

Gather quotes from at least three different carriers this week, then compare them side-by-side at the same coverage levels rather than just looking at the cheapest monthly premium. Request specific discount percentages from each insurer, calculate your total household cost if you bundle multiple policies, and verify which discounts stack together before committing to any carrier. This process takes roughly 30 minutes and typically saves $300 to $600 annually compared to renewing your current policy without shopping.

We at Cross Insurance Agency work with multiple top-rated carriers on your behalf, which eliminates the legwork while helping you capture discounts you might miss on your own. Our licensed agents understand Washington’s specific insurance requirements and local market rates, so we identify which carriers offer the best combination of price and coverage for your actual situation. Contact Cross Insurance Agency to get personalized quotes tailored to your Olympia location and driving profile-we handle the comparison shopping so you get genuine savings without the hassle.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
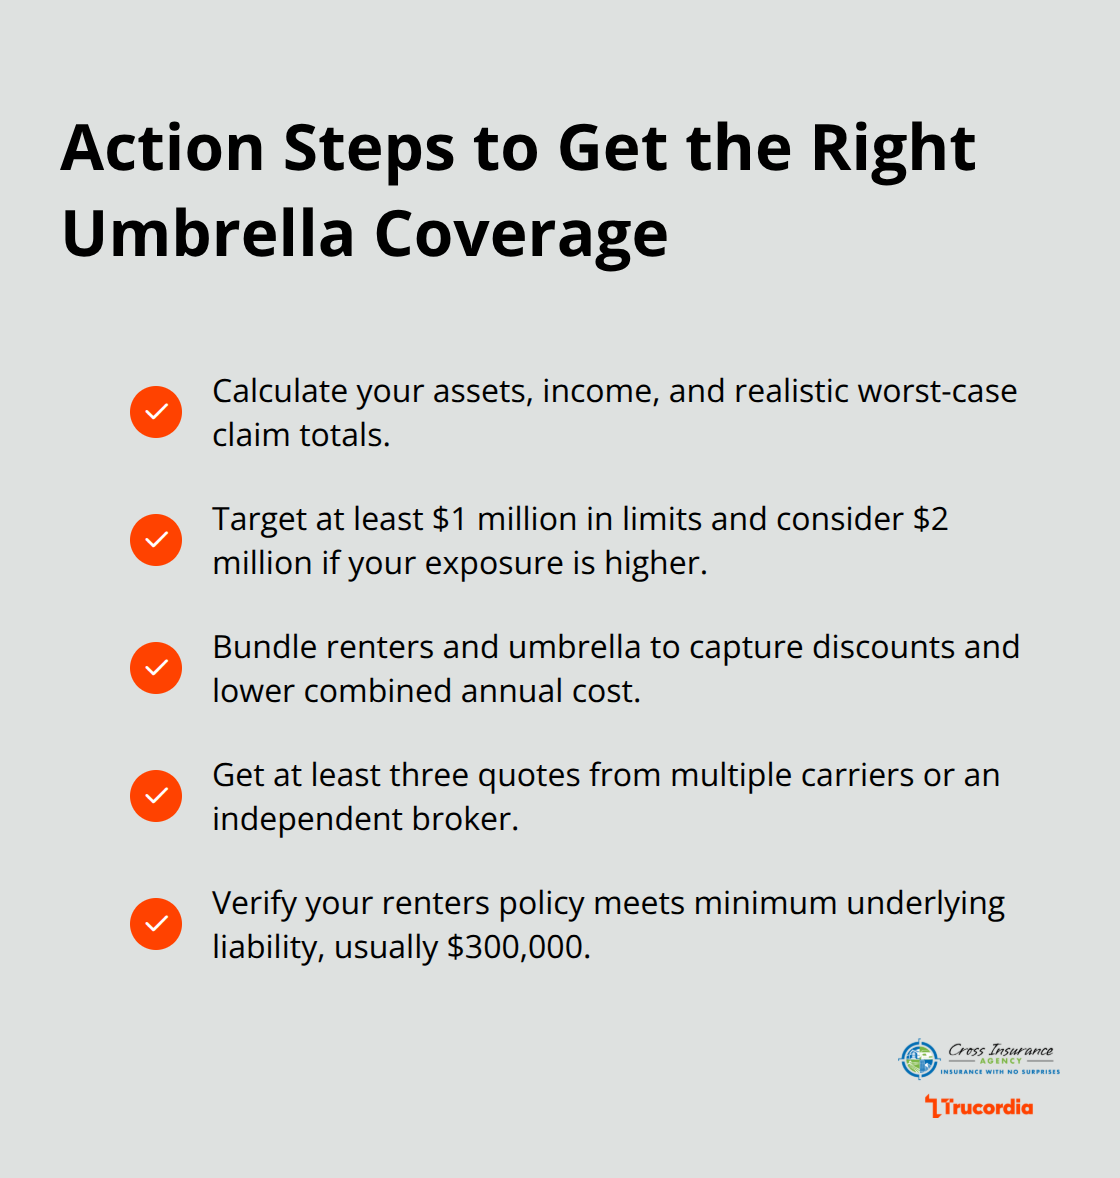
Renting a car in Olympia means you need protection that goes beyond hoping nothing goes wrong. Most people don’t realize their personal auto insurance might not cover rental vehicles, leaving them exposed to thousands of dollars in potential liability and damage costs.

At Cross Insurance Agency, we help Olympia residents understand their rental car insurance options so they can travel with confidence. This guide walks you through the coverage types available, how to assess what you already have, and how to choose the right protection for your next rental.

What Rental Car Insurance Actually Covers

Three Main Protection Categories

Rental car insurance protects you against financial losses when you damage, lose, or face liability for injuries in a rental vehicle. The coverage breaks down into three main categories: collision damage waiver (CDW) covers most of the car if you’re in a collision but usually excludes the undercarriage, roof, tires, windshield, windows, interior, and side mirrors, liability coverage covers injuries or property damage you cause to others, and personal effects coverage reimburses stolen items from the vehicle. Most people assume their personal auto policy automatically extends to rentals, but this assumption costs renters thousands annually.

The Coverage Gap Most Renters Face

According to the National Association of Insurance Commissioners, roughly 40 percent of renters lack adequate coverage when they pick up a vehicle. Your personal auto policy may not cover rentals at all, or it might only cover liability while excluding collision and comprehensive damage. Credit card rental protections sound appealing until you read the fine print-many cards exclude luxury vehicles, impose strict claim procedures, and require you to decline the rental company’s coverage first (which can trigger disputes with the rental agency).

Share of renters lacking adequate coverage (NAIC)

What Actually Happens When Damage Occurs

The real protection question comes down to what happens when something goes wrong. If you cause an accident in a rental and the damage exceeds your policy limits, you become personally liable for the difference. A single accident involving a mid-size sedan can easily cost $8,000 to $15,000 in repairs, plus potential liability claims if other vehicles or property were involved.

Washington’s Minimum Requirements Fall Short

Washington state requires all drivers to carry minimum liability coverage of 25/50/25, meaning $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage. When you rent, those minimums often prove insufficient for actual damages. Scenarios like hitting a parked car in a parking lot, experiencing a breakdown that extends rental duration, or having the vehicle damaged while parked overnight are exactly where rental insurance fills gaps your personal policy leaves open.

Evaluating Your Actual Protection

Identifying which rental protection option makes financial sense requires honest assessment of your existing coverage. Your personal auto policy details, credit card benefits, and the rental company’s offerings each play a role in your final decision. Understanding these three options helps you avoid overpaying for redundant coverage or leaving yourself exposed to significant financial risk.

Hub-and-spoke showing personal auto policy, rental company waiver, and credit card coverage - rental car insurance Olympia

Your Three Coverage Options in Olympia

What Your Personal Auto Policy Actually Covers

Your personal auto policy might extend to rentals, but most standard policies exclude them entirely or cover only liability while leaving you exposed to collision and comprehensive damage. The only way to know is to call your insurance agent and ask specifically whether your policy covers rental vehicles, what limits apply, and what exclusions exist. Many Olympia drivers discover gaps only after damage occurs, which is too late.

If your policy does cover rentals, check the deductible-it often runs higher for rentals than your personal vehicles, sometimes reaching $1,000 or more. Some policies also exclude coverage for certain rental types like luxury vehicles or trucks, so verify those details before you sign a rental agreement.

Rental Company Damage Waivers: What They Hide

Rental car companies push their own damage waivers aggressively at the counter, and for good reason-they generate significant revenue. The rental company’s collision damage waiver typically costs between $15 and $30 per day, which adds up quickly on a week-long trip.

What rental companies won’t emphasize is that these waivers often contain exclusions for off-road use, racing, mechanical breakdown, or damage from weather events. They also shift liability for the rental vehicle’s maintenance onto you, meaning if the brakes fail and you cause an accident, you could still face charges. The rental company’s liability coverage is usually minimal and protects them, not you.

Credit Card Rental Protection: The Hidden Costs

Credit card rental protection sounds free until you need it-most cards require you to decline the rental company’s coverage first, which creates immediate conflict with the rental agent. Many cards exclude luxury vehicles, exotic cars, or vehicles rented for business use. The claims process for credit cards is notoriously slow, sometimes taking 60 to 90 days, and requires extensive documentation.

These limitations mean credit card protection often fails when you need it most. A dedicated rental coverage policy eliminates these complications, provides clear coverage without exclusions hiding in fine print, and gives you immediate protection without disputes. When you compare your three options side by side, the choice becomes clear about which path protects you best.

Picking the Right Coverage for Your Rental

Ask Your Agent Three Specific Questions

Start by calling your insurance agent and asking three specific questions: Does my personal auto policy cover rental vehicles? If yes, what is the deductible for rentals, and what limits apply? What exclusions exist? Your agent should provide written answers, not vague reassurances. Once you have those answers, you can compare them against the rental company’s daily waiver cost and your credit card benefits.

Calculate the Math on Deductibles and Daily Costs

If your personal policy covers collision and comprehensive damage with a deductible under $500, you likely don’t need additional rental coverage unless you’re renting a luxury vehicle or traveling internationally. However, if your policy excludes rentals entirely or carries a $1,000 deductible, the rental company’s daily waiver becomes more attractive despite its cost. A $20 daily waiver over seven days costs $140, while a single accident with a $1,000 deductible could leave you paying thousands out of pocket. The decision isn’t about finding the cheapest option-it’s about identifying which scenario protects you without draining your wallet.

Quick comparison of daily costs, deductibles, repair bills, and authorization holds - rental car insurance Olympia

Credit Card Coverage Creates Conflicts at the Rental Counter

Washington drivers often overlook one critical detail: your credit card’s rental protection typically requires you to decline the rental company’s coverage, which puts you in direct conflict with the rental agent at the counter. The agent will pressure you to purchase their waiver, and if you refuse, they may require a credit card authorization hold for $15,000 to $50,000 depending on the vehicle class. That hold can cause problems if your card has a low limit or if you’re planning to use that card for other expenses during your trip.

Credit Card Exclusions Eliminate Coverage When You Need It

Credit card coverage excludes business rentals, luxury vehicles over certain price points, and often requires you to submit claims within 90 days with receipts, police reports, and repair estimates. For Olympia residents who rent occasionally for personal travel, credit card coverage might work. For anyone renting multiple times annually or for business purposes, a standalone rental policy removes these complications entirely and costs far less than you’d expect-often between $3 and $8 per day through an independent agent who can shop rates across multiple carriers.

Final Thoughts

Rental car insurance in Olympia protects you from financial exposure that your personal auto policy might not cover. Call your insurance agent today and ask three specific questions: Does my policy cover rentals, what deductible applies, and what exclusions exist? That single conversation eliminates guesswork and prevents costly surprises when damage occurs.

We at Cross Insurance Agency work with Olympia residents to identify coverage gaps and find rental car insurance solutions that fit your travel patterns and budget. Our licensed agents shop multiple carriers to deliver options you won’t find by calling rental companies or relying on credit card benefits. Whether you rent occasionally for vacation or frequently for business, we connect you with coverage that actually protects you without redundant costs.

Contact Cross Insurance Agency before your next rental to review your existing coverage and explore independent carrier options. We’ll explain what rental car insurance in Olympia costs through carriers beyond the rental counter and help you make a decision based on facts rather than pressure. Protection starts with understanding your options, and that’s exactly what we provide.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
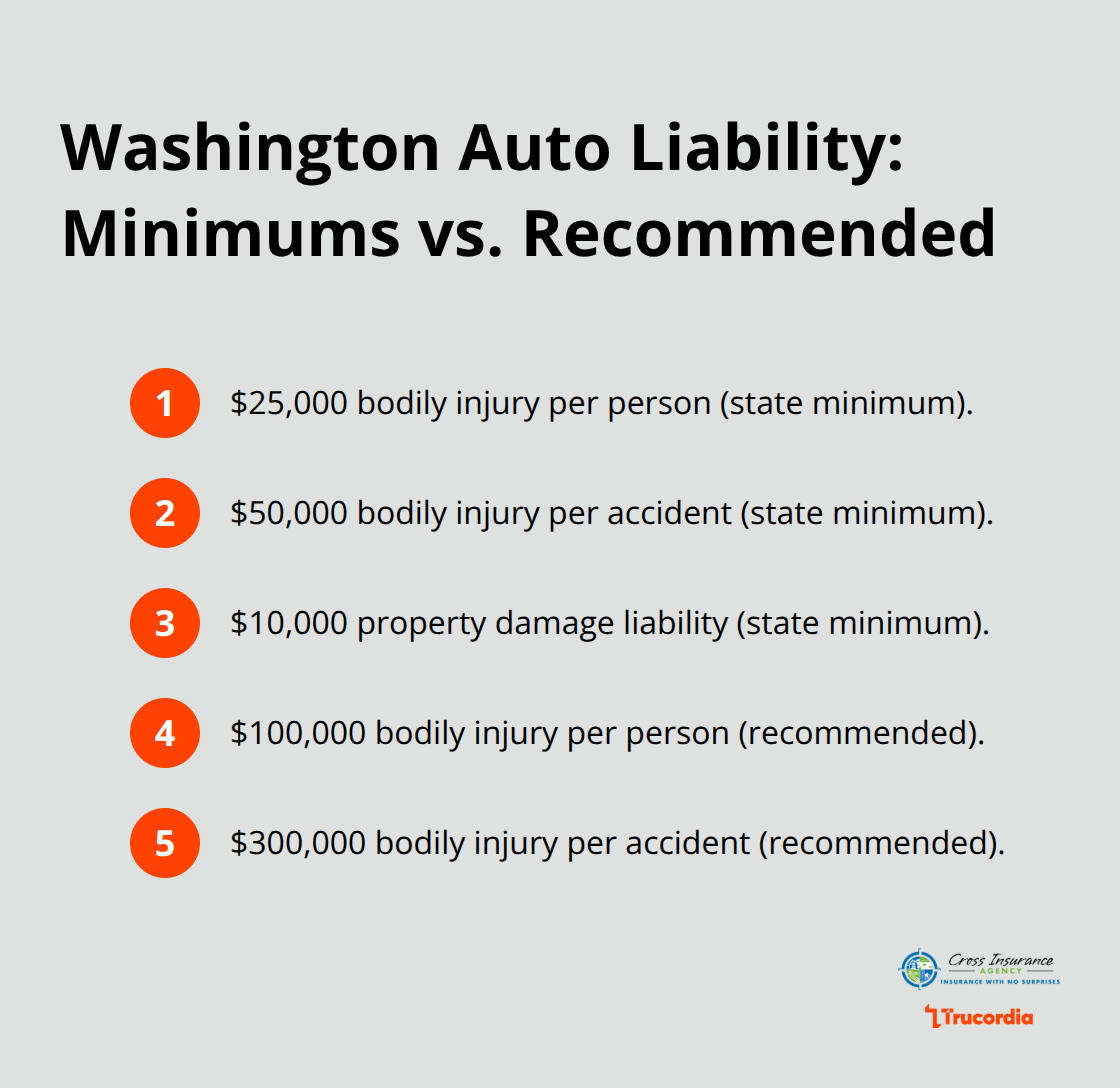
A single liability claim can wipe out years of rental income. Washington’s tenant-friendly laws and rising premises liability lawsuits make landlord liability insurance WA essential for protecting your business.

At Cross Insurance Agency, we’ve seen too many property owners operate without adequate coverage, only to face devastating financial consequences when accidents happen. The right policy shields your rental operation from bodily injury claims, property damage liability, and expensive legal fees.

What Landlord Liability Insurance Actually Covers

Bodily Injury Protection

Landlord liability insurance protects you when someone gets hurt on your rental property. When a tenant slips on icy stairs and breaks their leg, or a guest at a tenant’s party sues you for injuries, this coverage pays their medical bills, lost wages, and court judgments. Without this coverage, you’re personally liable for these expenses, which means creditors can pursue your personal assets, not just rental income.

Hub-and-spoke diagram showing core coverages in WA landlord liability insurance: bodily injury, legal defense costs, and property damage liability. - landlord liability insurance WA

Legal Defense Costs

The policy also covers legal defense costs, which can exceed $50,000 before a case even reaches trial. Even if you win the case, you’ve already paid thousands in attorney fees. This protection matters because the legal system doesn’t care whether you’re ultimately found liable-your defense costs mount regardless.

Property Damage Liability

Accidents happen beyond the tenant’s control, and property damage liability responds when they do. If you’re found liable for damaging a neighbor’s fence or their vehicle on your property, this coverage protects you. A guest injured on your property might sue, claiming your negligence allowed the hazard to exist-property damage liability addresses these situations.

Selecting the Right Coverage Limits

Standard policies typically offer $300,000 to $1,000,000 in liability limits, but your actual needs depend on your property type, location within Washington, tenant demographics, and local court award trends. A modest three-unit building and a 20-unit complex have vastly different exposure levels. Your specific property risks should guide your coverage limit selection, since underinsuring creates gaps that leave you vulnerable.

Why Washington’s Legal Climate Makes Liability Coverage Non-Negotiable

Washington’s Tenant Protection Laws Shift Risk to Landlords

Washington state’s tenant protection laws create significant liability exposure for landlords. The state has some of the strongest renter protections in the country, which means courts often side with tenants in injury disputes. Washington’s comparative negligence standard allows injured parties to recover damages even if they’re partially at fault, shifting more financial risk onto property owners.

A tenant injured on your property can argue you failed to maintain safe conditions, and Washington courts frequently award substantial damages in these cases. Additionally, Washington has no caps on non-economic damages like pain and suffering, meaning a single slip-and-fall claim can result in significant judgments. This legal environment makes liability coverage not optional-it’s a business requirement.

Three-point list explaining how Washington’s legal environment heightens liability exposure for landlords.

The Rising Cost of Premises Liability Claims

Premises liability lawsuits against rental property owners have increased steadily over the past decade. The Insurance Information Institute reports that the frequency of premises liability claims continues to rise nationally, and Washington’s tenant-friendly courts make the state particularly vulnerable to higher claim costs.

An uninsured judgment can force you into personal bankruptcy or require selling off properties to satisfy court orders. Legal defense costs alone can be substantial before you settle claims, with total payouts extending well beyond your annual rental income. Operating without adequate liability coverage means one accident could eliminate years of profit and jeopardize your entire rental portfolio.

The Hidden Costs of Going Uninsured

The financial devastation of an uninsured claim extends far beyond the immediate judgment. You’ll face difficulty obtaining future financing, higher insurance premiums once you finally get coverage, and potential loss of financing from existing lenders who discover gaps in your protection. Lenders view uninsured claims as red flags that signal poor risk management.

These cascading consequences can damage your ability to refinance properties, purchase additional rental units, or access favorable loan terms. The cost of operating without proper coverage compounds over time, making liability insurance an investment that protects not just your current properties but your future growth as a landlord. Understanding your specific property risks helps you select the right coverage limits that actually match your exposure.

How to Choose the Right Landlord Liability Policy for Your Rental

Assess Your Property’s Real Risk Factors

Start with an honest assessment of what could go wrong on your specific property. A four-unit apartment building with exterior stairs in Seattle faces different risks than a single-family home in a suburban area. Walk your property and document hazards: icy walkways in winter months, poor lighting near entrances, aging plumbing that could cause water damage to adjacent units, or common areas where guests frequently gather. Washington’s rainy climate creates slip-and-fall hazards that persist longer than in drier states, so properties with outdoor stairs or decks warrant higher coverage limits. Properties near busy streets or with pools, hot tubs, or trampolines attract more litigation. Once you identify your specific risks, you can justify coverage limits that actually protect you rather than guessing at industry averages.

Match Coverage Limits to Your Exposure

Coverage limits between $300,000 and $1,000,000 work for some properties, but a densely occupied building or one with documented accident history needs $1,000,000 or higher. Deductibles typically range from $500 to $2,500-a higher deductible lowers your premium but means you pay more out-of-pocket for smaller claims. If your property has experienced claims before, a lower deductible protects you from repeated out-of-pocket expenses that accumulate quickly.

Compare Quotes Across Multiple Carriers

Bundling landlord liability with other coverage types produces real savings that most property owners overlook. Adding landlord liability to a commercial property policy or combining it with umbrella coverage often costs 15-25% less than purchasing policies separately. An independent agent in Washington can shop multiple carriers and show you exactly which combinations save money for your specific situation. Carriers like State Farm, Allstate, and regional providers each price landlord liability differently based on your property details, claims history, and location within Washington. Getting three to five quotes takes roughly two hours but reveals price differences that can exceed $500 annually on the same coverage.

Compact ordered list of steps to cut landlord liability premiums in Washington. - landlord liability insurance WA

Review and Adjust Your Coverage Annually

Annual reviews catch coverage gaps when your property changes-adding a unit, converting to short-term rentals, or upgrading amenities all affect your liability exposure and should trigger policy adjustments. Your coverage needs shift as your rental operation evolves, and policies that protected you last year may leave gaps this year.

Final Thoughts

Your landlord liability insurance WA policy requires regular attention as your property and business evolve. When you add units, upgrade amenities, or shift to short-term rentals, your coverage must shift with those changes. Annual policy reviews catch gaps that develop over time and let you adjust coverage limits based on actual claim trends in your area and your property’s performance history.

Property maintenance directly reduces your liability exposure and strengthens your insurance position. Washington’s wet climate demands consistent attention to drainage, walkways, and exterior stairs where slip-and-fall accidents happen most frequently. Document your maintenance efforts with photos and records (this documentation proves you took reasonable steps to prevent injuries if a claim arises), because well-maintained properties experience fewer accidents and receive better renewal rates from insurers.

Working with local agents who understand Washington’s specific legal environment makes a real difference in your coverage decisions. An agent familiar with Washington’s tenant protection laws, comparative negligence standards, and local court award patterns can recommend appropriate coverage limits that actually match your exposure. Connect with us at Cross Insurance Agency to review your current coverage and confirm your policy reflects your actual business needs.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.