
Rental Car Insurance Olympia: Your Guide to Short-Term Vehicle Coverage
Renting a car in Olympia means you need protection that goes beyond hoping nothing goes wrong. Most people don’t realize their personal auto insurance might not cover rental vehicles, leaving them exposed to thousands of dollars in potential liability and damage costs.
At Cross Insurance Agency, we help Olympia residents understand their rental car insurance options so they can travel with confidence. This guide walks you through the coverage types available, how to assess what you already have, and how to choose the right protection for your next rental.
What Rental Car Insurance Actually Covers
Three Main Protection Categories
Rental car insurance protects you against financial losses when you damage, lose, or face liability for injuries in a rental vehicle. The coverage breaks down into three main categories: collision damage waiver (CDW) covers most of the car if you’re in a collision but usually excludes the undercarriage, roof, tires, windshield, windows, interior, and side mirrors, liability coverage covers injuries or property damage you cause to others, and personal effects coverage reimburses stolen items from the vehicle. Most people assume their personal auto policy automatically extends to rentals, but this assumption costs renters thousands annually.
The Coverage Gap Most Renters Face
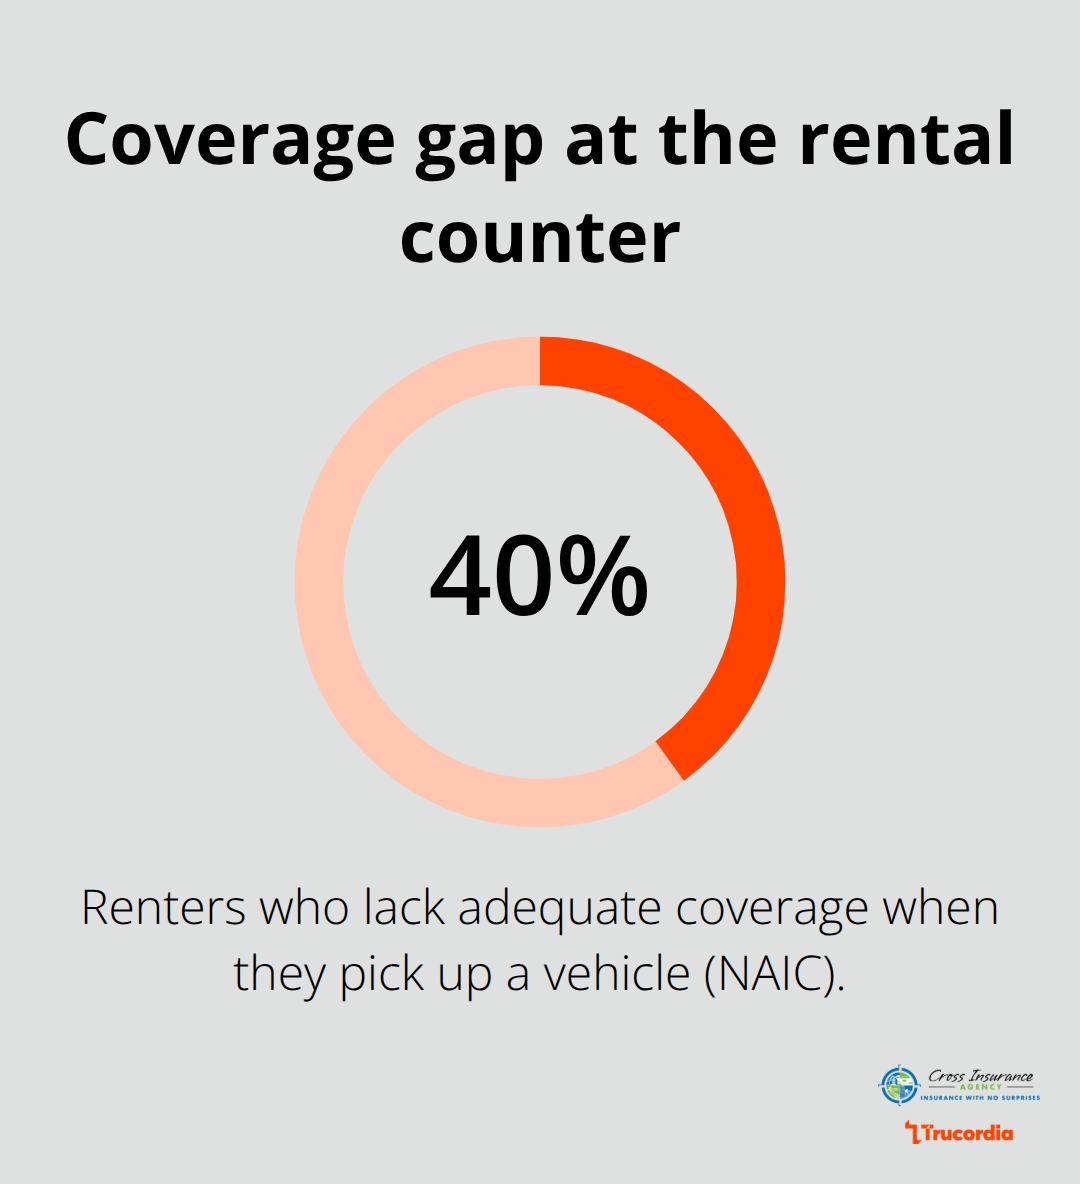
According to the National Association of Insurance Commissioners, roughly 40 percent of renters lack adequate coverage when they pick up a vehicle. Your personal auto policy may not cover rentals at all, or it might only cover liability while excluding collision and comprehensive damage. Credit card rental protections sound appealing until you read the fine print-many cards exclude luxury vehicles, impose strict claim procedures, and require you to decline the rental company’s coverage first (which can trigger disputes with the rental agency).
What Actually Happens When Damage Occurs
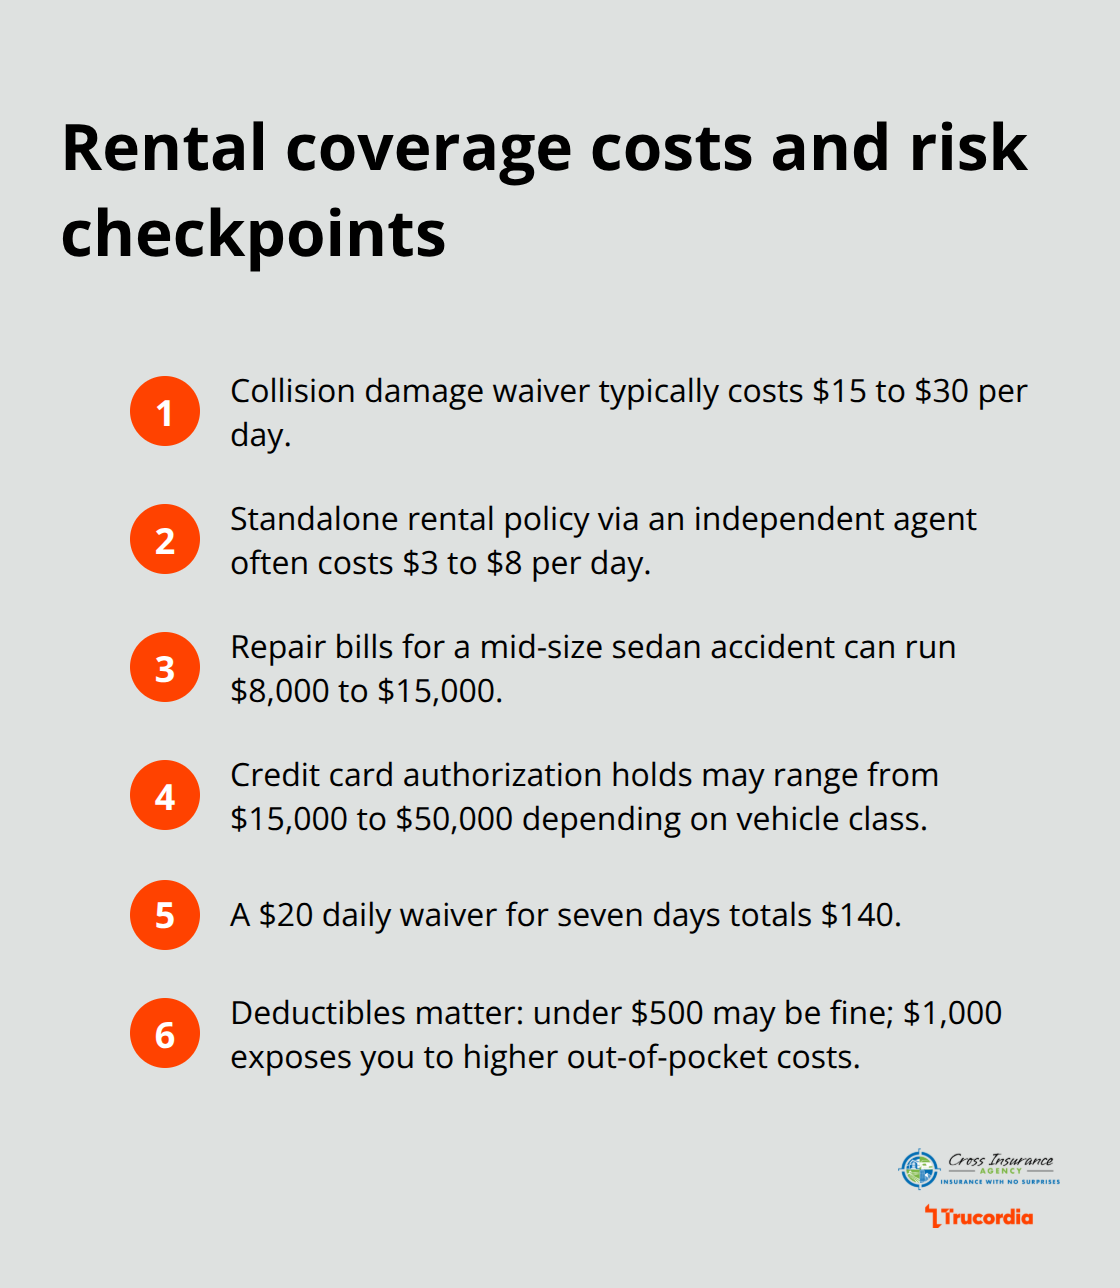
The real protection question comes down to what happens when something goes wrong. If you cause an accident in a rental and the damage exceeds your policy limits, you become personally liable for the difference. A single accident involving a mid-size sedan can easily cost $8,000 to $15,000 in repairs, plus potential liability claims if other vehicles or property were involved.
Washington’s Minimum Requirements Fall Short
Washington state requires all drivers to carry minimum liability coverage of 25/50/25, meaning $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage. When you rent, those minimums often prove insufficient for actual damages. Scenarios like hitting a parked car in a parking lot, experiencing a breakdown that extends rental duration, or having the vehicle damaged while parked overnight are exactly where rental insurance fills gaps your personal policy leaves open.
Evaluating Your Actual Protection
Identifying which rental protection option makes financial sense requires honest assessment of your existing coverage. Your personal auto policy details, credit card benefits, and the rental company’s offerings each play a role in your final decision. Understanding these three options helps you avoid overpaying for redundant coverage or leaving yourself exposed to significant financial risk.
Your Three Coverage Options in Olympia
What Your Personal Auto Policy Actually Covers
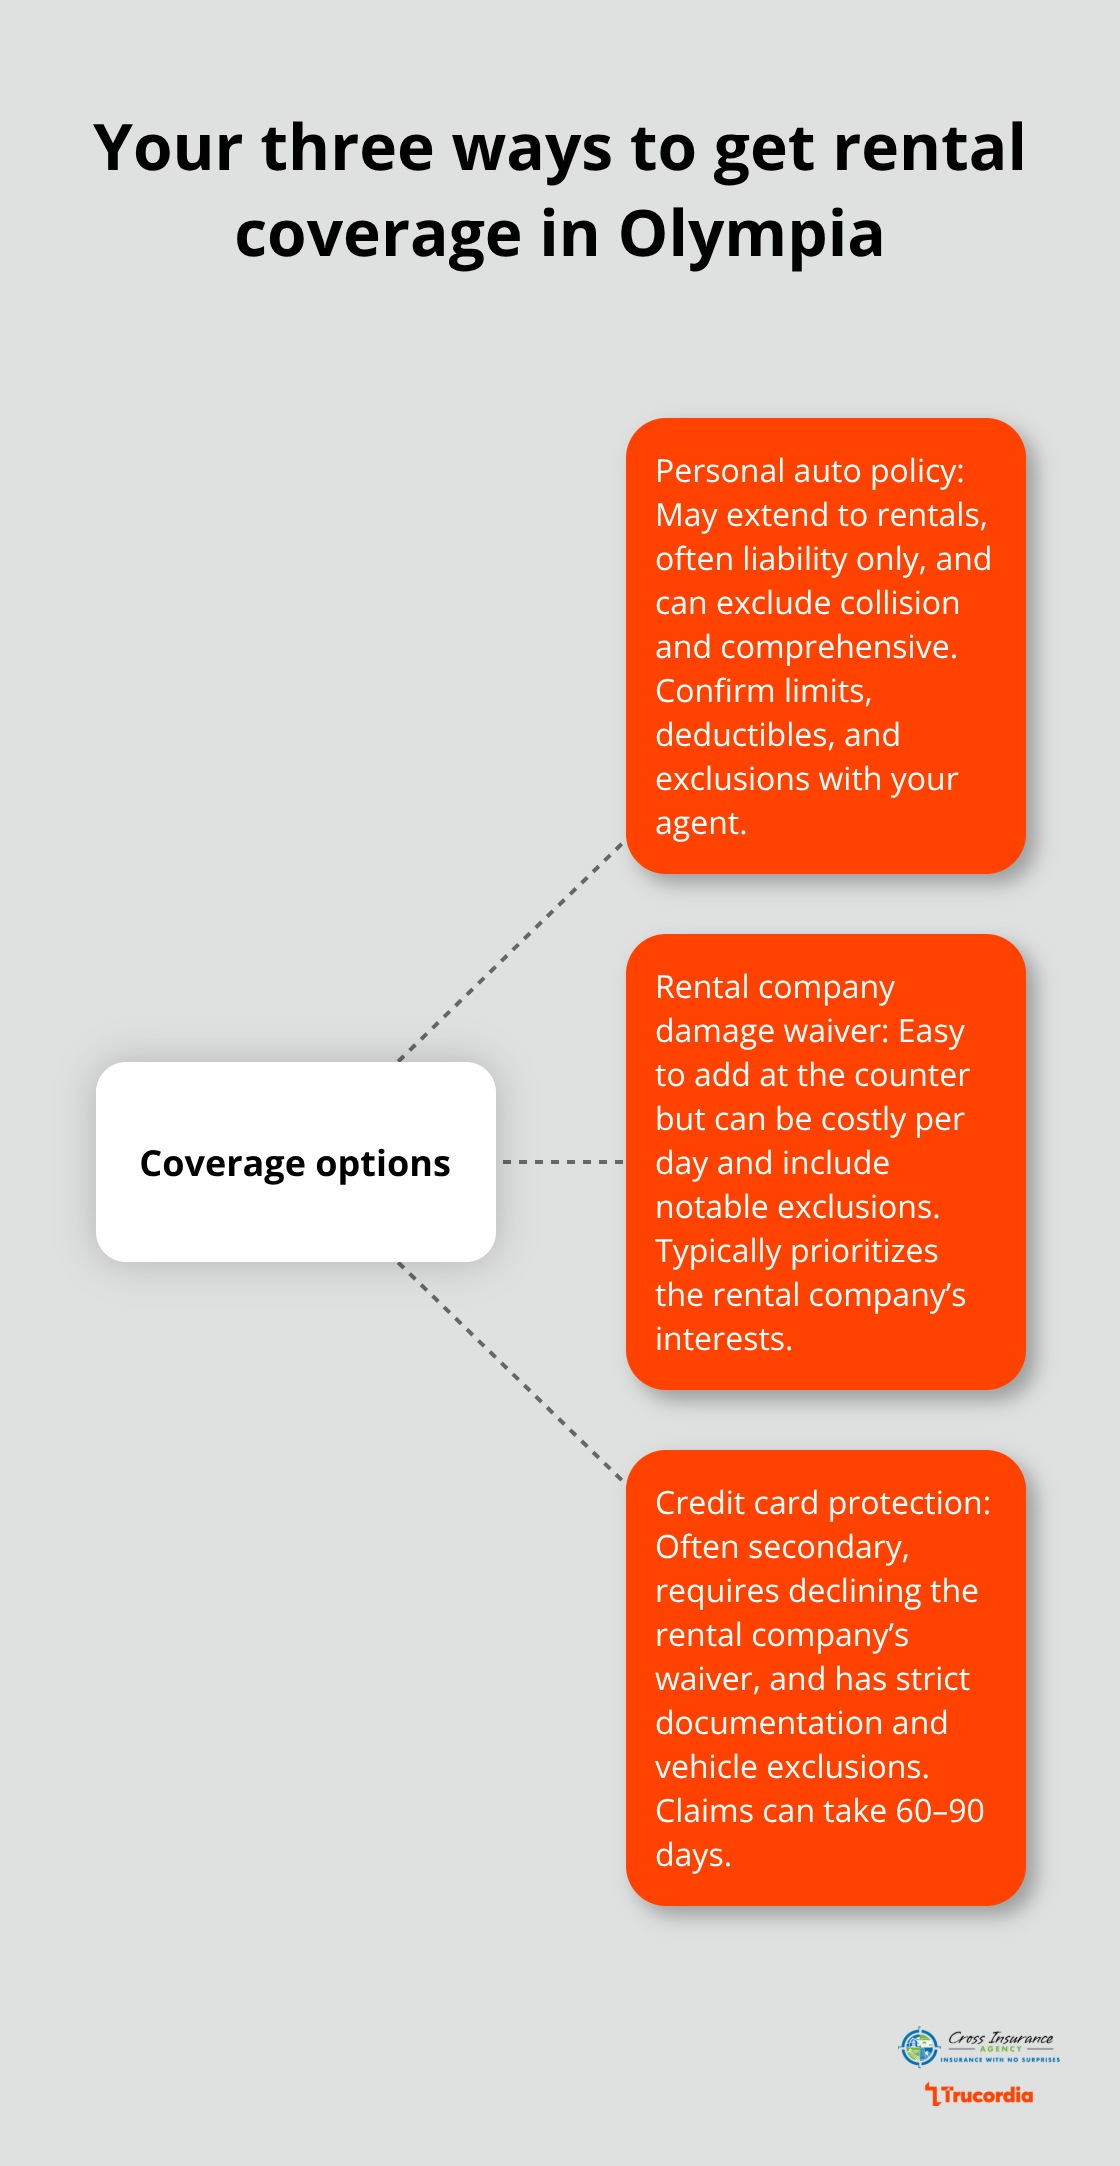
Your personal auto policy might extend to rentals, but most standard policies exclude them entirely or cover only liability while leaving you exposed to collision and comprehensive damage. The only way to know is to call your insurance agent and ask specifically whether your policy covers rental vehicles, what limits apply, and what exclusions exist. Many Olympia drivers discover gaps only after damage occurs, which is too late.
If your policy does cover rentals, check the deductible-it often runs higher for rentals than your personal vehicles, sometimes reaching $1,000 or more. Some policies also exclude coverage for certain rental types like luxury vehicles or trucks, so verify those details before you sign a rental agreement.
Rental Company Damage Waivers: What They Hide
Rental car companies push their own damage waivers aggressively at the counter, and for good reason-they generate significant revenue. The rental company’s collision damage waiver typically costs between $15 and $30 per day, which adds up quickly on a week-long trip.
What rental companies won’t emphasize is that these waivers often contain exclusions for off-road use, racing, mechanical breakdown, or damage from weather events. They also shift liability for the rental vehicle’s maintenance onto you, meaning if the brakes fail and you cause an accident, you could still face charges. The rental company’s liability coverage is usually minimal and protects them, not you.
Credit Card Rental Protection: The Hidden Costs
Credit card rental protection sounds free until you need it-most cards require you to decline the rental company’s coverage first, which creates immediate conflict with the rental agent. Many cards exclude luxury vehicles, exotic cars, or vehicles rented for business use. The claims process for credit cards is notoriously slow, sometimes taking 60 to 90 days, and requires extensive documentation.
These limitations mean credit card protection often fails when you need it most. A dedicated rental coverage policy eliminates these complications, provides clear coverage without exclusions hiding in fine print, and gives you immediate protection without disputes. When you compare your three options side by side, the choice becomes clear about which path protects you best.
Picking the Right Coverage for Your Rental
Ask Your Agent Three Specific Questions
Start by calling your insurance agent and asking three specific questions: Does my personal auto policy cover rental vehicles? If yes, what is the deductible for rentals, and what limits apply? What exclusions exist? Your agent should provide written answers, not vague reassurances. Once you have those answers, you can compare them against the rental company’s daily waiver cost and your credit card benefits.
Calculate the Math on Deductibles and Daily Costs
If your personal policy covers collision and comprehensive damage with a deductible under $500, you likely don’t need additional rental coverage unless you’re renting a luxury vehicle or traveling internationally. However, if your policy excludes rentals entirely or carries a $1,000 deductible, the rental company’s daily waiver becomes more attractive despite its cost. A $20 daily waiver over seven days costs $140, while a single accident with a $1,000 deductible could leave you paying thousands out of pocket. The decision isn’t about finding the cheapest option-it’s about identifying which scenario protects you without draining your wallet.
Credit Card Coverage Creates Conflicts at the Rental Counter
Washington drivers often overlook one critical detail: your credit card’s rental protection typically requires you to decline the rental company’s coverage, which puts you in direct conflict with the rental agent at the counter. The agent will pressure you to purchase their waiver, and if you refuse, they may require a credit card authorization hold for $15,000 to $50,000 depending on the vehicle class. That hold can cause problems if your card has a low limit or if you’re planning to use that card for other expenses during your trip.
Credit Card Exclusions Eliminate Coverage When You Need It
Credit card coverage excludes business rentals, luxury vehicles over certain price points, and often requires you to submit claims within 90 days with receipts, police reports, and repair estimates. For Olympia residents who rent occasionally for personal travel, credit card coverage might work. For anyone renting multiple times annually or for business purposes, a standalone rental policy removes these complications entirely and costs far less than you’d expect-often between $3 and $8 per day through an independent agent who can shop rates across multiple carriers.
Final Thoughts
Rental car insurance in Olympia protects you from financial exposure that your personal auto policy might not cover. Call your insurance agent today and ask three specific questions: Does my policy cover rentals, what deductible applies, and what exclusions exist? That single conversation eliminates guesswork and prevents costly surprises when damage occurs.
We at Cross Insurance Agency work with Olympia residents to identify coverage gaps and find rental car insurance solutions that fit your travel patterns and budget. Our licensed agents shop multiple carriers to deliver options you won’t find by calling rental companies or relying on credit card benefits. Whether you rent occasionally for vacation or frequently for business, we connect you with coverage that actually protects you without redundant costs.
Contact Cross Insurance Agency before your next rental to review your existing coverage and explore independent carrier options. We’ll explain what rental car insurance in Olympia costs through carriers beyond the rental counter and help you make a decision based on facts rather than pressure. Protection starts with understanding your options, and that’s exactly what we provide.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


