
Condo Insurance Olympia WA: Is Your Policy a Good Fit for Your Building
Condo insurance in Olympia, WA protects your investment, but many owners don’t realize their policies have significant gaps. Your condo association’s master policy covers the building structure, but it leaves your personal belongings, liability exposure, and unit improvements unprotected.
At Cross Insurance Agency, we’ve seen too many Olympia condo owners discover coverage shortfalls only after a claim. This guide walks you through what your policy should cover and how to spot weaknesses before they cost you money.
What Your Condo Policy Actually Covers
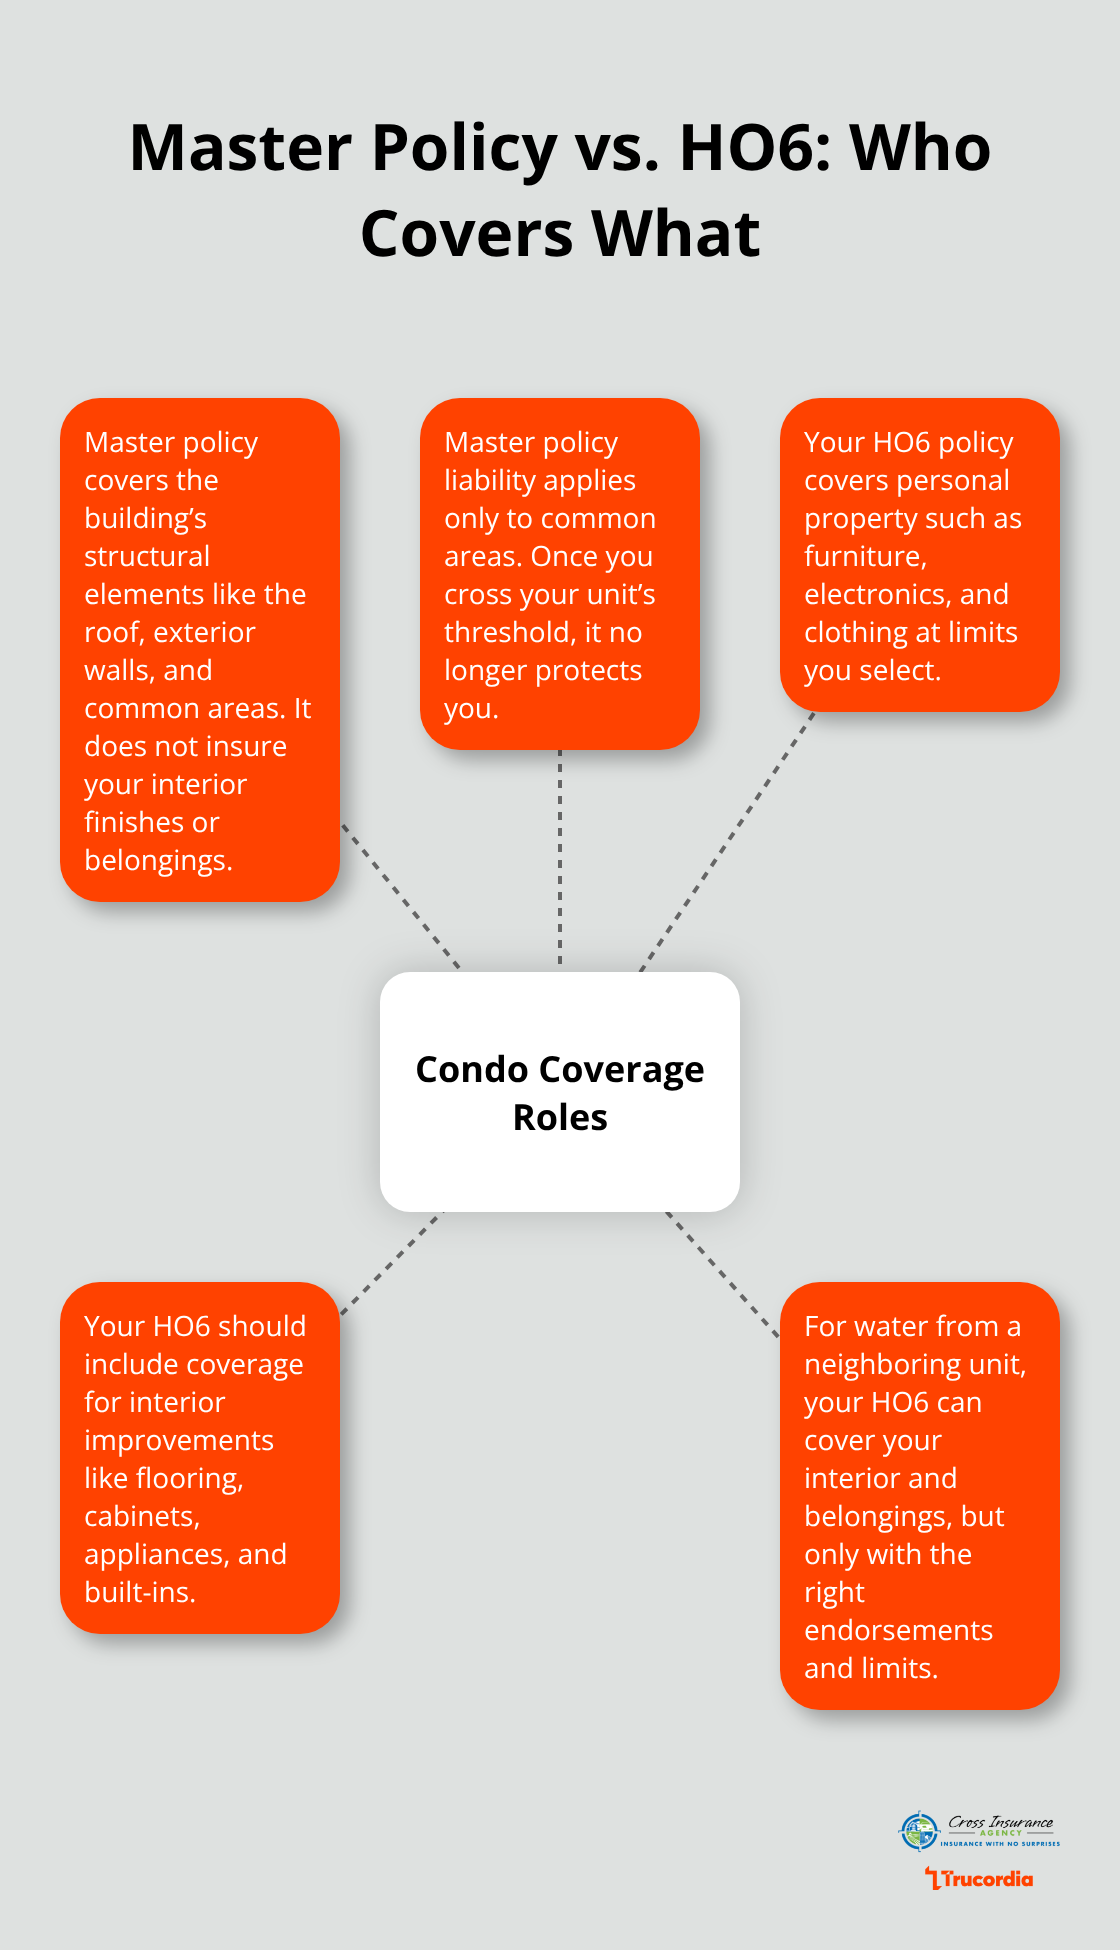
Olympia’s condo market includes roughly 8,000 registered condominiums, according to Thurston County assessor data, and nearly all operate under a master insurance policy paid through association dues. That master policy covers the building’s structural elements-the roof, walls, common areas, and the bones of your unit itself. Your association’s policy does not cover your interior walls, flooring, cabinetry, appliances, furniture, or anything else inside your four walls. Most owners make their first mistake here: they assume the association’s coverage protects their personal investment when it absolutely does not. The master policy also carries liability coverage for common areas, but it stops at your unit’s threshold. If someone slips in a hallway, the association’s liability pays. If someone trips on your bathroom tile, your personal liability policy pays, and you need one.
Your HO6 Policy Fills the Actual Gaps
You need an HO6 condo owner’s policy to cover everything the master policy leaves exposed. This policy protects your personal property, your unit’s interior improvements, and your personal liability. If you’ve upgraded your kitchen, replaced flooring, or added built-in shelving, those improvements belong to you and require coverage under your individual policy. Water damage from a neighbor’s burst pipe ranks among the most common claims in Olympia condos, especially in older buildings along the Capitol Lake waterfront. Your HO6 policy covers damage to your belongings and interior from water originating outside your unit, but only if you carry the right coverage limits.
Coverage Limits That Actually Match Your Building
Many owners carry inadequate limits-$100,000 or less-when Olympia’s average condo replacement cost runs $250,000 to $400,000 for mid-range units. Your association likely requires minimum coverage of at least $50,000, but that’s a floor, not a ceiling. You should also carry loss assessment coverage, which protects you if the association bills owners for uninsured losses or deductible costs from a major claim. This protection matters most when a single incident (a roof collapse or major fire) affects multiple units and exhausts the association’s deductible.
What Happens When the Master Policy Falls Short
Water intrusion, structural failures, and liability disputes between neighbors create situations where the master policy’s limits and your individual coverage must work together. Your personal policy steps in where the association’s coverage ends, but only if you’ve structured your limits correctly. This is where most Olympia condo owners face real financial exposure-not from what they know about, but from what they’ve overlooked.
Coverage Gaps That Cost Olympia Condo Owners Real Money
Liability Limits That Fall Short of Real Disputes
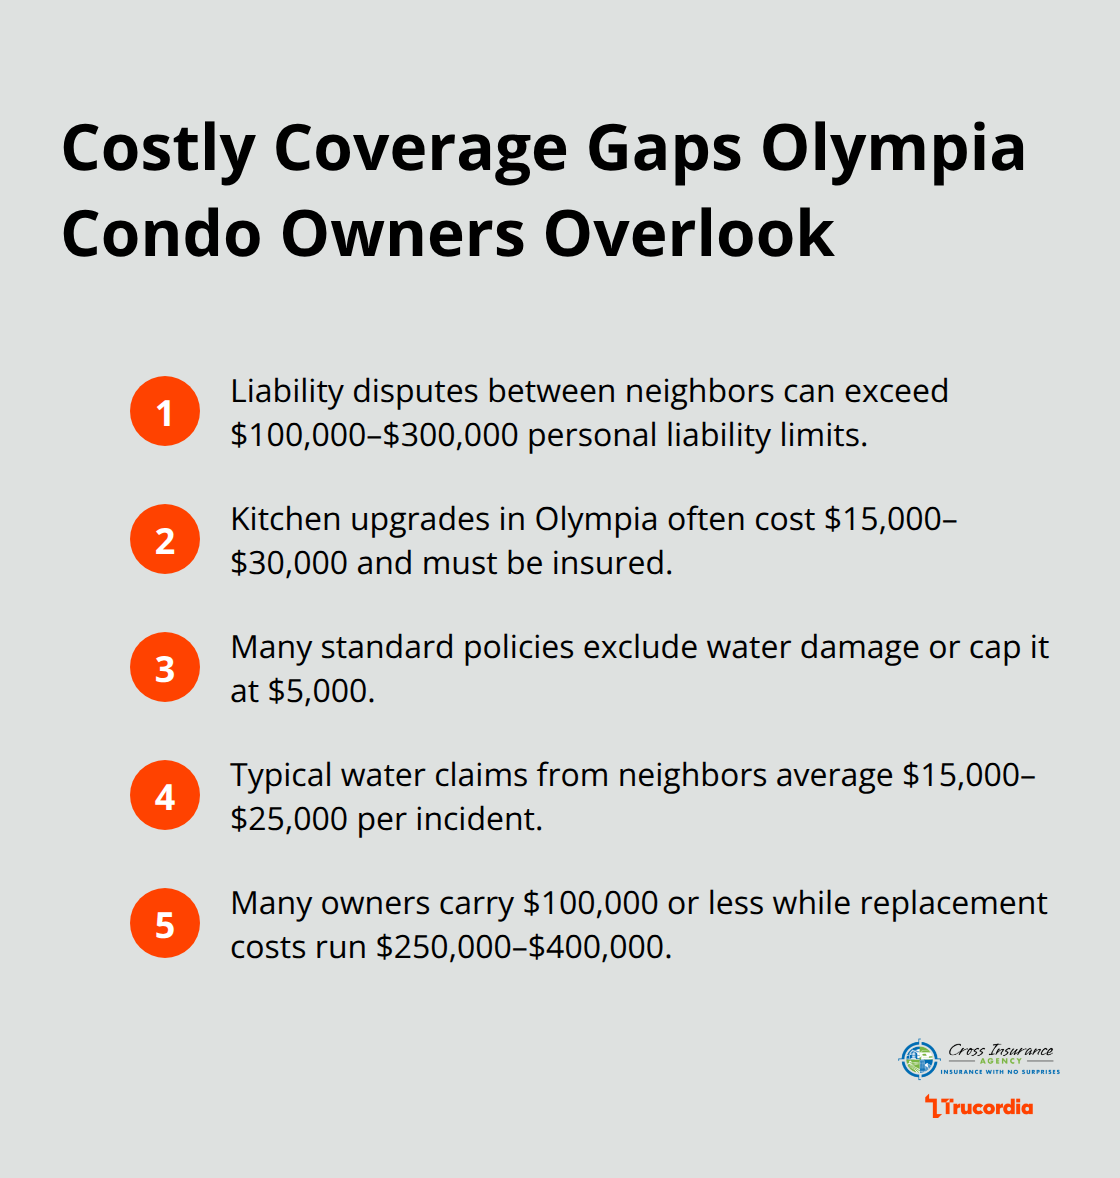
Most Olympia condo owners underestimate their liability exposure because they confuse the association’s common-area liability coverage with their own personal liability protection. Your HO6 policy typically carries $100,000 to $300,000 in personal liability coverage, but disputes between neighbors over water damage, structural defects, or shared wall problems routinely exceed these limits. When a neighbor’s water damage claim reaches $150,000 and your policy maxes out at $100,000, you personally owe the difference. Thurston County property values have climbed steadily, and liability awards have followed. A $300,000 liability limit costs only slightly more in annual premiums than $100,000, yet provides genuine protection for your actual financial exposure.
Structural Improvements You Thought Were Covered
Owners often assume that kitchen renovations, bathroom upgrades, flooring replacements, or added closet systems fall under the master policy because they’re physically attached to the unit. They don’t. Your HO6 policy must explicitly cover these improvements, and your coverage limit should reflect their actual replacement cost. An upgraded kitchen alone runs $15,000 to $30,000 in Olympia’s current market. Without adequate coverage limits for improvements, you absorb that loss yourself.
The association’s master policy protects only the building’s structural shell-not the investments you’ve made inside your four walls.
Water Damage Caps That Leave You Exposed
Water damage from neighbors creates the most common claim gap, particularly in older Olympia buildings constructed before modern waterproofing standards. Your HO6 covers belongings damaged by water originating outside your unit, but only if you carry water backup coverage or agreed-upon water damage limits. Many standard policies exclude water damage entirely or cap it at $5,000. A single incident involving a failed pipe in the unit above can saturate flooring, drywall, cabinetry, and personal property worth far more than that cap. Olympia’s climate brings consistent moisture exposure, making this coverage non-negotiable rather than optional.
How These Gaps Interact in Real Claims
When multiple coverage gaps overlap-inadequate liability limits, unprotected improvements, and water damage exclusions-a single incident can create financial exposure that extends well beyond your policy’s protection. The association’s master policy covers the building structure, but your personal policy must stand alone for everything inside your unit. This separation means you carry the full weight of underinsurance if your limits don’t match your actual exposure. Evaluating whether your current policy fits your building requires a direct comparison between what you own, what you’ve improved, and what your policy actually protects.
How to Evaluate if Your Current Policy Fits Your Building
Obtain Your Association’s Master Policy Details
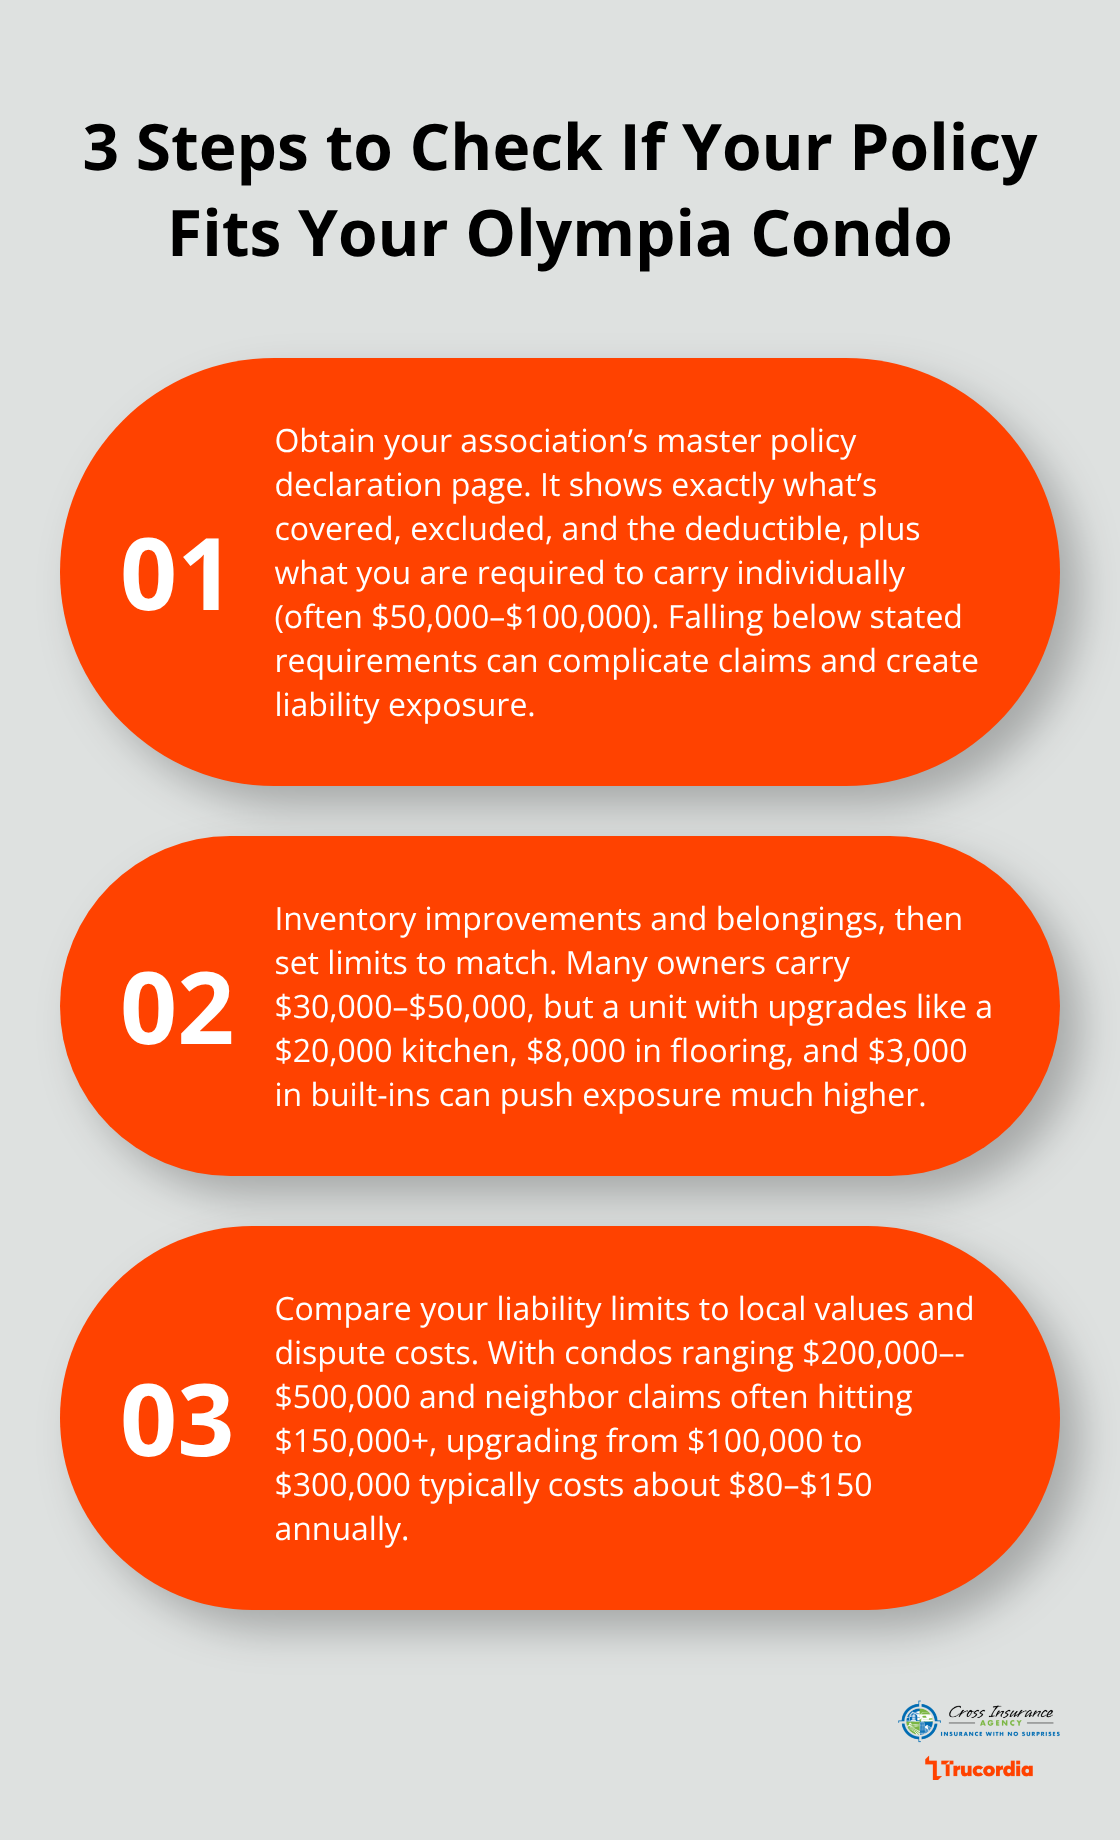
Start by requesting your condo association’s master policy declaration page from your board or property manager. This document specifies exactly what the association covers, what it excludes, and what deductible applies to claims. Many Olympia condo owners have never seen this document, which means they operate without knowing their coverage gaps. The declaration page shows your association’s liability limits, whether water damage receives coverage under the master policy, and what the association requires you to carry individually. Some associations mandate minimum HO6 limits of $50,000; others require $100,000 or more. If your current policy falls below what your association requires, you violate your ownership agreement, and that violation could complicate claims or create liability exposure during disputes.
Inventory Your Unit’s Actual Improvements and Belongings
Walk through each room and list major items: furniture, electronics, artwork, and any structural improvements you’ve made. An Olympia condo owner with a $20,000 kitchen renovation, $8,000 in flooring upgrades, $3,000 in built-in shelving, and $15,000 in furniture and electronics needs coverage limits reflecting that $46,000 total investment. Most owners carry $30,000 to $50,000 in coverage and assume it’s adequate when their actual exposure runs significantly higher. Your HO6 policy should cover both personal property replacement cost and improvement coverage at amounts matching your real inventory.
Pull your current policy declarations and compare the personal property limit and improvement coverage limit against your actual totals. If either limit falls short, you remain underinsured and personally liable for the difference in a claim.
Assess Water Damage Coverage Against Local Risk
Olympia’s older condo buildings along Capitol Lake and downtown areas face elevated water intrusion risk from aging pipes, failed waterproofing, and ground-level moisture. Your policy should explicitly cover water damage from sources outside your unit, not exclude it or cap it at $5,000. Contact your agent and confirm whether your current policy includes water backup coverage or whether water damage receives exclusion entirely. If excluded, request an endorsement adding it or switch carriers if your current insurer won’t provide it. Water damage from neighbors creates the most common claim gap in Olympia’s condo market, with claims averaging $15K to $25K per incident. A single incident involving a failed pipe in the unit above can saturate flooring, drywall, cabinetry, and personal property worth far more than a $5,000 cap.
Compare Your Liability Limits to Current Market Values
Compare your liability limit against Olympia’s property values and typical dispute costs. A $100,000 liability limit made sense ten years ago when median condo values ran lower. Today, with Thurston County assessor data showing condo values ranging from $200,000 to $500,000 depending on location and condition, liability awards in neighbor disputes frequently reach $150,000 or more. Most Olympia condo owners underestimate their liability exposure because they confuse the association’s common-area liability coverage with their own personal liability protection. Your HO6 policy typically carries $100,000 to $300,000 in personal liability coverage, but disputes between neighbors over water damage, structural defects, or shared wall problems routinely exceed these limits. When a neighbor’s water damage claim reaches $150,000 and your policy maxes out at $100,000, you personally owe the difference. Upgrading from $100,000 to $300,000 in personal liability coverage costs approximately $80 to $150 annually but protects your actual financial exposure. This comparison between your current limits and Olympia’s current market values reveals whether your policy genuinely fits your building or whether you carry yesterday’s coverage for today’s risks.
Final Thoughts
Your condo insurance in Olympia, WA requires the same attention you’d give to any major financial decision. Pull your current HO6 policy declaration and your association’s master policy details side by side, then compare your personal property limit, improvement coverage, and liability limit against what you actually own and what your building requires. If gaps exist between your coverage and your real exposure, contact your agent immediately and request updated quotes-most Olympia condo owners discover their coverage falls short only after a claim, which means you operate with unnecessary financial risk right now.
A local insurance agent who understands Olympia’s condo market makes this evaluation straightforward. They know which carriers offer the best rates for water damage coverage in older buildings, which liability limits make sense given current property values, and how to structure your policy so it works seamlessly with your association’s master coverage. At Cross Insurance Agency, our licensed agents shop multiple top-rated carriers to find you the right protection at competitive rates, and we provide local claims advocacy when you need it most.
Schedule a policy review with an agent who knows condo insurance and bring your current declarations and your association’s master policy. Spend thirty minutes comparing your actual exposure against your current limits-if your liability limit sits at $100,000 while your condo’s value exceeds $300,000, upgrading costs less than $150 annually but protects your actual financial exposure. Contact Cross Insurance Agency to start your review today and stop carrying yesterday’s coverage for today’s risks.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


