
Flood Insurance Olympia WA: Protecting Homes Against Rising Water Risks
Olympia sits in one of the wettest regions in the country, and flooding poses a real threat to homeowners here. Standard homeowners insurance won’t cover water damage from floods, leaving many properties vulnerable.
At Cross Insurance Agency, we help Olympia residents understand their flood insurance options and find coverage that actually protects their investment. This guide walks you through everything you need to know about flood insurance in Olympia, WA.
Why Flood Risk Is Real in Olympia
Olympia’s Geography Creates Unavoidable Flood Threats
Olympia’s location makes flooding inevitable rather than unlikely. The city sits in the Puget Sound region where heavy rainfall, snowmelt, and proximity to water bodies create perfect conditions for water damage. According to the National Oceanic and Atmospheric Administration, the Pacific Northwest receives an average of 50 to 80 inches of precipitation annually, with some areas exceeding 100 inches. Thurston County, where Olympia is located, experiences significant flood events roughly every 10 to 15 years.
The Deschutes River, which runs through the area, has flooded neighborhoods multiple times in the past two decades. Properties within the 100-year floodplain face a 26% chance of experiencing a flood during a 30-year mortgage period, according to FEMA data. Even homes outside designated flood zones can suffer water damage from localized flooding, stormwater backup, or overwhelmed drainage systems.
Standard Homeowners Insurance Leaves You Exposed
Most homeowners make a critical mistake when they assume their standard policy covers flood damage. Standard homeowners insurance policies explicitly exclude flood damage, treating it as a separate peril that requires dedicated coverage. The Insurance Information Institute reports that the average homeowners insurance claim for water damage costs around $11,000, but flood damage claims can be substantial.
In 2023, the National Flood Insurance Program paid out over $3.2 billion in claims nationwide, yet many policyholders remained underinsured or uninsured. If water enters your home through a broken pipe or roof leak, your homeowners policy covers it. If floodwater from rising rivers or heavy rain penetration damages your property, you’re on your own. This gap leaves Olympia homeowners exposed to substantial financial risk.
Your current homeowners policy likely contains specific language that excludes water damage from external sources (like rivers, storms, or drainage failures). Understanding this distinction between covered water damage and excluded flood damage matters when you face actual loss. The financial consequences of this gap can devastate your finances without proper flood insurance in place.
Your Flood Insurance Choices in Washington
The National Flood Insurance Program Remains Your Baseline Option
The National Flood Insurance Program (NFIP) covers approximately 5.6 million policies nationwide as of 2024, making it the dominant flood coverage option in Washington. NFIP policies cap building coverage at $250,000 and personal property coverage at $100,000-a significant limitation if your Olympia home exceeds these thresholds. The Federal Emergency Management Agency sets NFIP rates, so you’ll find consistent pricing across carriers rather than competitive bidding. Premiums typically range from $400 to $3,000 annually for standard-risk properties in Washington, calculated based on your flood zone designation and your home’s elevation relative to the base flood elevation.
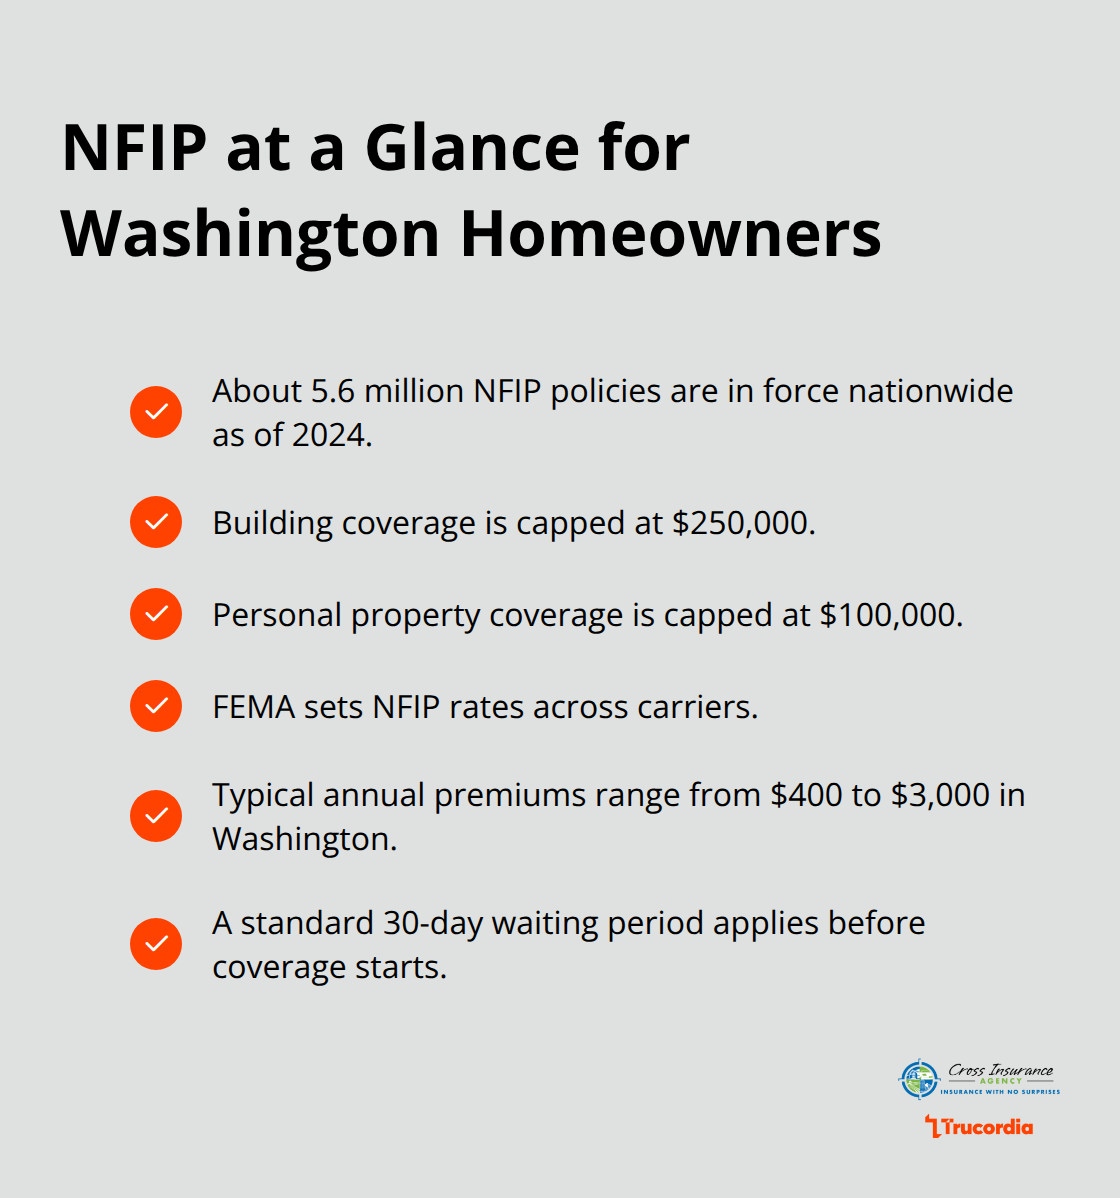
One critical advantage of NFIP: the program includes a 30-day waiting period before coverage takes effect. This timing matters significantly when you anticipate seasonal flooding, so you should apply well before heavy rain seasons arrive. Understanding how insurance works provides a solid foundation before exploring alternatives, since it often delivers the most affordable baseline coverage for moderate-risk properties.
Private Flood Insurance Offers Competitive Alternatives
Private flood insurance has expanded substantially in Washington over the past five years, offering higher coverage limits and potentially better rates for properties outside high-risk zones. Companies like AquaVest and Kin now write flood policies in Washington, sometimes undercutting NFIP premiums by 20 to 40 percent for low-to-moderate risk properties. However, private policies vary dramatically in coverage scope and exclusions, so direct comparison matters before you purchase.
Properties in designated high-risk zones (A or V zones) cannot purchase private flood insurance in most cases and must use NFIP instead. For Olympia properties outside high-risk zones, private policies can offer superior coverage options, including replacement cost coverage instead of actual cash value and higher deductible choices that lower premiums. These alternatives provide flexibility that NFIP cannot match for many homeowners.
Identifying Your Flood Zone Determines Your Options
Visit FEMA’s Flood Map Service Center online and enter your address to identify your property’s flood zone classification. The map shows whether you’re in the high-risk 100-year floodplain, moderate-risk 500-year zone, or lower-risk area. Your flood zone designation directly controls which insurance products you can purchase and what rates you’ll pay.
High-risk zone properties face mandatory flood insurance requirements if you carry a federally-backed mortgage, while moderate and low-risk properties have more flexibility in their coverage decisions. Understanding your specific zone classification helps you compare NFIP and private options accurately. Once you know your flood zone, you can assess whether private carriers offer better value than NFIP for your particular situation, then move forward with securing the coverage that protects your Olympia investment.
Getting Your Flood Insurance in Place
Confirm Your Flood Zone and Coverage Requirements
Visit FEMA’s Flood Map Service Center and enter your Olympia address to confirm your exact flood zone classification. Contact your mortgage lender to ask whether flood insurance is mandatory for your loan-if you’re in a high-risk zone with a federally-backed mortgage, it is required. Gather your home’s key details: square footage, year built, elevation relative to base flood elevation if available, and replacement cost estimate. This information directly affects your premium quotes and helps carriers assess your actual risk profile.
Identify Which Carriers You Can Purchase From
If you’re in a high-risk A or V zone, NFIP becomes your only option. Request quotes from at least two NFIP-authorized carriers like State Farm or Allstate to compare their specific rates and service reputation. For properties outside high-risk zones, obtain NFIP quotes alongside private carrier options like AquaVest or Kin. Request quotes with identical coverage limits and deductible amounts so you’re comparing apples to apples-don’t let carriers quote you different protection levels that skew the price comparison.
Compare Coverage Limits and Policy Terms
NFIP policies cap building coverage at $250,000 and personal property at $100,000, which may leave substantial gaps if your Olympia home’s replacement cost exceeds those limits. Private policies sometimes offer replacement cost coverage instead of actual cash value, meaning you receive full repair costs without depreciation deductions. Check deductible options carefully: NFIP offers standard $1,000 deductibles but also allows $2,500, $5,000, and $10,000 options that lower premiums significantly if you can absorb higher out-of-pocket costs in a flood event. Private carriers often provide more deductible flexibility than NFIP.
Account for Waiting Periods and Seasonal Timing
Review waiting periods in your policy documents-NFIP’s standard 30-day waiting period means you need to apply well before seasonal heavy rains arrive. Don’t delay this decision into October or November when Olympia’s rainy season intensifies and flood risk peaks. The 30-day clock starts when your application is approved, so early action protects you when weather conditions matter most. Examine the actual policy language instead of just the premium numbers to understand what protection you actually receive.
Make Your Final Selection Based on Actual Protection
Select the policy that protects your home’s value, not just the quote that looks cheapest on paper. A lower premium that leaves your home underinsured creates false economy when a flood event occurs. Your coverage choice determines whether you can rebuild after water damage or face financial hardship. Take time to review all policy terms, coverage limits, and deductible options before you commit to a carrier.
Final Thoughts
Olympia’s flood risk demands action, not wishful thinking. The city’s geography, annual precipitation exceeding 50 inches, and proximity to the Deschutes River create genuine threats to your home and finances. Properties in the 100-year floodplain face a 26% chance of flooding during a 30-year mortgage, yet standard homeowners insurance won’t cover that damage-this gap costs homeowners thousands of dollars every year.
Flood insurance in Olympia WA protects your financial security when water damage strikes. The National Flood Insurance Program remains accessible for most properties, while private carriers offer competitive alternatives for homes outside high-risk zones. Waiting until November or December to apply means facing NFIP’s 30-day waiting period during peak flood season, leaving you exposed when you need protection most.
Contact Cross Insurance Agency to discuss your flood insurance options and secure the protection your Olympia home needs. Our licensed agents shop multiple carriers to deliver choice and personalized guidance tailored to your specific property and risk profile. Visit FEMA’s Flood Map Service Center to confirm your flood zone, then reach out to us so we can help you find coverage that actually protects your investment.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


