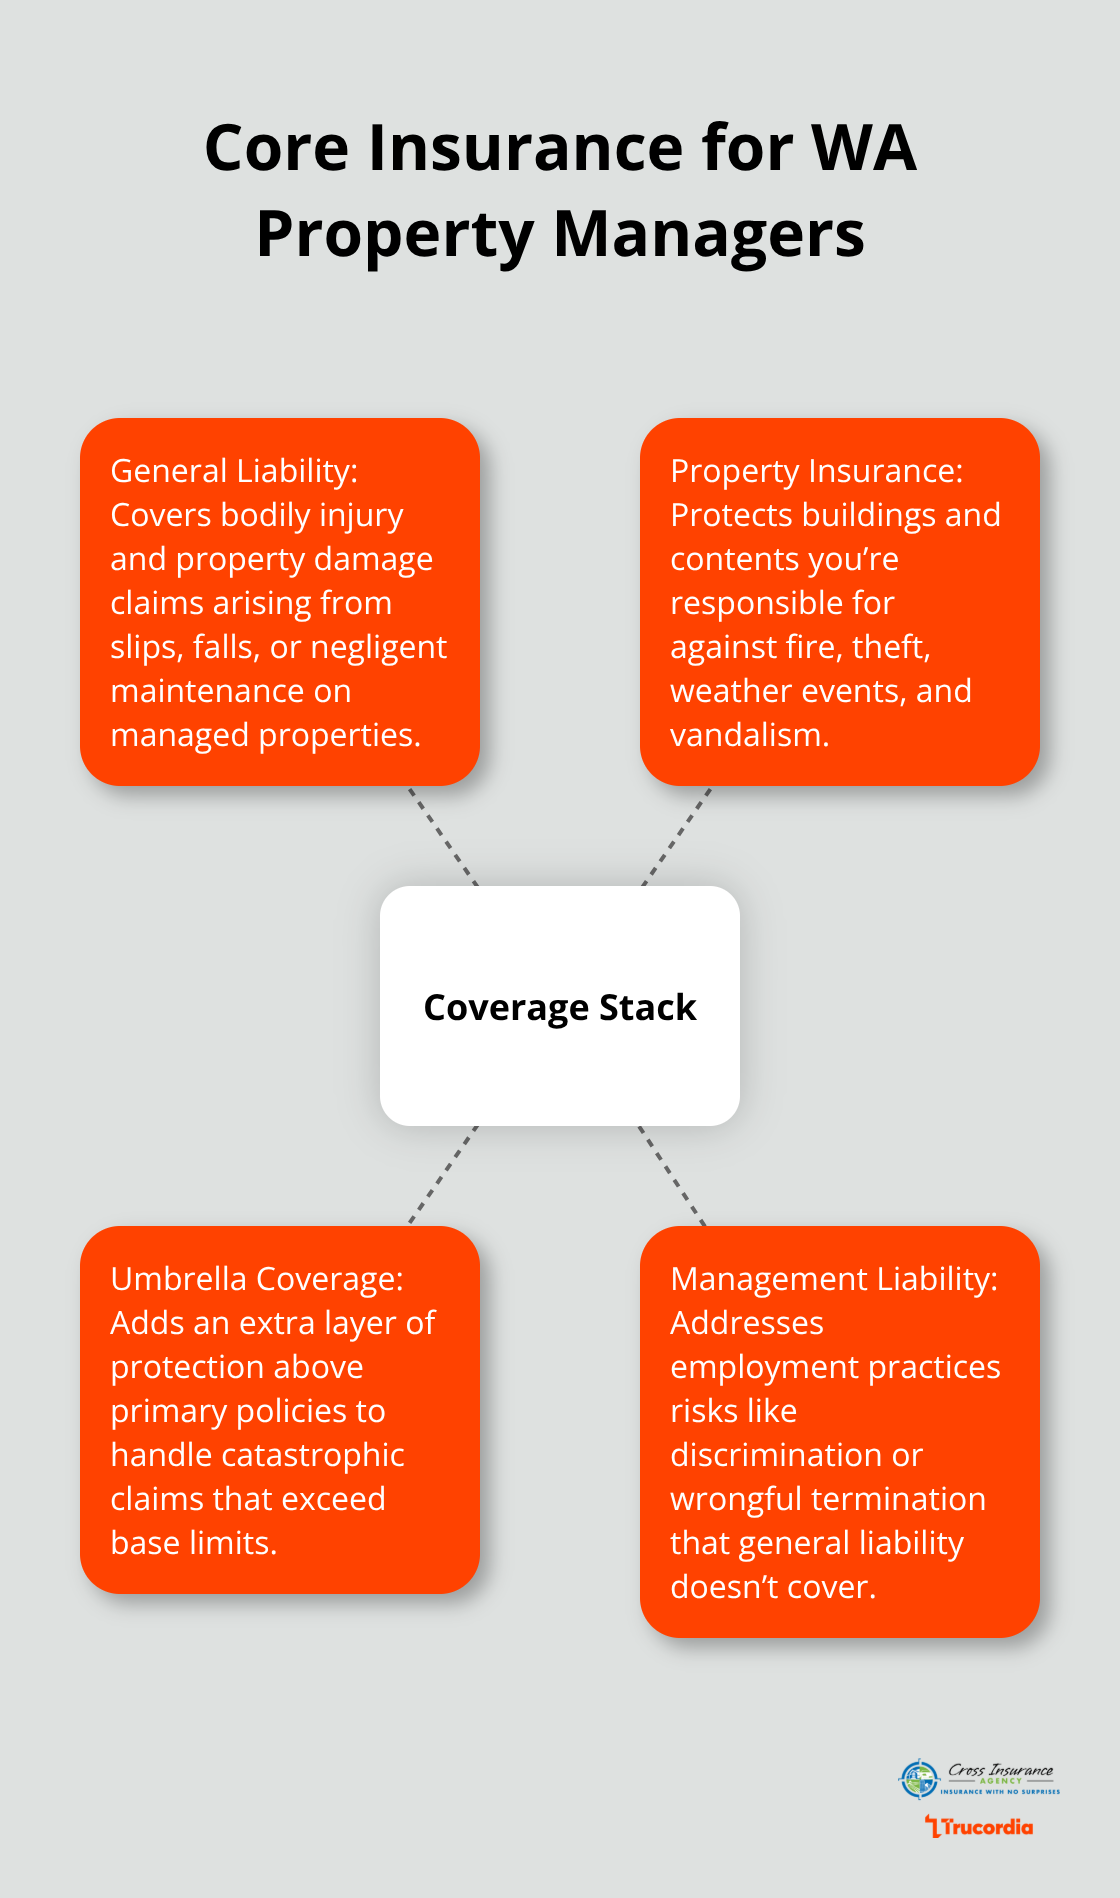
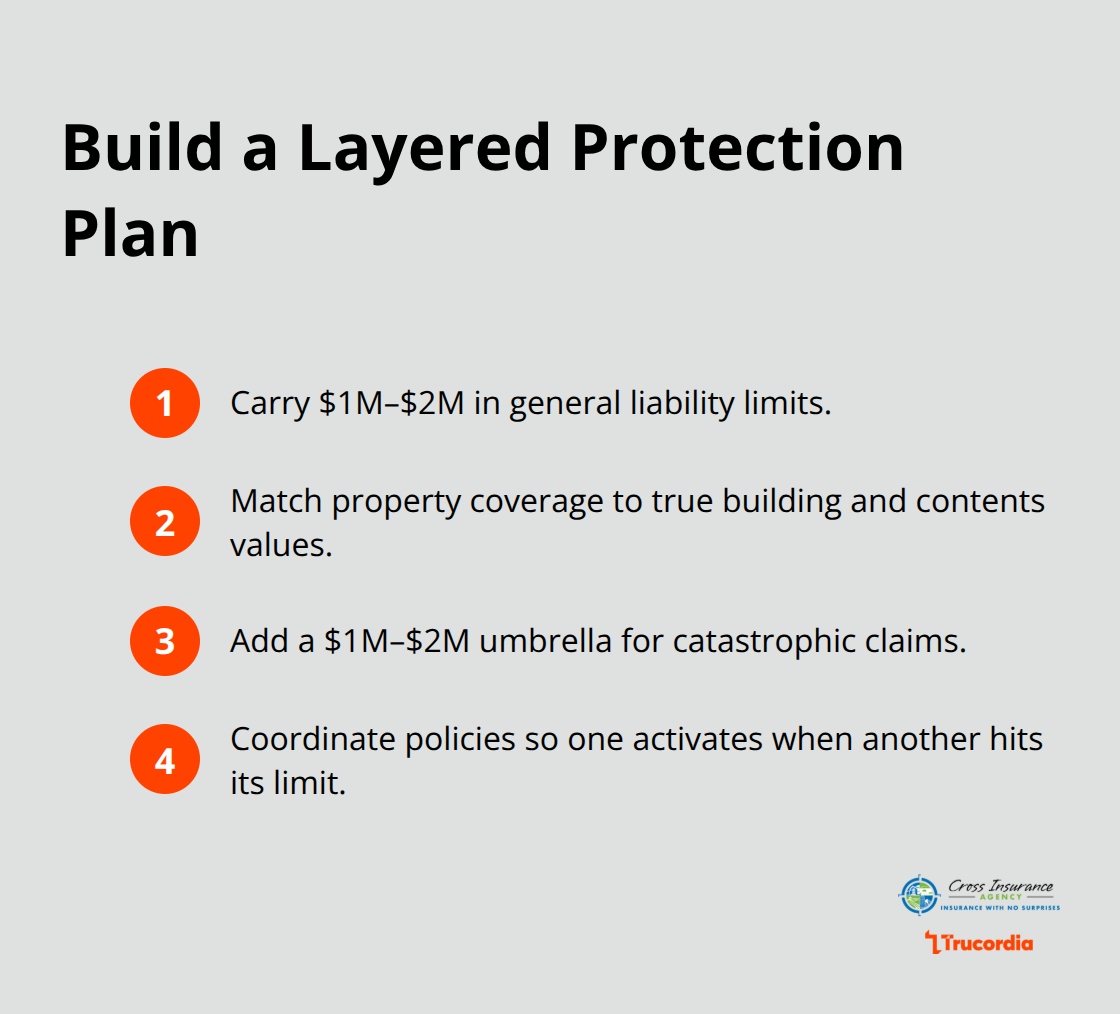
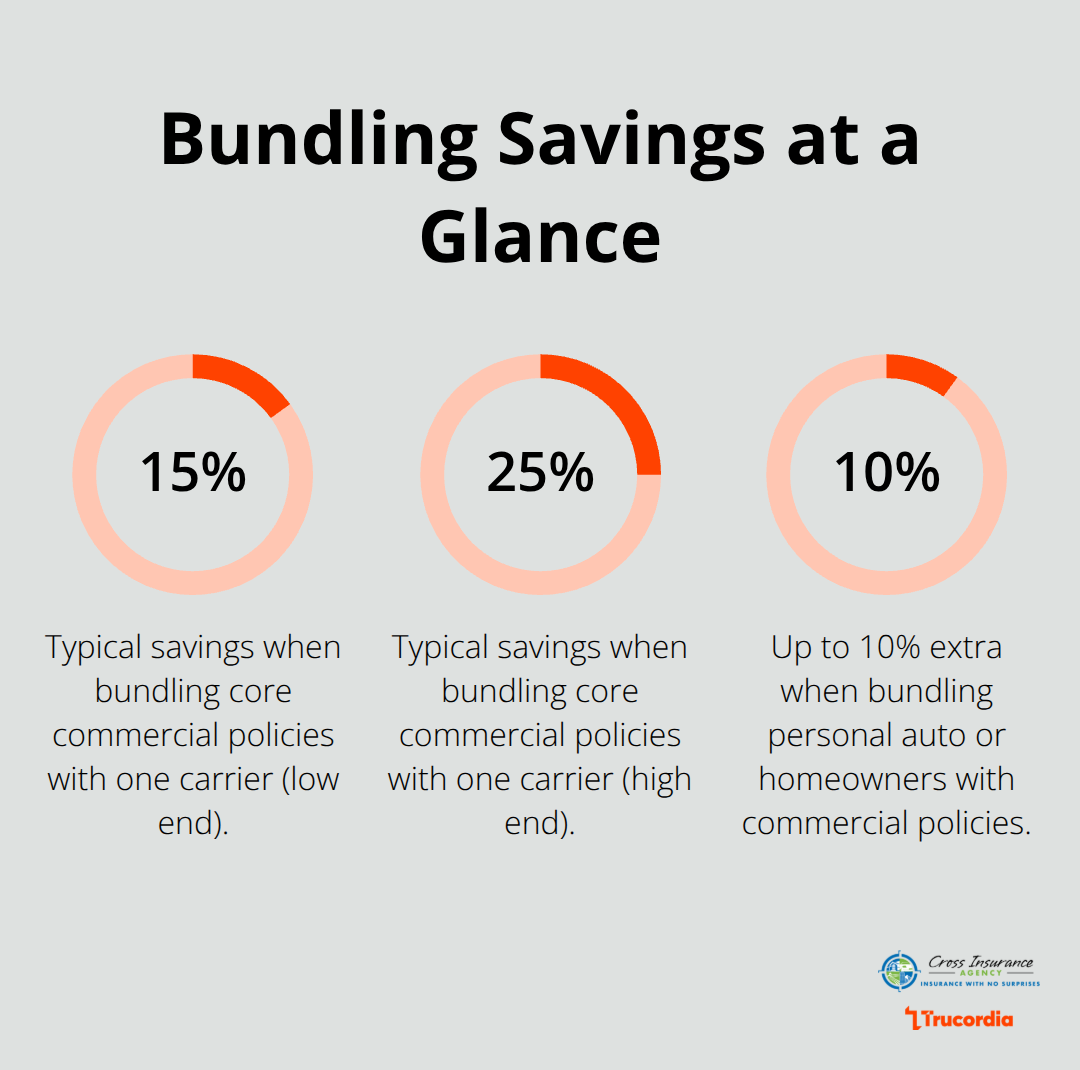
Property insurance in Centralia, WA protects what matters most-your home or business. Weather threats, fire, theft, and liability risks are real concerns for local property owners.

At Cross Insurance Agency, we help Centralia residents and business owners find coverage that fits their specific needs. The right policy can make the difference between financial security and devastating loss.

Why Property Insurance Matters in Centralia

Centralia property owners face real financial exposure that standard homeowners or business policies often leave unprotected. Median property values in Centralia reached $318,200, which means replacement costs have climbed significantly. A fire, theft, or weather event that damages a property without adequate coverage creates a catastrophic loss that most households cannot absorb.
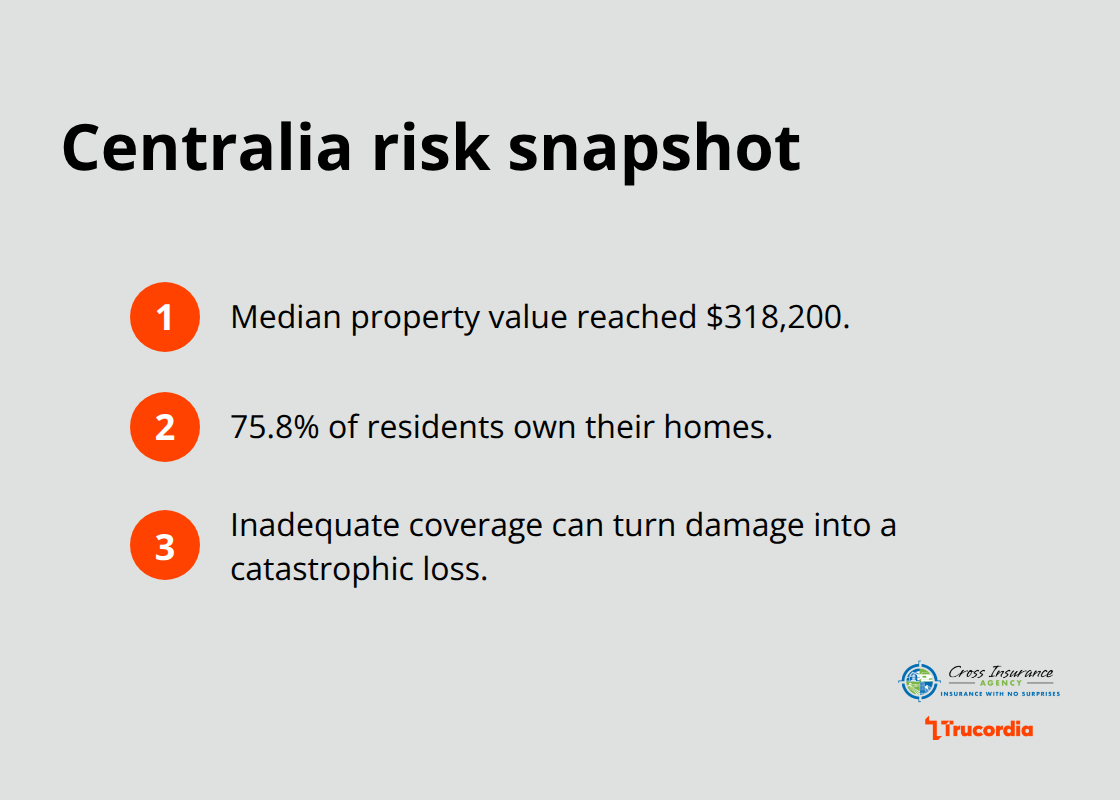
Key property risk facts for Centralia homeowners and property owners - property insurance Centralia WA

The stakes are particularly high in Centralia because 75.8% of residents own their homes, according to Data USA, making property protection a central financial concern for three out of four households in the community.

Weather and Natural Disaster Risks Are Increasing

Centralia’s location in Washington exposes properties to wind damage, heavy rainfall, and occasional severe storms that compromise roofs, foundations, and structural integrity. Standard homeowners policies cover wind and hail damage, but many property owners underestimate repair costs. A single roof replacement in Washington costs between $15,000 and $25,000 depending on square footage and materials, and deductibles of $1,000 to $2,500 mean you pay that amount out of pocket before coverage activates. Flood damage presents a separate problem entirely-homeowners policies explicitly exclude flood coverage, yet Centralia’s proximity to waterways and seasonal precipitation patterns create genuine flood risk. If you live in or near a flood zone, you must purchase a separate flood insurance policy through the National Flood Insurance Program or a private carrier. Without it, water damage from heavy rain or nearby creek overflow leaves you completely unprotected.

Fire and Theft Protection Secures Your Assets

Fire remains one of the most destructive property threats, and Centralia experiences structure fires that cause six-figure losses. Your homeowners or commercial property policy must include dwelling coverage at full replacement cost, not market value. Many property owners make the mistake of insuring their home at $300,000 when replacement cost actually totals $400,000, which triggers coinsurance penalties that force you to pay a portion of claims out of pocket. For businesses, commercial property insurance covers the building structure and its contents separately, and underinsuring either component creates a dangerous gap. Theft and burglary coverage protects against break-ins and stolen property, but limits vary widely-some policies cap coverage at $2,500 for jewelry or $5,000 for cash, which may not match your actual assets. You should document your possessions with photos and receipts to prove the value of items during a claim.

Legal and Mortgage Requirements Mandate Coverage

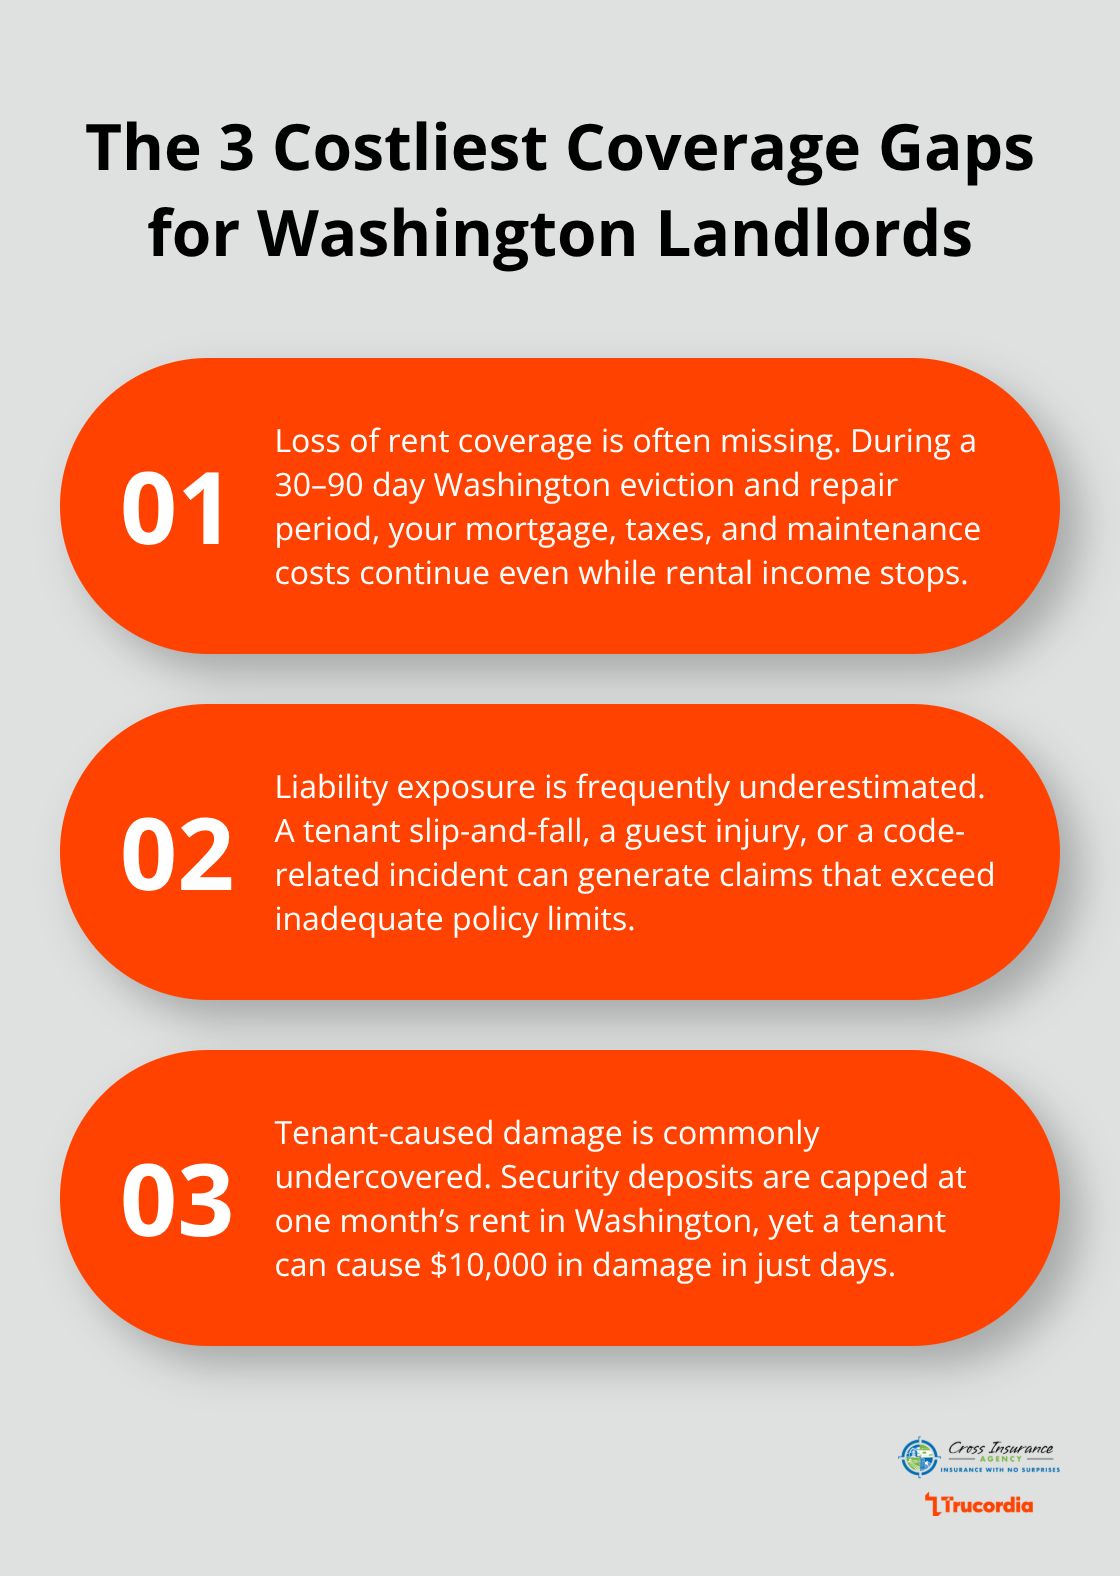
Mortgage lenders in Washington require homeowners insurance as a condition of financing, and if you fail to maintain a policy, the lender can force-place coverage on your behalf-which is typically more expensive and offers less protection than a policy you choose yourself. For rental properties, Washington landlords face additional legal exposure because the state’s Residential Tenancy Act strengthens tenant protections, raising liability exposure significantly. A tenant injury claim can exceed $100,000, and standard homeowners policies do not cover rental income loss or tenant-caused damage. If you own rental properties in Centralia, you must carry landlord insurance with adequate liability limits and loss-of-rent coverage. Business owners also face legal mandates-general liability insurance is often required by local permits, lease agreements, or contracts with clients, and skipping this coverage leaves your business vulnerable to lawsuits that can bankrupt the operation.

Understanding these legal requirements and real-world risks shapes what coverage you actually need. The next section examines the specific types of property insurance available in Centralia and how each one addresses different ownership situations.

Coverage Options That Match Your Centralia Property

Homeowners Insurance Fits Your Owner-Occupied Residence

Centralia homeowners access standard homeowners insurance that protects owner-occupied residences with dwelling coverage, personal property protection, and liability limits that typically range from $300,000 to $500,000. The median property value in Centralia is $385,800 according to Data USA, which means many homeowners must verify their dwelling coverage sits at or above full replacement cost rather than market value. You should obtain a professional replacement-cost appraisal or contractor reconstruction estimate before finalizing your policy-this step prevents the coinsurance penalty that strikes when your insured amount falls short of actual replacement costs. If your home’s true replacement cost is $450,000 but you insure it at $350,000, a total loss claim triggers a coinsurance clause that forces you to absorb a percentage of the loss yourself.

Condo owners in Centralia need a different approach entirely because the building structure is typically covered by the condo association’s master policy, leaving you to insure only interior walls, fixtures, and personal property through an HO-6 condo policy. This policy includes liability coverage for accidents that occur within your unit and protects against theft and damage to your belongings.

Commercial Property Insurance Protects Business Assets Separately

Commercial property insurance for Centralia businesses operates on a separate framework that splits building coverage and contents coverage into distinct protection buckets. Many small business owners make the mistake of insuring only the building structure while leaving inventory, equipment, and fixtures severely underinsured, which creates a dangerous gap when a fire or theft occurs. The three largest employers in Centralia are Health Care & Social Assistance with 4,784 jobs, Retail Trade with 4,242 jobs, and Manufacturing with 3,361 jobs according to Data USA, and each sector faces different property risks-hospitals need protection for expensive medical equipment, retail stores need inventory coverage with seasonal fluctuations, and manufacturing facilities require machinery and production-line asset protection.
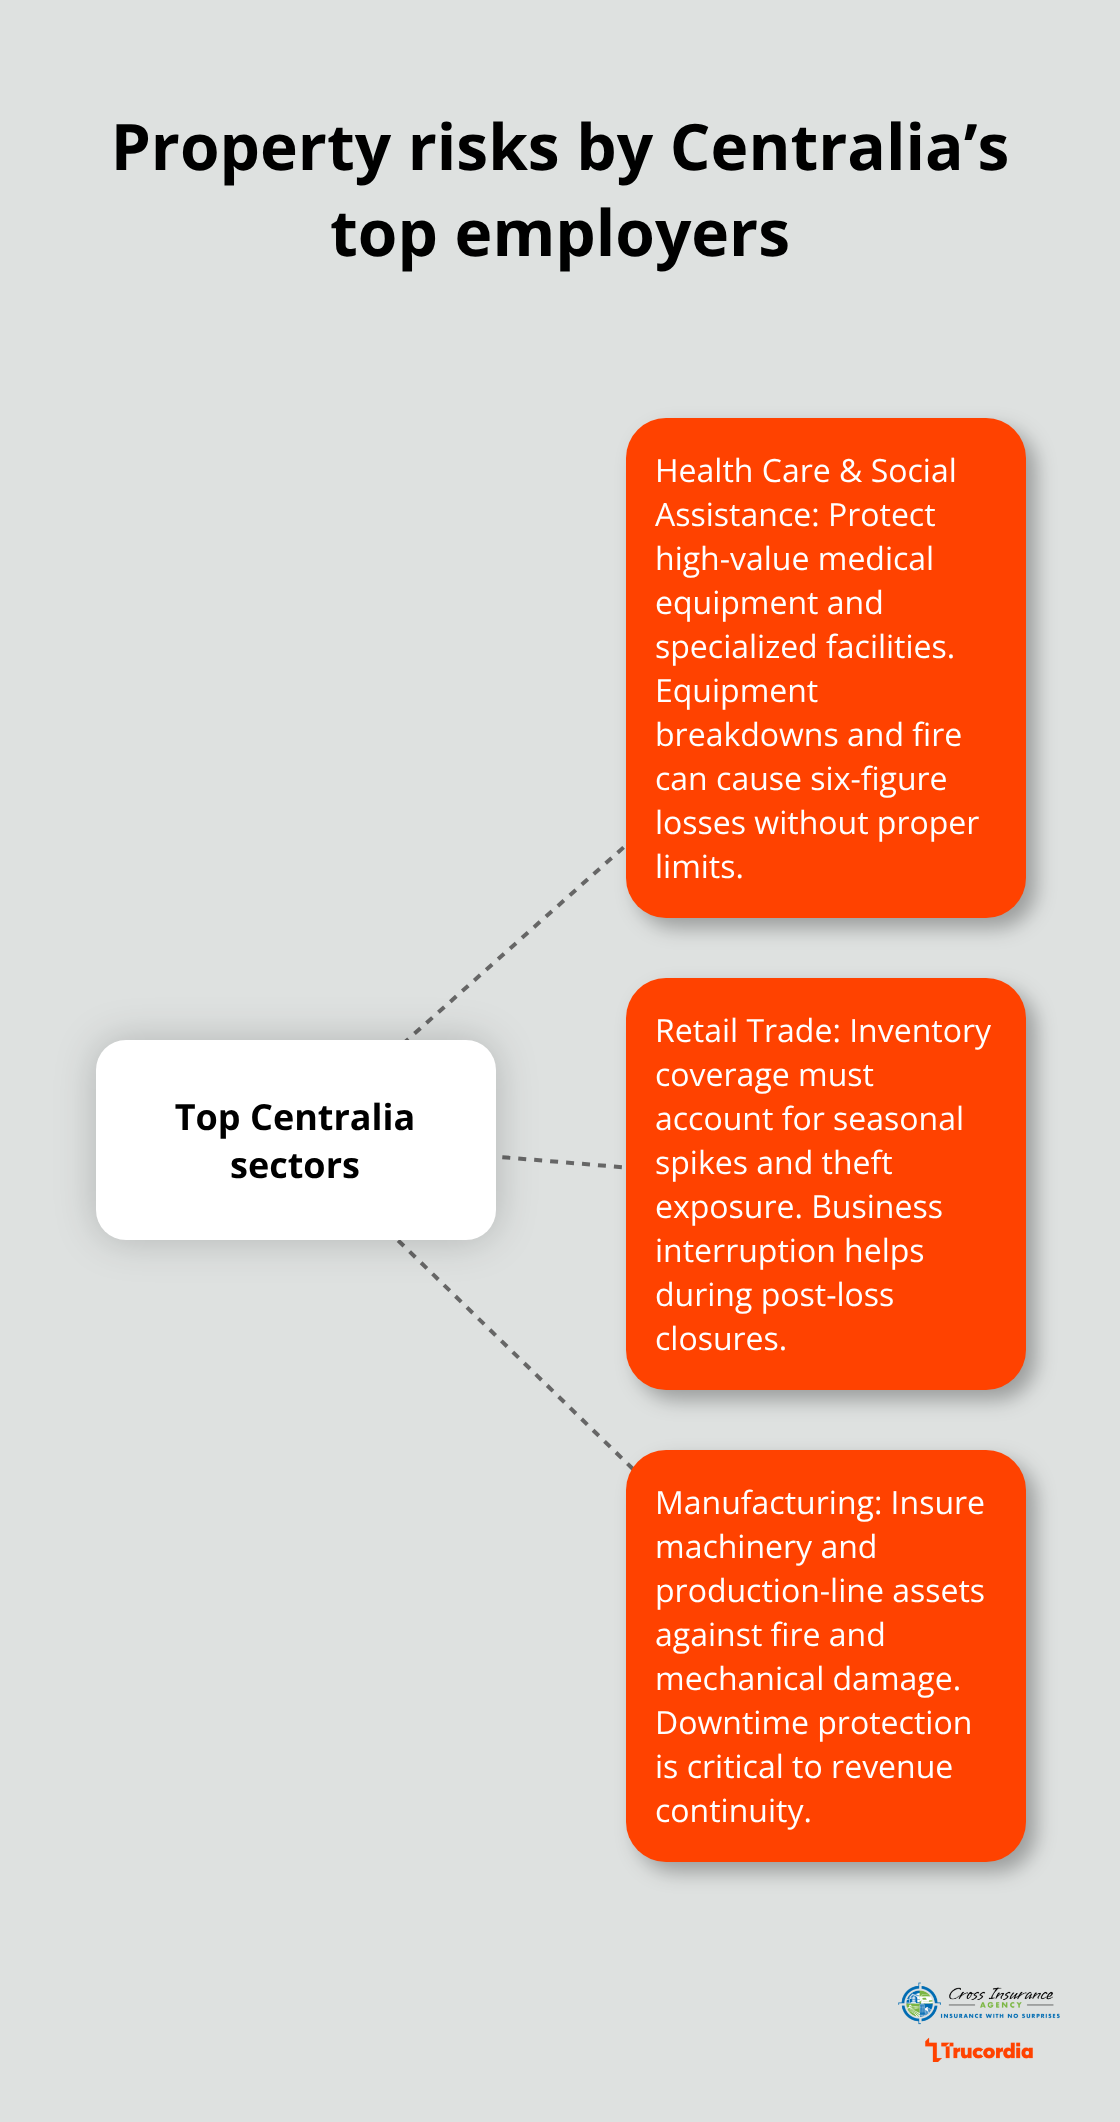
How leading Centralia sectors translate to distinct property insurance needs

A commercial property policy should include business interruption coverage that reimburses lost income when fire, theft, or weather damage forces you to close temporarily, which becomes critical during the 30 to 90 day repair periods that are common in Washington.

Scheduled Coverage Protects High-Value Assets

For high-value assets like jewelry collections, fine art, or expensive equipment, standard homeowners or commercial policies impose sublimits that cap coverage far below actual value-jewelry might be limited to $2,500 and cash to $5,000. Scheduled personal property endorsements remove these sublimits for specifically listed items, and insurers typically require appraisals or receipts for items valued above $5,000 to establish proof of value before a claim occurs. Centralia business owners with specialized equipment or inventory should request quotes that include agreed-value provisions, which lock in the replacement cost at policy inception and prevent disputes over value during claims.

Comparing Carriers Reveals Your Best Protection Match

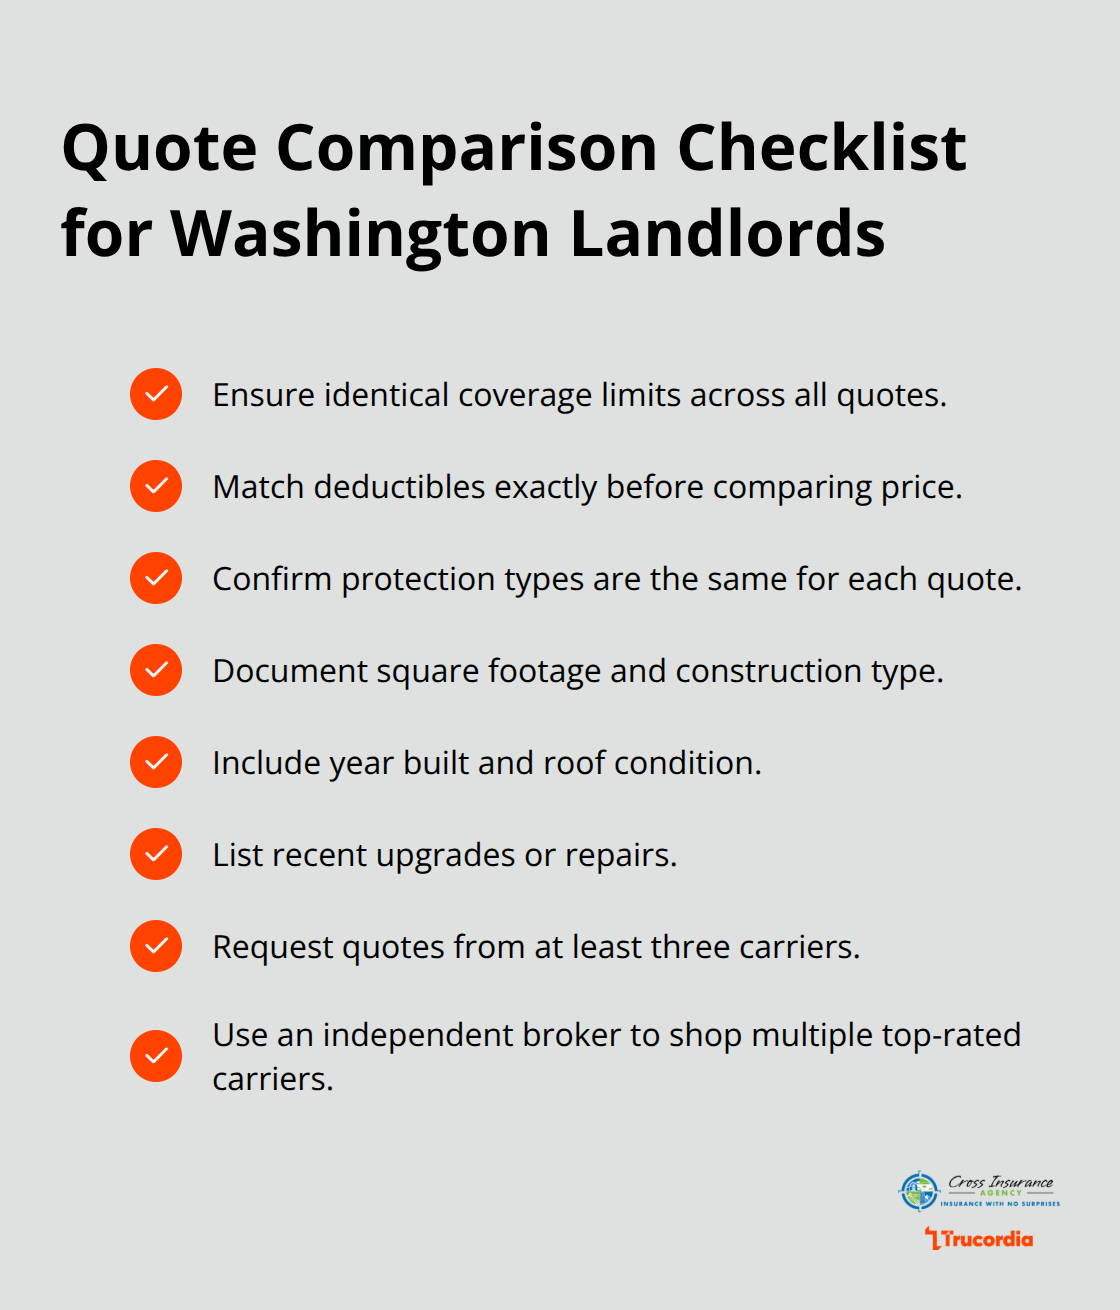
The independent agency model allows agents to compare these coverage variations across multiple top-rated carriers, ensuring you pay for protection that actually matches your assets rather than overpaying for unnecessary coverage or accepting dangerous gaps. When you request quotes from different carriers, you’ll notice that building coverage, contents limits, and business interruption options vary significantly-some insurers offer extended replacement cost up to 125% of your insured amount, while others cap it at 100%. You should document your property details (square footage, construction type, year built, roof condition, upgrades) because these factors directly affect pricing and coverage needs. Obtaining quotes from at least three carriers with identical coverage limits and deductibles reveals which insurers offer the best value for your specific situation.

The next section walks you through the process of selecting the right policy by assessing your actual coverage needs and understanding how deductibles and limits work together to protect your financial security.

How to Choose the Right Property Insurance Policy

Start with a Professional Replacement-Cost Appraisal

A professional replacement-cost appraisal for your Centralia home or business beats guessing at coverage needs. The median property value in Centralia reached $385,800 according to Data USA, yet market value and replacement cost diverge significantly-a home worth $385,000 on the market might cost $420,000 to rebuild after a total loss because construction labor and materials exceed what you’d receive selling the property. Contact local contractors or use the replacement-cost calculator from the National Association of Insurance Commissioners to document square footage, construction type, roof condition, and any recent upgrades. Many Centralia property owners insure their homes at 80% of replacement cost to save on premiums, but this strategy backfires through coinsurance penalties that force you to pay a percentage of claims yourself.

If your actual replacement cost is $400,000 and you insure it at only $300,000, the insurer calculates your loss reimbursement based on the shortfall-a $100,000 fire damage claim might result in you absorbing $25,000 out of pocket. For commercial properties, document building square footage separately from contents value, then request quotes that specify building coverage at full replacement cost and contents coverage based on your inventory turnover and seasonal fluctuations. Small manufacturers in Centralia with 3,361 jobs in the sector according to Data USA should photograph equipment and machinery to establish agreed values before a claim occurs, preventing disputes over replacement cost later.

Compare Quotes from Multiple Carriers with Identical Terms

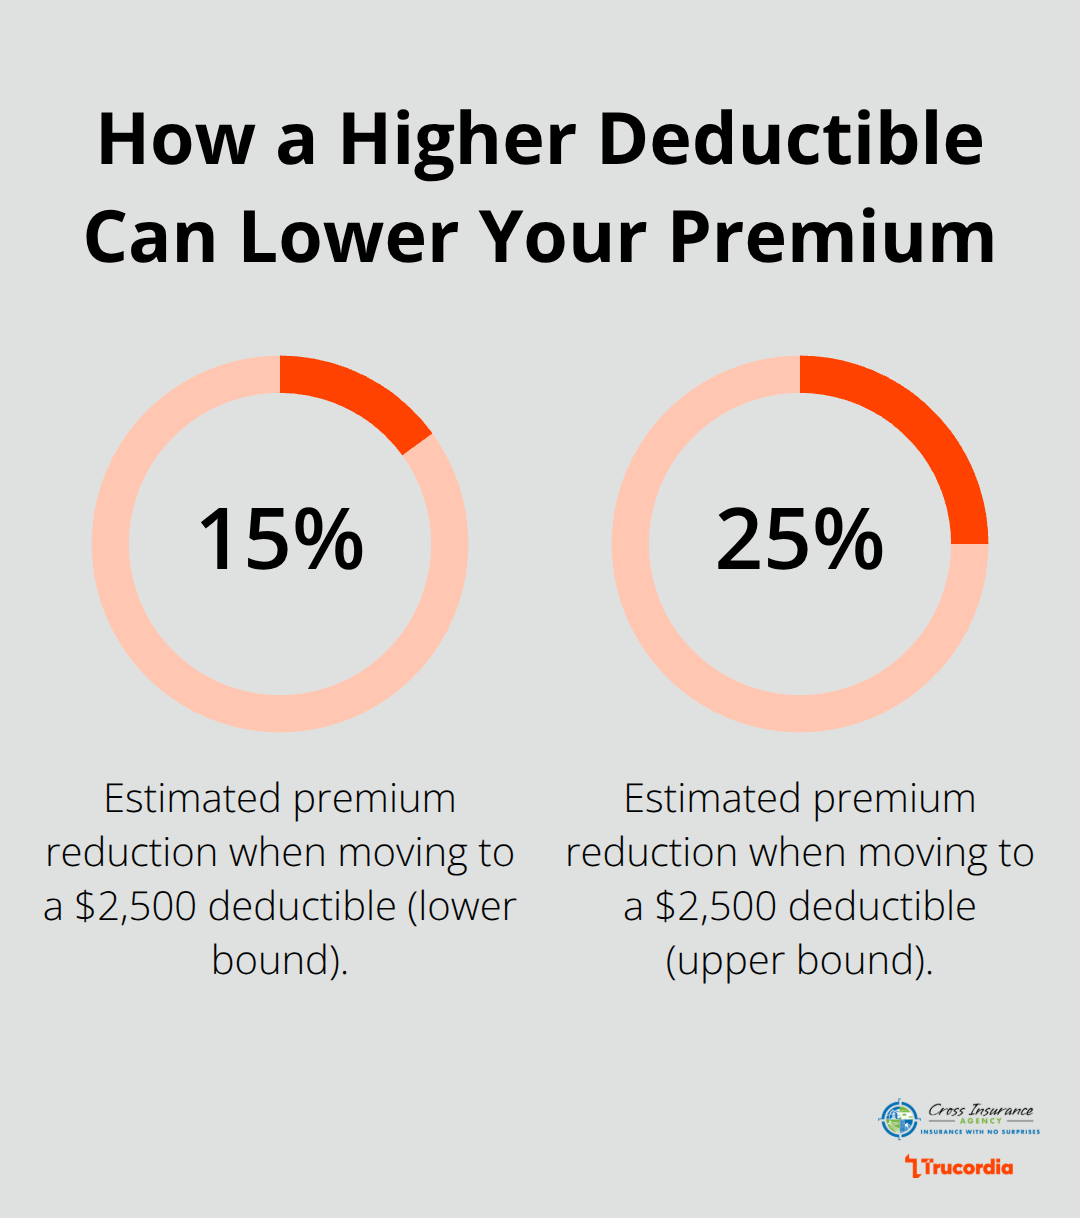
Quotes from at least three carriers with identical coverage limits, deductibles, and protection types reveal pricing differences that reflect actual carrier variation rather than coverage gaps. Request that each quote include standard homeowners or commercial property coverage plus optional protections like extended replacement cost up to 125%, business interruption coverage that extends beyond 30 days, and scheduled endorsements for high-value items. Deductibles typically range from $500 to $2,500 for homeowners policies and $1,000 to $5,000 for commercial properties-raising your deductible from $1,000 to $2,500 might save 15% to 25% annually, but only if you can absorb that amount from emergency savings without financial strain.
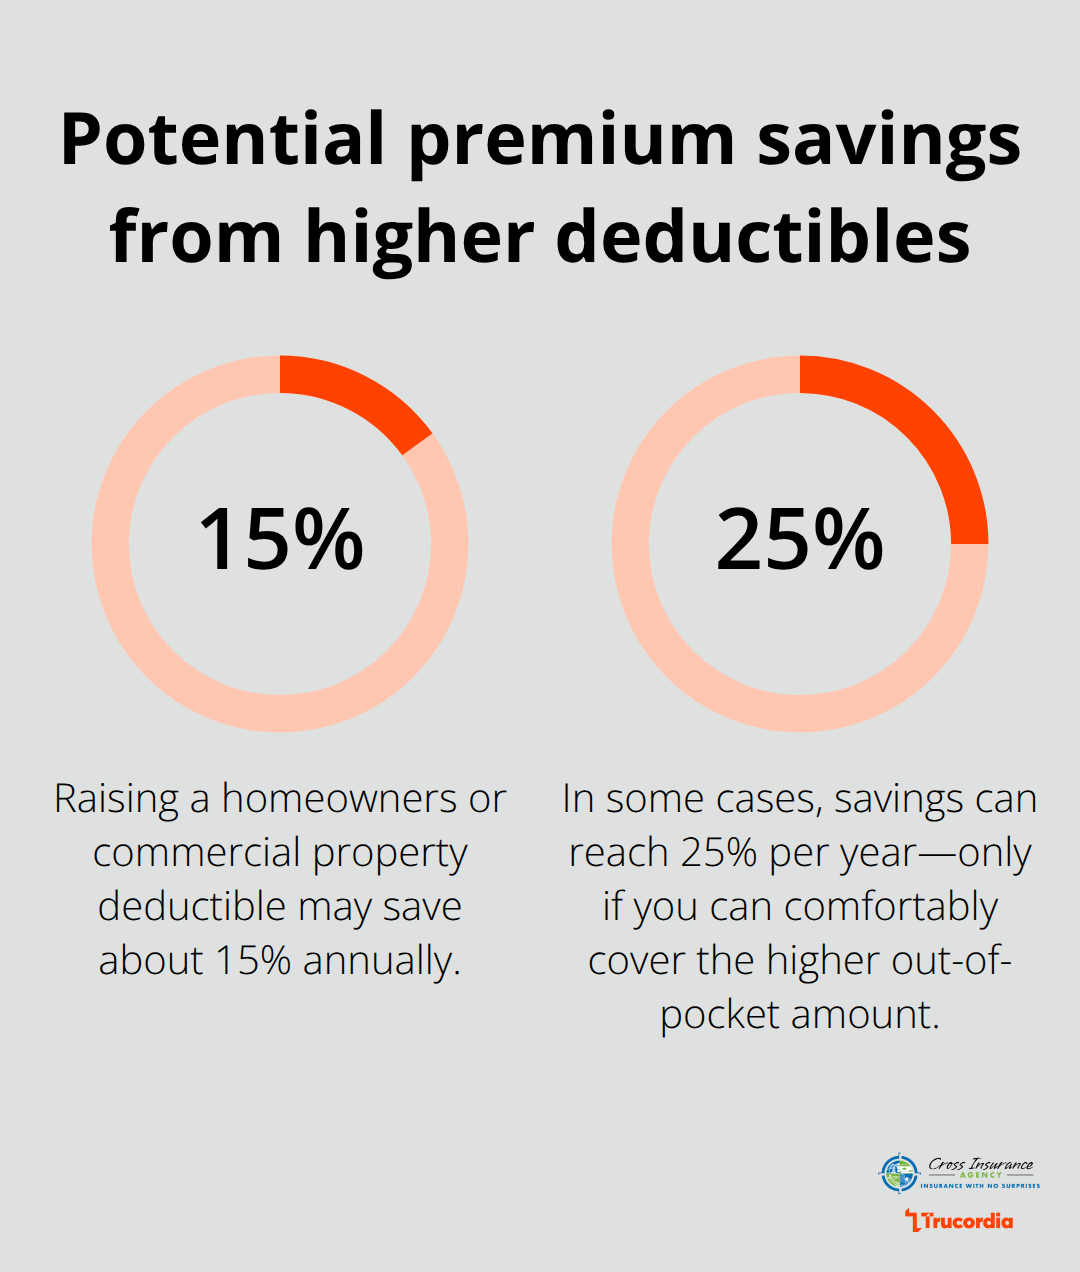
Estimated annual savings range when raising property insurance deductibles - property insurance Centralia WA

Washington landlords should demand loss-of-rent coverage that extends 60 days minimum since evictions in the state typically consume 30 to 90 days, and a two-month rent loss on a $2,000 monthly rental equals $4,000 in unprotected income. An independent agent who shops multiple top-rated carriers can identify bundling discounts that reduce overall premium costs when you combine auto, home, and business coverage with one carrier or across multiple insurers.

Evaluate Carrier Strength and Claims Performance

Financial strength ratings from A.M. Best or J.D. Power matter more than you might think-an inexpensive policy from a carrier with weak claims-handling reputation becomes worthless when you file a claim and face delays or denials. Review these ratings before finalizing your choice to confirm the insurer can actually pay claims when disaster strikes. Centralia residents benefit from working with independent agents who maintain relationships with top-rated carriers and can advocate for you during the claims process, ensuring faster resolution and fair treatment when you need it most.

Final Thoughts

Property insurance in Centralia, WA protects your financial future when fire, theft, weather, or liability strikes. You must obtain a professional replacement-cost appraisal to avoid coinsurance penalties, compare quotes from multiple carriers with identical coverage terms, and verify that your policy covers all protection gaps that standard homeowners or commercial policies typically miss. Centralia’s median property value of $385,800 and 75.8% homeownership rate mean most residents carry significant financial exposure, and underinsurance forces you to absorb losses out of pocket when claims occur.

Document your property details including square footage, construction type, roof condition, and any recent upgrades, then request quotes from at least three carriers. For homeowners, verify dwelling coverage sits at full replacement cost, not market value. For rental properties, demand loss-of-rent coverage extending 60 days minimum since Washington evictions typically consume 30 to 90 days, and for businesses, split building and contents coverage into separate protection buckets while including business interruption coverage that reimburses lost income during repairs.

Local expertise matters because Centralia property owners face specific risks that generic national policies often miss-an independent agent who understands Washington’s Residential Tenancy Act, local eviction timelines, seasonal weather patterns, and the unique exposures facing health care, retail, and manufacturing businesses identifies coverage gaps that cost you thousands during claims. At Cross Insurance Agency, we shop multiple top-rated carriers to deliver choice, bundling discounts, and personalized guidance tailored to your actual situation. Contact us today to secure property insurance Centralia WA that protects what matters most.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
One accident or lawsuit can wipe out years of financial progress. Most homeowners and car owners in Washington rely only on standard insurance policies, which cap out far too low when serious liability hits.

Family umbrella protection in WA fills those dangerous gaps. At Cross Insurance Agency, we help families build a real safety net that protects everything they’ve worked for.

How Umbrella Insurance Actually Works

The Basic Structure of Umbrella Coverage

Umbrella insurance sits above your existing auto and homeowners policies and activates only when those underlying policies hit their limits. If you cause a serious accident and the damages exceed what your car insurance covers, your umbrella policy picks up the remaining liability. Washington drivers typically carry auto liability limits between $25,000 and $100,000, which sounds adequate until you face a real lawsuit. A single at-fault collision that injures multiple people can easily generate $250,000 to $500,000 in medical bills, lost wages, and pain-and-suffering claims. Your standard policy maxes out far below that threshold, leaving you personally responsible for the gap.

Why the Cost Makes Sense

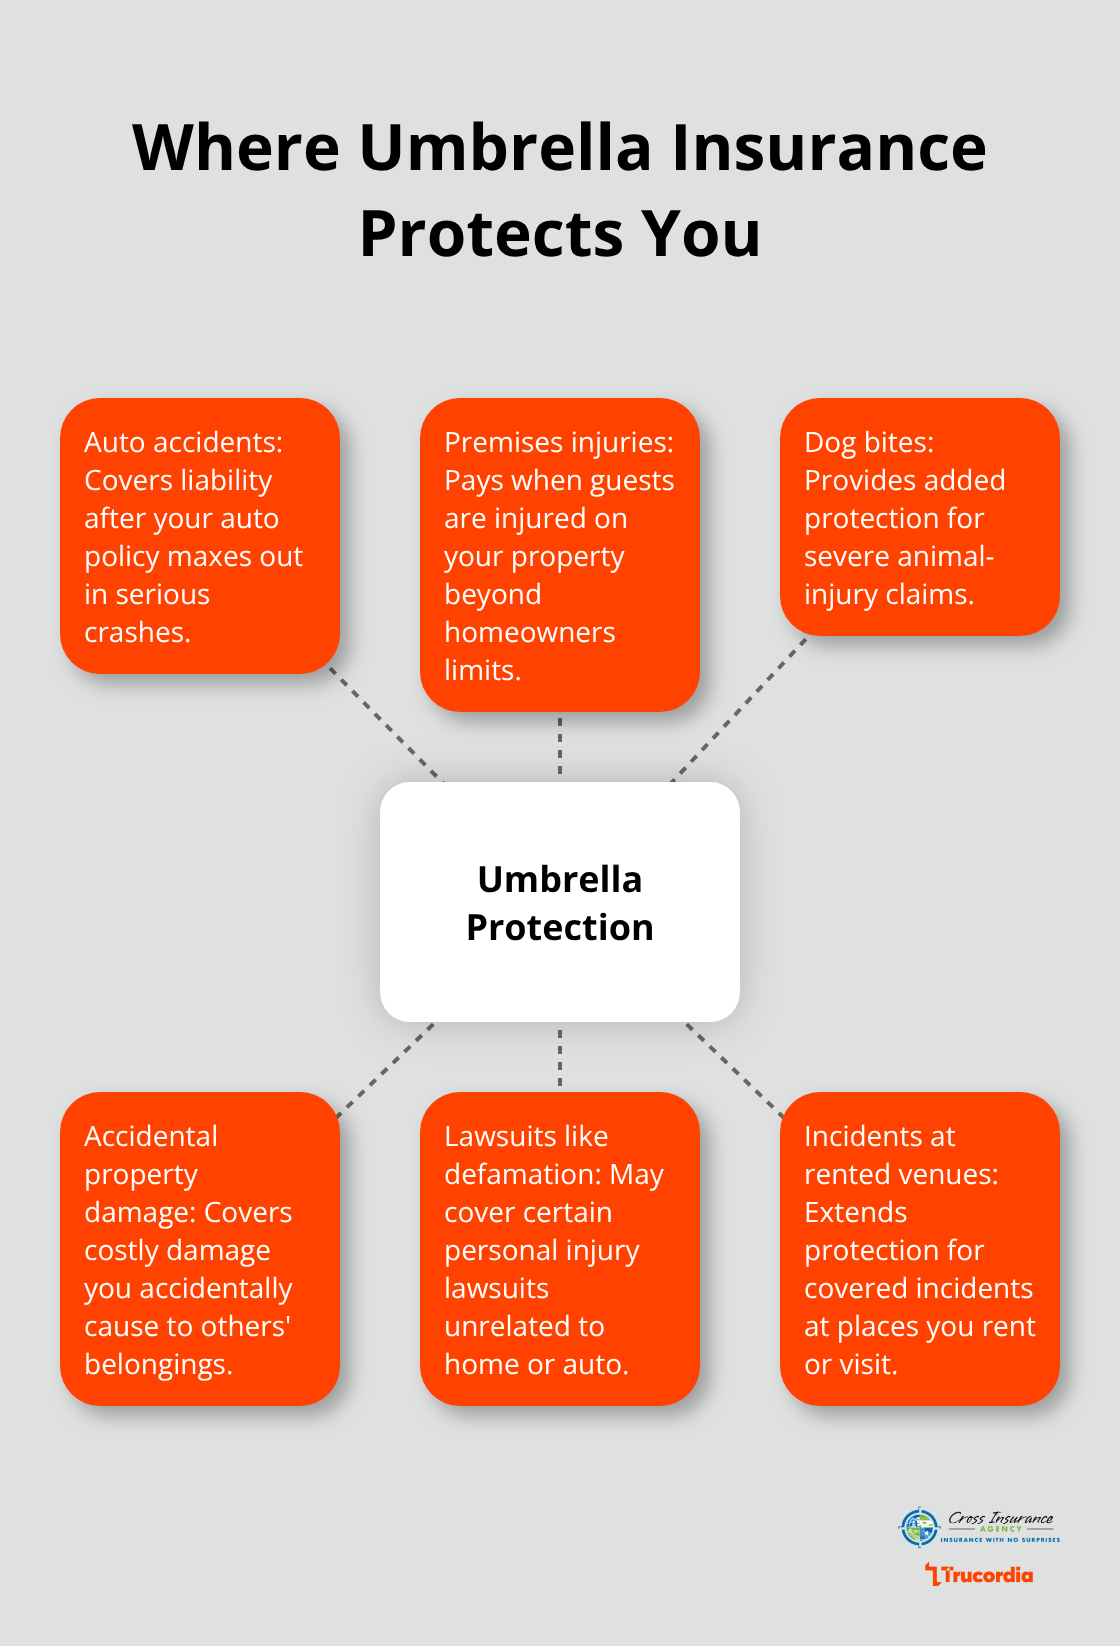
A $1 million umbrella policy costs between $150 and $300 annually for most homeowners, making it one of the cheapest forms of serious protection available. The coverage applies to liability situations across your life-car accidents, injuries on your property, dog bites, or accidental damage you cause to someone else’s belongings. It also protects you against certain lawsuits unrelated to your home or vehicle, though coverage details vary by policy.

Diagram showing key situations where umbrella insurance provides added liability protection - family umbrella protection WA

Real Liability Exposure Most People Miss

Most people underestimate their actual liability exposure because they assume worst-case scenarios won’t happen to them. Data shows that catastrophic liability claims regularly exceed $300,000. Washington residents who own rental properties, host frequent gatherings, or have teenage drivers face significantly higher risk profiles that standard policies simply cannot address.

Matching Coverage to Your Actual Risk

The solution is straightforward: assess what your auto and homeowners policies actually cover today, calculate your net worth and future earning potential, then purchase umbrella coverage that reflects the real financial damage a lawsuit could inflict. A $1 million umbrella policy protects most middle-class families adequately, though high-income earners or those with substantial assets often need $2 million or $3 million in coverage. The specific limit should match your situation, not some generic recommendation. Once you understand how umbrella insurance works, the next step involves identifying the specific scenarios where this protection matters most.

When Umbrella Coverage Actually Kicks In

A rear-end collision at a Seattle intersection sends a minivan into oncoming traffic, injuring four people across two vehicles. Medical bills exceed $600,000 within weeks. The at-fault driver’s auto policy maxes out at $100,000, leaving a $500,000 gap that umbrella insurance covers immediately. This scenario plays out regularly in Washington-not as a worst-case fantasy but as documented claims that destroy unprotected families financially. Without umbrella coverage, that driver faces wage garnishment for years, potential asset seizure, and bankruptcy that could have been prevented for roughly $200 annually.

The Serious Accident Reality

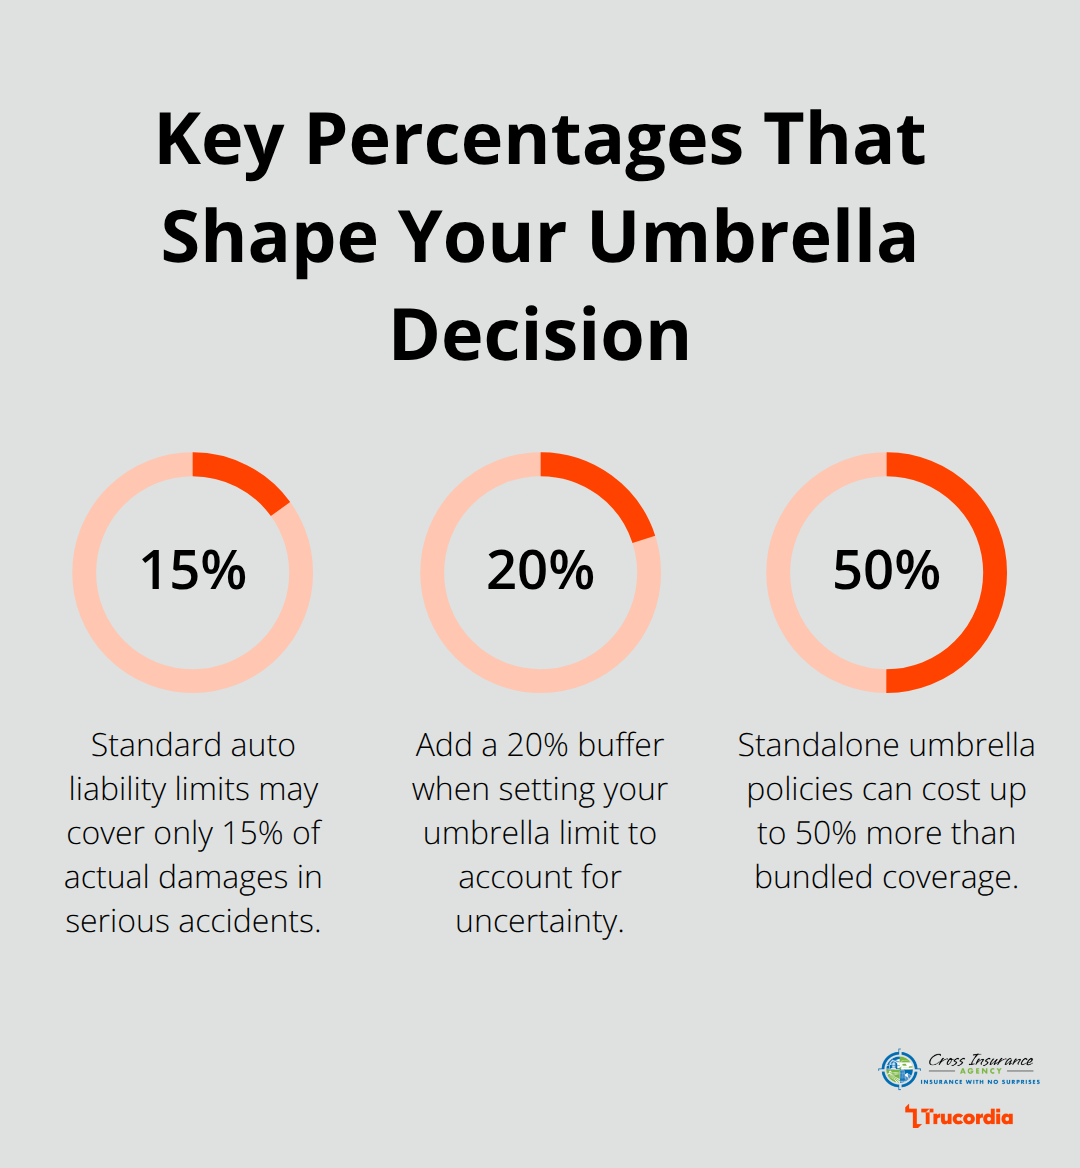
Car accidents generate the highest umbrella claims because liability exposure scales quickly with injury severity. A single collision involving multiple vehicles or pedestrians easily produces $250,000 to $750,000 in combined medical expenses, rehabilitation costs, and pain-and-suffering awards that juries regularly grant. Washington courts have awarded settlements exceeding $1 million in cases involving permanent disability or death. Standard auto liability limits between $25,000 and $100,000 cover maybe 15 percent of these actual damages. The umbrella policy then activates to cover the remainder, protecting your home, savings, and future income from creditors pursuing the judgment.

Percentage chart highlighting 15% coverage gap, 20% buffer, and up to 50% standalone cost increase

Property and Premises Liability Claims

Homeowner scenarios create equally expensive liability exposure that most people ignore until they face one. A guest slips on your icy driveway in January, breaks both legs, and misses eight months of work as a physical therapist earning $120,000 annually. Medical bills add another $85,000. The homeowners policy covers $300,000 in liability, which handles this incident, but what if a trampoline accident paralyzes a neighborhood child? What if your dog attacks a jogger? These incidents regularly generate $400,000 to $800,000 in settlements. A homeowners policy alone leaves you personally liable for amounts exceeding its limits. Your umbrella policy eliminates that personal exposure entirely, covering the full judgment amount up to your policy limit.

The Lawsuit Beyond Your Property

Umbrella coverage also protects against liability situations that don’t involve your home or vehicle directly. If you accidentally damage someone’s boat, cause injury at a rented venue, or face a defamation lawsuit, your umbrella policy often provides coverage where your standard policies create gaps. These situations happen less frequently than car or home accidents, but they generate surprisingly large claims when they do occur. A single incident costs $150,000 to $400,000 in legal defense and settlement costs alone. Having umbrella protection means these unexpected liabilities never force you to liquidate retirement accounts or sell assets to cover judgment amounts. The real question becomes how much coverage you actually need for your specific situation.

How Much Umbrella Coverage Do You Actually Need

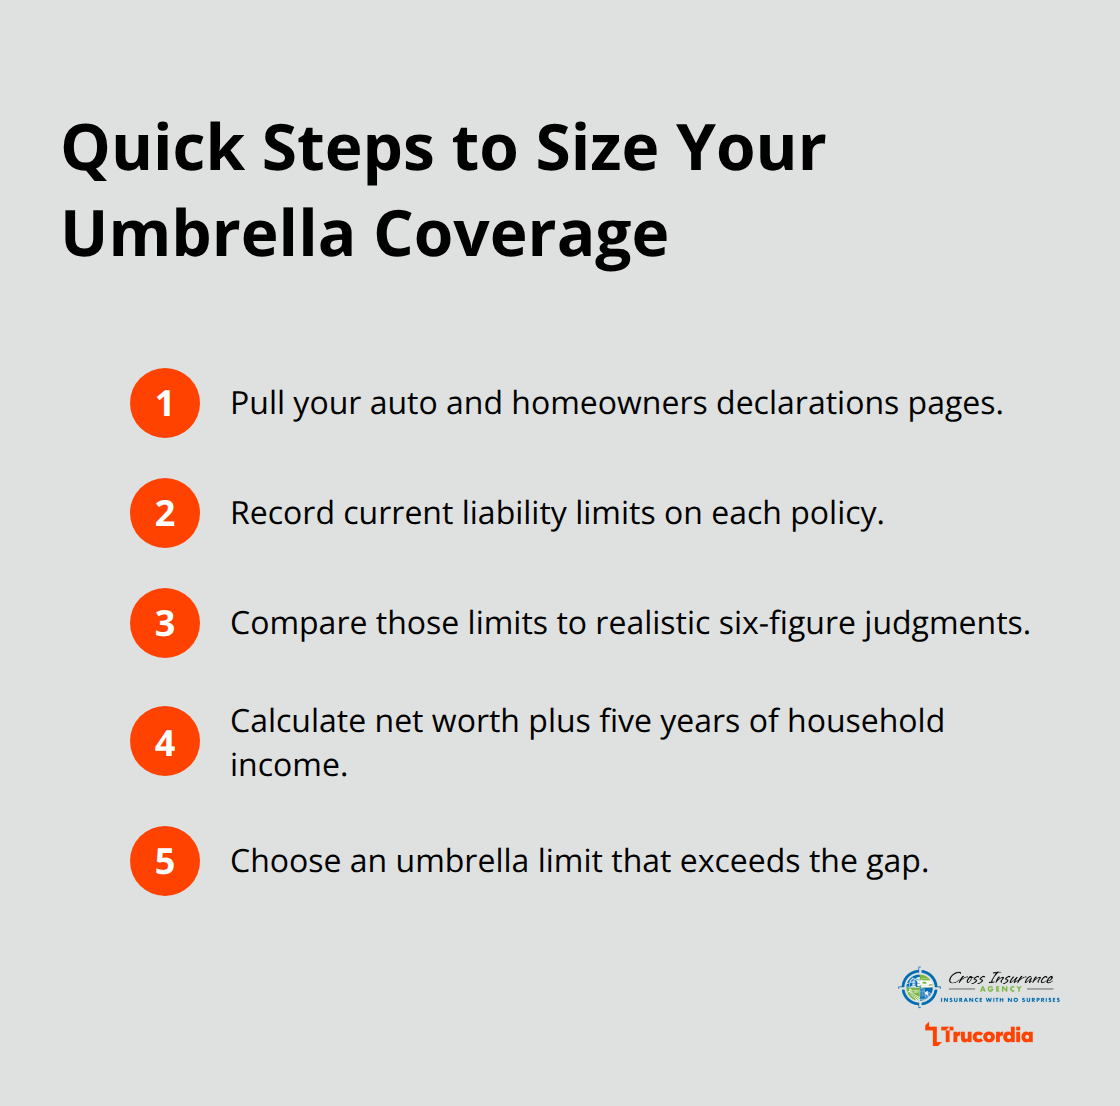
The gap between what your current policies cover and what a serious lawsuit could cost is precisely where umbrella insurance operates, but most Washington families guess at their coverage needs instead of calculating them. Start by pulling your auto and homeowners declarations pages and write down the liability limits on each policy. Most people discover their auto liability maxes out at $100,000 and their homeowners liability at $300,000, which sounds substantial until you face a $600,000 judgment. Your net worth and future earning potential matter far more than generic recommendations when you decide your umbrella limit.

Compact checklist of steps to determine your umbrella insurance limit - family umbrella protection WA

Calculate Your Coverage Based on Real Assets

A family with $400,000 in home equity, $150,000 in retirement savings, and two income earners should carry at least $1 million in umbrella coverage to protect those assets from creditors pursuing a judgment. High-income earners or those with rental properties need $2 million to $3 million in coverage because their earning potential and asset exposure run significantly higher. Washington residents earning over $200,000 annually face substantially greater lawsuit targets than those earning $60,000, so coverage should scale accordingly. Calculate your total net worth plus five years of household income to establish a realistic floor for your umbrella limit, then add 20 percent as a buffer. This approach beats relying on industry averages or whatever limit your neighbor carries.

Bundling Creates Real Savings That Multiply

Purchasing umbrella insurance through the same agent who handles your auto and homeowners policies generates immediate discounts that shopping separately never produces. Insurers reward bundling because they retain more of your premium dollars and reduce administrative costs, passing those savings to customers who consolidate coverage. A $1 million umbrella policy costs approximately $150 to $300 annually when bundled with existing auto and homeowners policies, but that same coverage often costs 30 to 50 percent more when purchased standalone. Bundling also simplifies claims handling because a single agent manages your entire coverage structure instead of coordinating between multiple carriers. Request quotes from at least three independent agents in Washington who represent multiple carriers, not captive agents who work for single insurers. The difference between a quote of $200 annually and $320 annually for identical $1 million coverage represents real money over ten or twenty years of ownership.

Understand Your Policy’s Activation Requirements

Your umbrella policy activates only after your underlying auto or homeowners policy exhausts its limit, meaning you must maintain those underlying policies with adequate limits to trigger umbrella protection. If you carry only $50,000 in auto liability but your umbrella policy requires a minimum underlying limit of $100,000 to activate, your umbrella coverage won’t protect you in that scenario. Most insurers in Washington require minimum underlying auto limits of $100,000 and homeowners limits of $300,000 before umbrella coverage applies. Intentional acts, criminal conduct, business activities, and certain contractual liabilities fall outside umbrella coverage entirely, which means you need separate policies for rental properties or business operations. Ask your agent specifically which situations your umbrella policy excludes before purchasing, because those exclusions matter more than the overall limit.

Final Thoughts

Family umbrella protection in WA stops being optional once you understand what a single lawsuit actually costs. Without it, years of financial discipline disappear in months when liability claims exceed your standard policy limits. With it, your family’s assets stay protected regardless of what accident or injury claim comes your way.

Start by pulling your auto and homeowners policy declarations and identifying your current liability limits, then calculate your total net worth plus five years of household income to determine how much umbrella coverage you actually need. Most Washington families find that $1 million provides adequate protection, though higher earners or those with substantial assets benefit from $2 million or $3 million limits. Contact an independent insurance agent who represents multiple carriers and can quote umbrella coverage bundled with your existing policies, since bundling cuts your umbrella premium by 30 to 50 percent compared to purchasing coverage separately.

A $1 million umbrella policy typically costs $150 to $300 annually when bundled, making it one of the cheapest forms of serious financial protection available. An independent agent shops multiple top-rated carriers, explains exactly which situations your umbrella policy covers and which it excludes, and ensures your underlying auto and homeowners limits meet the minimum requirements to activate umbrella protection. Contact Cross Insurance Agency to discuss your specific situation with a licensed agent who understands Washington liability risks and can deliver quotes from multiple carriers in one conversation.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Finding the right Olympia car insurance quotes takes time, but it doesn’t have to be complicated. We at Cross Insurance Agency work with drivers every day to match them with coverage that fits their needs and budget.

Local agents understand Washington’s specific requirements and can spot discounts you might miss online. Let’s walk through how to find the best rates and get the protection your vehicle deserves.

How Your Olympia Quote Gets Built

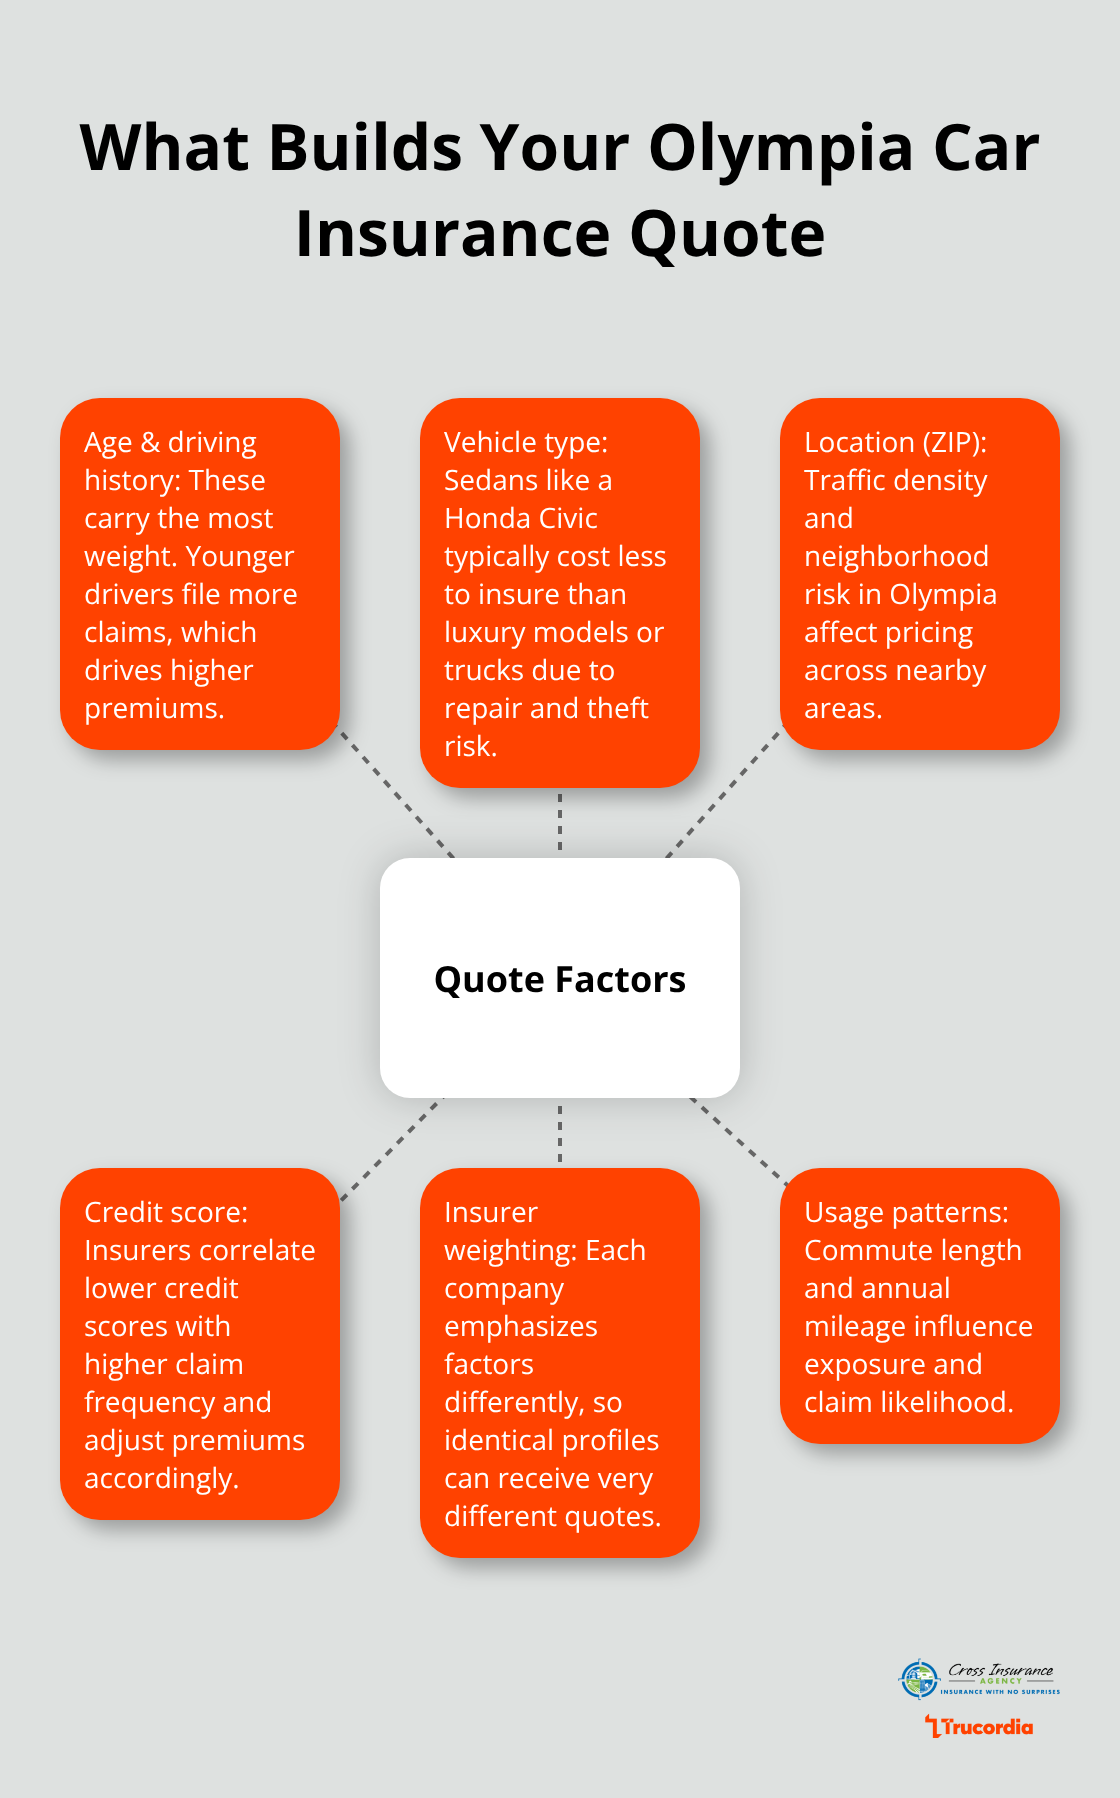
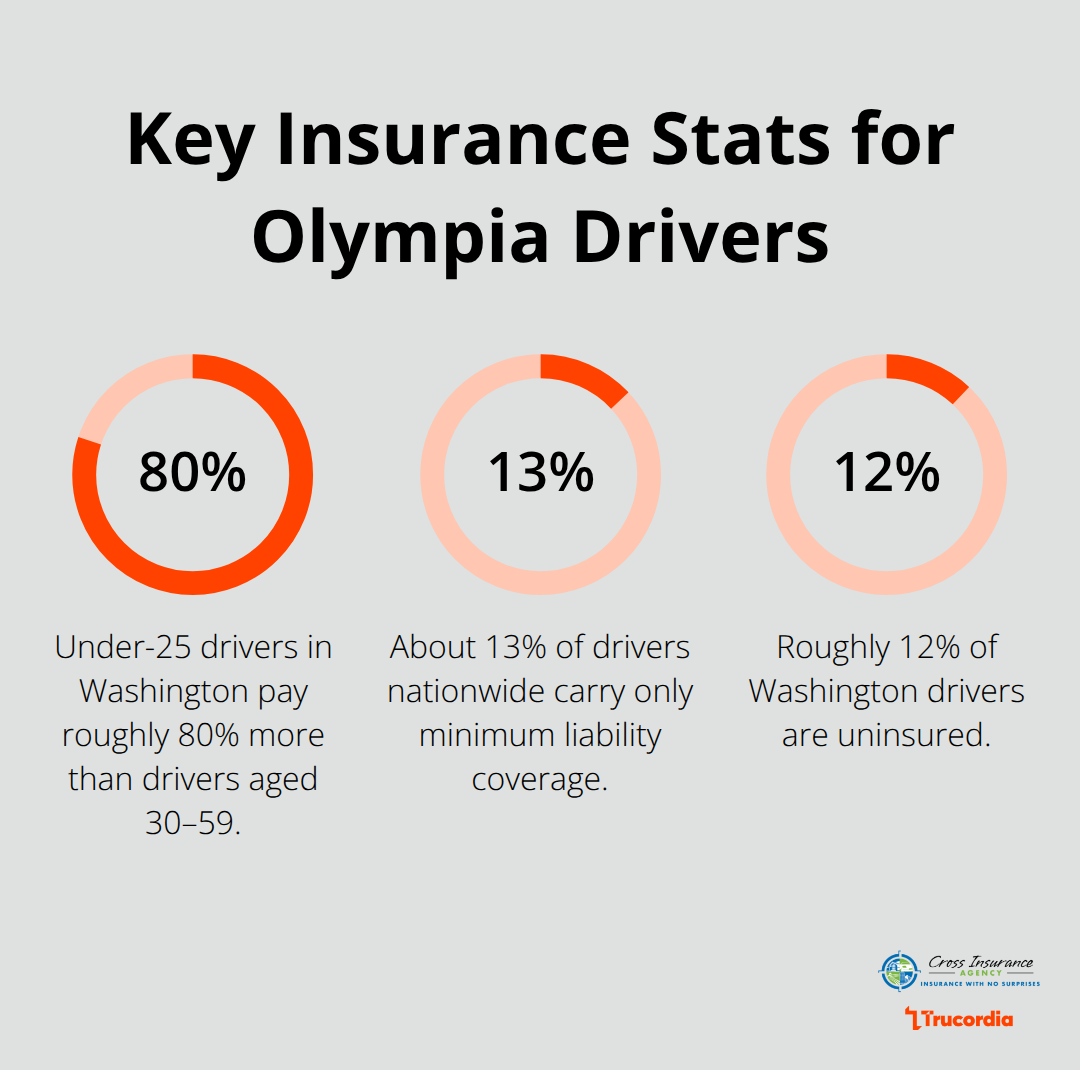
Insurance companies calculate quotes based on specific data points about you and your vehicle. Your age, driving history, and the type of car you drive carry the most weight. Washington state data shows that drivers under 25 pay roughly 80% more than drivers aged 30-59, simply because younger drivers file claims at higher rates.

Infographic showing main factors that determine Olympia car insurance quotes

Your zip code matters too-Olympia drivers in higher-traffic areas pay different rates than those in quieter neighborhoods. The type of vehicle you insure affects your premium significantly (a Honda Civic costs less to insure than a BMW or a truck). Credit score plays a role as well; insurers have found that drivers with lower credit scores file more claims, so they adjust premiums accordingly. When you request quotes, each insurer weights these factors differently, which is why you’ll see wildly different numbers from company to company.

Shopping Multiple Quotes Reveals Real Price Differences

Three to five quotes are non-negotiable if you want competitive rates. The National Association of Insurance Commissioners found that price variation between insurers for identical coverage can exceed 300% for the same driver. That means one company might charge $1,200 annually while another charges $4,000. When you compare quotes, look at the same coverage levels across all of them-liability limits, deductibles, and additional coverages must match or the comparison fails. Local agents have access to carriers that online-only platforms don’t represent, which often means better pricing for Olympia drivers. The time you spend comparing quotes directly translates to money in your pocket (sometimes hundreds of dollars annually).

Why Local Knowledge Changes Your Quote

A local agent knows Washington’s specific insurance landscape in ways national websites never will. They understand how Olympia’s weather patterns, road conditions, and traffic density influence risk assessment. They also know which carriers offer the best rates for your particular situation and which ones have strong claims support in your area. An agent identifies discounts you’d never find on your own-bundling your auto and home policies, safety features in your vehicle, or low-mileage discounts if you work from home. They advocate for you if you need to file a claim, rather than leaving you to navigate the process alone with a faceless corporation. National insurers processed over 26 million auto insurance claims in 2024, and having someone in your corner who knows the local claims process matters when things go wrong.

What Happens Next in Your Quote Journey

Once you understand how quotes work and why local agents matter, the next step involves looking at what coverage options actually exist in Washington state. Different policies protect different risks, and Olympia drivers need to know which types of coverage are required by law and which ones make sense for their situation.

Types of Coverage Available in Washington State

Washington state mandates liability coverage, which means you must carry it whether you want to or not. The state requires a minimum of $25,000 for bodily injury per person, $50,000 for bodily injury per accident, and $10,000 for property damage. These minimums are dangerously low. A serious accident involving multiple vehicles or injuries can easily exceed $50,000 in damages, leaving you personally liable for amounts far beyond your policy limits.

Why Minimum Liability Coverage Falls Short

Insurance Information Institute data shows that approximately 13% of drivers nationwide carry only minimum liability coverage, and many of them face financial devastation when accidents exceed those limits. A single lawsuit can target your wages and property for years. We recommend carrying at least $100,000 in bodily injury coverage and $50,000 in property damage, which costs only marginally more than minimums but protects your assets substantially better. Olympia drivers who own homes or have meaningful savings should try $250,000 or higher in liability limits.

Collision and Comprehensive: Protecting Your Vehicle

Collision and comprehensive coverage protects your vehicle itself, but these coverages are optional if your car is paid off. Collision covers damage from accidents with other vehicles or objects, while comprehensive covers theft, weather, vandalism, and animal strikes. If you financed or leased your vehicle, your lender requires both. For owned vehicles, the math is straightforward: if your car’s value is less than five times your annual deductible cost, skip these coverages. A 2015 Honda Civic worth $8,000 with a $500 deductible makes sense to insure; a 2005 vehicle worth $2,000 does not.

Additional Coverage Options for Olympia Drivers

Additional coverage options matter for Olympia drivers specifically. Uninsured motorist protection shields you if an uninsured driver causes an accident, and Washington state has roughly 12% uninsured drivers on the road. Medical payments coverage covers immediate medical expenses regardless of fault.

Percentage chart highlighting key auto insurance statistics relevant to Olympia and Washington state

Roadside assistance helps with towing and lockouts. Gap insurance protects financed vehicles if they’re totaled and you still owe money to the lender. Rental reimbursement covers car rental costs while yours is being repaired (most Olympia drivers benefit from uninsured motorist coverage and medical payments, which add minimal cost but address real risks in Washington’s driving environment).

Now that you understand what coverage options exist and which ones make sense for your situation, the next step involves learning how to actually lower your rates through discounts and smart policy decisions.

Lower Your Olympia Car Insurance Costs

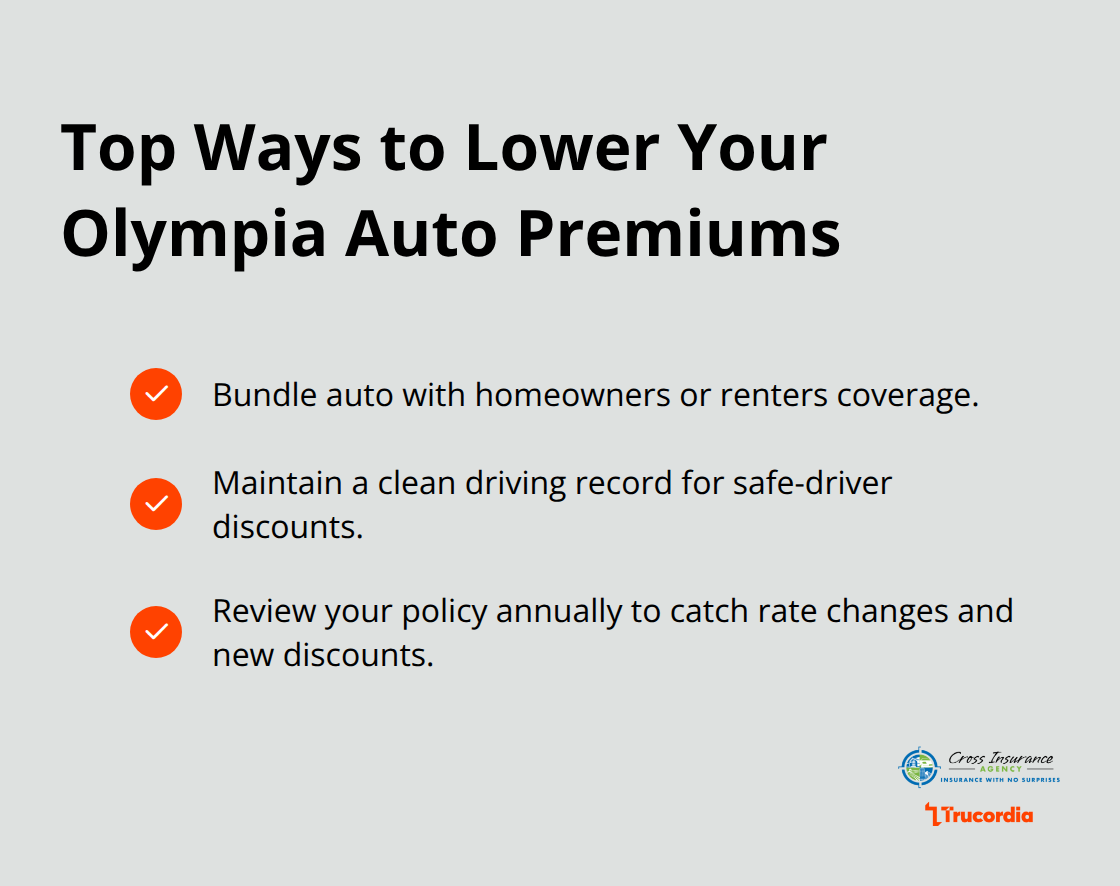
Lowering your insurance costs requires action, not patience. The difference between a passive driver who accepts the first quote and an active one who pursues discounts can easily reach $500 to $1,000 annually. We see this gap repeatedly when we review policies that have been sitting unchanged for years. The three most effective ways to reduce your premiums involve combining policies strategically, maintaining a clean driving record, and conducting regular policy reviews that actually catch rate changes and new discounts.

Checklist of actions to reduce Olympia car insurance costs - Olympia car insurance quotes

Bundle Your Policies for Significant Savings

Combining your auto insurance with homeowners or renters coverage typically saves 5% to 25% on your auto policy alone, according to the Insurance Information Institute. If you carry a mortgage, you already have homeowners insurance, which means bundling is available immediately. The math is simple: a driver paying $1,200 annually for auto coverage saves $60 to $300 just by combining policies with the same insurer. Some carriers offer even steeper discounts for bundling three or more policies together.

The catch is that bundling only works if the combined rate is genuinely lower than shopping each policy separately, so compare the bundled quote against standalone quotes before committing. A local agent can show you exactly what bundling saves versus what you’d pay elsewhere, eliminating the guesswork.

Maintain a Clean Driving Record

Your driving record directly impacts your rates, and this is where most Olympia drivers miss opportunities. A single accident or traffic violation can increase your premium by 20% to 40% for three to five years, according to the Insurance Institute for Highway Safety. Conversely, maintaining a clean record for three consecutive years often qualifies you for a safe driver discount worth 10% or more.

If you received a ticket years ago, ask your agent when it stops affecting your rates-violations typically drop off after three years in Washington state, but some carriers maintain longer lookback periods. Defensive driving courses can also reduce your premium by 5% to 10%, and many courses qualify you for the discount immediately after completion.

Review Your Coverage Annually

Reviewing your coverage annually prevents you from overpaying for protection you don’t need or underinsuring against real risks. Rate changes happen constantly-carriers adjust their pricing models, new discounts emerge, and your personal circumstances shift. The average driver who reviews their policy annually saves between $200 and $400 compared to those who never revisit their coverage, according to consumer research from the Consumer Federation of America.

During your review, confirm that your vehicle’s value has changed (older cars depreciate, which might mean dropping collision coverage), check if you’ve qualified for new discounts based on job changes or home improvements, and verify that your coverage limits still match your assets. Annual reviews take thirty minutes and often uncover rate reductions that your current insurer doesn’t advertise automatically.

Final Thoughts

Local agents who understand Olympia deliver better Olympia car insurance quotes than online platforms ever will. We at Cross Insurance Agency shop multiple carriers simultaneously, comparing rates and discounts across options you’d never find on your own. That 300% price variation between insurers disappears when someone advocates for your specific situation instead of leaving you to navigate the process alone.

Your next step is straightforward: contact Cross Insurance Agency to request quotes from multiple carriers. Bring your current policy if you have one, your vehicle information, and your driving history, and our licensed agents will walk you through your coverage options and show you exactly what bundling, discounts, and policy adjustments can save. The conversation takes less time than you’d spend comparing quotes online, and you’ll walk away with actual numbers instead of estimates.

Choosing a trusted insurance partner means selecting someone who prioritizes your protection over commission and understands Olympia’s specific risks. Your vehicle deserves coverage that fits your life, and you deserve an agent who makes that happen without the runaround.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Olympia sits in one of the wettest regions in the country, and flooding poses a real threat to homeowners here. Standard homeowners insurance won’t cover water damage from floods, leaving many properties vulnerable.

At Cross Insurance Agency, we help Olympia residents understand their flood insurance options and find coverage that actually protects their investment. This guide walks you through everything you need to know about flood insurance in Olympia, WA.

Why Flood Risk Is Real in Olympia

Olympia’s Geography Creates Unavoidable Flood Threats

Olympia’s location makes flooding inevitable rather than unlikely. The city sits in the Puget Sound region where heavy rainfall, snowmelt, and proximity to water bodies create perfect conditions for water damage. According to the National Oceanic and Atmospheric Administration, the Pacific Northwest receives an average of 50 to 80 inches of precipitation annually, with some areas exceeding 100 inches. Thurston County, where Olympia is located, experiences significant flood events roughly every 10 to 15 years.

The Deschutes River, which runs through the area, has flooded neighborhoods multiple times in the past two decades. Properties within the 100-year floodplain face a 26% chance of experiencing a flood during a 30-year mortgage period, according to FEMA data. Even homes outside designated flood zones can suffer water damage from localized flooding, stormwater backup, or overwhelmed drainage systems.

Standard Homeowners Insurance Leaves You Exposed

Most homeowners make a critical mistake when they assume their standard policy covers flood damage. Standard homeowners insurance policies explicitly exclude flood damage, treating it as a separate peril that requires dedicated coverage. The Insurance Information Institute reports that the average homeowners insurance claim for water damage costs around $11,000, but flood damage claims can be substantial.

In 2023, the National Flood Insurance Program paid out over $3.2 billion in claims nationwide, yet many policyholders remained underinsured or uninsured. If water enters your home through a broken pipe or roof leak, your homeowners policy covers it. If floodwater from rising rivers or heavy rain penetration damages your property, you’re on your own. This gap leaves Olympia homeowners exposed to substantial financial risk.

Your current homeowners policy likely contains specific language that excludes water damage from external sources (like rivers, storms, or drainage failures). Understanding this distinction between covered water damage and excluded flood damage matters when you face actual loss. The financial consequences of this gap can devastate your finances without proper flood insurance in place.

Your Flood Insurance Choices in Washington

The National Flood Insurance Program Remains Your Baseline Option

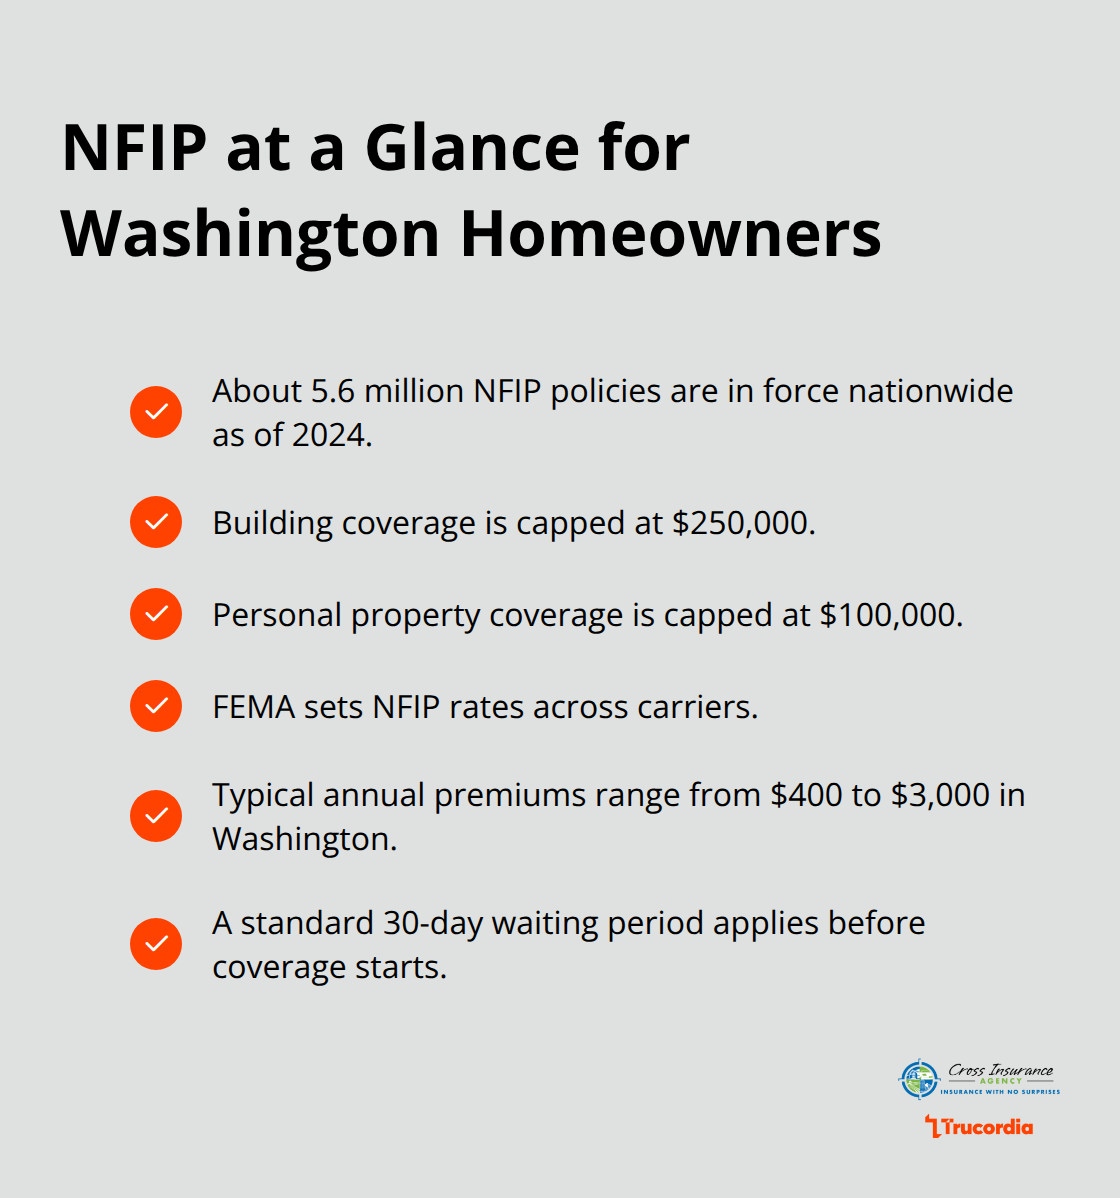
The National Flood Insurance Program (NFIP) covers approximately 5.6 million policies nationwide as of 2024, making it the dominant flood coverage option in Washington. NFIP policies cap building coverage at $250,000 and personal property coverage at $100,000-a significant limitation if your Olympia home exceeds these thresholds. The Federal Emergency Management Agency sets NFIP rates, so you’ll find consistent pricing across carriers rather than competitive bidding. Premiums typically range from $400 to $3,000 annually for standard-risk properties in Washington, calculated based on your flood zone designation and your home’s elevation relative to the base flood elevation.

Key NFIP coverage limits, pricing, and timing facts for Washington - flood insurance Olympia WA

One critical advantage of NFIP: the program includes a 30-day waiting period before coverage takes effect. This timing matters significantly when you anticipate seasonal flooding, so you should apply well before heavy rain seasons arrive. Understanding how insurance works provides a solid foundation before exploring alternatives, since it often delivers the most affordable baseline coverage for moderate-risk properties.

Private Flood Insurance Offers Competitive Alternatives

Private flood insurance has expanded substantially in Washington over the past five years, offering higher coverage limits and potentially better rates for properties outside high-risk zones. Companies like AquaVest and Kin now write flood policies in Washington, sometimes undercutting NFIP premiums by 20 to 40 percent for low-to-moderate risk properties. However, private policies vary dramatically in coverage scope and exclusions, so direct comparison matters before you purchase.

Properties in designated high-risk zones (A or V zones) cannot purchase private flood insurance in most cases and must use NFIP instead. For Olympia properties outside high-risk zones, private policies can offer superior coverage options, including replacement cost coverage instead of actual cash value and higher deductible choices that lower premiums. These alternatives provide flexibility that NFIP cannot match for many homeowners.

Identifying Your Flood Zone Determines Your Options

Visit FEMA’s Flood Map Service Center online and enter your address to identify your property’s flood zone classification. The map shows whether you’re in the high-risk 100-year floodplain, moderate-risk 500-year zone, or lower-risk area. Your flood zone designation directly controls which insurance products you can purchase and what rates you’ll pay.

High-risk zone properties face mandatory flood insurance requirements if you carry a federally-backed mortgage, while moderate and low-risk properties have more flexibility in their coverage decisions. Understanding your specific zone classification helps you compare NFIP and private options accurately. Once you know your flood zone, you can assess whether private carriers offer better value than NFIP for your particular situation, then move forward with securing the coverage that protects your Olympia investment.

Getting Your Flood Insurance in Place

Confirm Your Flood Zone and Coverage Requirements

Visit FEMA’s Flood Map Service Center and enter your Olympia address to confirm your exact flood zone classification. Contact your mortgage lender to ask whether flood insurance is mandatory for your loan-if you’re in a high-risk zone with a federally-backed mortgage, it is required. Gather your home’s key details: square footage, year built, elevation relative to base flood elevation if available, and replacement cost estimate. This information directly affects your premium quotes and helps carriers assess your actual risk profile.

Identify Which Carriers You Can Purchase From

If you’re in a high-risk A or V zone, NFIP becomes your only option. Request quotes from at least two NFIP-authorized carriers like State Farm or Allstate to compare their specific rates and service reputation. For properties outside high-risk zones, obtain NFIP quotes alongside private carrier options like AquaVest or Kin. Request quotes with identical coverage limits and deductible amounts so you’re comparing apples to apples-don’t let carriers quote you different protection levels that skew the price comparison.

Compare Coverage Limits and Policy Terms

NFIP policies cap building coverage at $250,000 and personal property at $100,000, which may leave substantial gaps if your Olympia home’s replacement cost exceeds those limits. Private policies sometimes offer replacement cost coverage instead of actual cash value, meaning you receive full repair costs without depreciation deductions. Check deductible options carefully: NFIP offers standard $1,000 deductibles but also allows $2,500, $5,000, and $10,000 options that lower premiums significantly if you can absorb higher out-of-pocket costs in a flood event. Private carriers often provide more deductible flexibility than NFIP.

Account for Waiting Periods and Seasonal Timing

Review waiting periods in your policy documents-NFIP’s standard 30-day waiting period means you need to apply well before seasonal heavy rains arrive. Don’t delay this decision into October or November when Olympia’s rainy season intensifies and flood risk peaks. The 30-day clock starts when your application is approved, so early action protects you when weather conditions matter most. Examine the actual policy language instead of just the premium numbers to understand what protection you actually receive.

Make Your Final Selection Based on Actual Protection

Select the policy that protects your home’s value, not just the quote that looks cheapest on paper. A lower premium that leaves your home underinsured creates false economy when a flood event occurs. Your coverage choice determines whether you can rebuild after water damage or face financial hardship. Take time to review all policy terms, coverage limits, and deductible options before you commit to a carrier.

Final Thoughts

Olympia’s flood risk demands action, not wishful thinking. The city’s geography, annual precipitation exceeding 50 inches, and proximity to the Deschutes River create genuine threats to your home and finances. Properties in the 100-year floodplain face a 26% chance of flooding during a 30-year mortgage, yet standard homeowners insurance won’t cover that damage-this gap costs homeowners thousands of dollars every year.

Flood insurance in Olympia WA protects your financial security when water damage strikes. The National Flood Insurance Program remains accessible for most properties, while private carriers offer competitive alternatives for homes outside high-risk zones. Waiting until November or December to apply means facing NFIP’s 30-day waiting period during peak flood season, leaving you exposed when you need protection most.

Contact Cross Insurance Agency to discuss your flood insurance options and secure the protection your Olympia home needs. Our licensed agents shop multiple carriers to deliver choice and personalized guidance tailored to your specific property and risk profile. Visit FEMA’s Flood Map Service Center to confirm your flood zone, then reach out to us so we can help you find coverage that actually protects your investment.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Condo insurance in Olympia, WA protects your investment, but many owners don’t realize their policies have significant gaps. Your condo association’s master policy covers the building structure, but it leaves your personal belongings, liability exposure, and unit improvements unprotected.

At Cross Insurance Agency, we’ve seen too many Olympia condo owners discover coverage shortfalls only after a claim. This guide walks you through what your policy should cover and how to spot weaknesses before they cost you money.

What Your Condo Policy Actually Covers

Olympia’s condo market includes roughly 8,000 registered condominiums, according to Thurston County assessor data, and nearly all operate under a master insurance policy paid through association dues. That master policy covers the building’s structural elements-the roof, walls, common areas, and the bones of your unit itself. Your association’s policy does not cover your interior walls, flooring, cabinetry, appliances, furniture, or anything else inside your four walls. Most owners make their first mistake here: they assume the association’s coverage protects their personal investment when it absolutely does not. The master policy also carries liability coverage for common areas, but it stops at your unit’s threshold. If someone slips in a hallway, the association’s liability pays. If someone trips on your bathroom tile, your personal liability policy pays, and you need one.

Hub-and-spoke chart showing what the condo association’s master policy covers versus what an HO6 policy must cover for Olympia, WA owners.

Your HO6 Policy Fills the Actual Gaps

You need an HO6 condo owner’s policy to cover everything the master policy leaves exposed. This policy protects your personal property, your unit’s interior improvements, and your personal liability. If you’ve upgraded your kitchen, replaced flooring, or added built-in shelving, those improvements belong to you and require coverage under your individual policy. Water damage from a neighbor’s burst pipe ranks among the most common claims in Olympia condos, especially in older buildings along the Capitol Lake waterfront. Your HO6 policy covers damage to your belongings and interior from water originating outside your unit, but only if you carry the right coverage limits.

Coverage Limits That Actually Match Your Building

Many owners carry inadequate limits-$100,000 or less-when Olympia’s average condo replacement cost runs $250,000 to $400,000 for mid-range units. Your association likely requires minimum coverage of at least $50,000, but that’s a floor, not a ceiling. You should also carry loss assessment coverage, which protects you if the association bills owners for uninsured losses or deductible costs from a major claim. This protection matters most when a single incident (a roof collapse or major fire) affects multiple units and exhausts the association’s deductible.

What Happens When the Master Policy Falls Short

Water intrusion, structural failures, and liability disputes between neighbors create situations where the master policy’s limits and your individual coverage must work together. Your personal policy steps in where the association’s coverage ends, but only if you’ve structured your limits correctly. This is where most Olympia condo owners face real financial exposure-not from what they know about, but from what they’ve overlooked.

Coverage Gaps That Cost Olympia Condo Owners Real Money

Liability Limits That Fall Short of Real Disputes

Most Olympia condo owners underestimate their liability exposure because they confuse the association’s common-area liability coverage with their own personal liability protection. Your HO6 policy typically carries $100,000 to $300,000 in personal liability coverage, but disputes between neighbors over water damage, structural defects, or shared wall problems routinely exceed these limits. When a neighbor’s water damage claim reaches $150,000 and your policy maxes out at $100,000, you personally owe the difference. Thurston County property values have climbed steadily, and liability awards have followed. A $300,000 liability limit costs only slightly more in annual premiums than $100,000, yet provides genuine protection for your actual financial exposure.

Structural Improvements You Thought Were Covered

Owners often assume that kitchen renovations, bathroom upgrades, flooring replacements, or added closet systems fall under the master policy because they’re physically attached to the unit. They don’t. Your HO6 policy must explicitly cover these improvements, and your coverage limit should reflect their actual replacement cost. An upgraded kitchen alone runs $15,000 to $30,000 in Olympia’s current market. Without adequate coverage limits for improvements, you absorb that loss yourself.

Compact ordered list highlighting common insurance gaps and dollar amounts for Olympia, WA condo owners. - condo insurance Olympia WA

The association’s master policy protects only the building’s structural shell-not the investments you’ve made inside your four walls.

Water Damage Caps That Leave You Exposed

Water damage from neighbors creates the most common claim gap, particularly in older Olympia buildings constructed before modern waterproofing standards. Your HO6 covers belongings damaged by water originating outside your unit, but only if you carry water backup coverage or agreed-upon water damage limits. Many standard policies exclude water damage entirely or cap it at $5,000. A single incident involving a failed pipe in the unit above can saturate flooring, drywall, cabinetry, and personal property worth far more than that cap. Olympia’s climate brings consistent moisture exposure, making this coverage non-negotiable rather than optional.

How These Gaps Interact in Real Claims

When multiple coverage gaps overlap-inadequate liability limits, unprotected improvements, and water damage exclusions-a single incident can create financial exposure that extends well beyond your policy’s protection. The association’s master policy covers the building structure, but your personal policy must stand alone for everything inside your unit. This separation means you carry the full weight of underinsurance if your limits don’t match your actual exposure. Evaluating whether your current policy fits your building requires a direct comparison between what you own, what you’ve improved, and what your policy actually protects.

How to Evaluate if Your Current Policy Fits Your Building

Obtain Your Association’s Master Policy Details

Start by requesting your condo association’s master policy declaration page from your board or property manager. This document specifies exactly what the association covers, what it excludes, and what deductible applies to claims. Many Olympia condo owners have never seen this document, which means they operate without knowing their coverage gaps. The declaration page shows your association’s liability limits, whether water damage receives coverage under the master policy, and what the association requires you to carry individually. Some associations mandate minimum HO6 limits of $50,000; others require $100,000 or more. If your current policy falls below what your association requires, you violate your ownership agreement, and that violation could complicate claims or create liability exposure during disputes.

Inventory Your Unit’s Actual Improvements and Belongings

Walk through each room and list major items: furniture, electronics, artwork, and any structural improvements you’ve made. An Olympia condo owner with a $20,000 kitchen renovation, $8,000 in flooring upgrades, $3,000 in built-in shelving, and $15,000 in furniture and electronics needs coverage limits reflecting that $46,000 total investment. Most owners carry $30,000 to $50,000 in coverage and assume it’s adequate when their actual exposure runs significantly higher. Your HO6 policy should cover both personal property replacement cost and improvement coverage at amounts matching your real inventory.

Three-step guide outlining how Olympia condo owners can evaluate HO6 coverage against real risks and association requirements. - condo insurance Olympia WA

Pull your current policy declarations and compare the personal property limit and improvement coverage limit against your actual totals. If either limit falls short, you remain underinsured and personally liable for the difference in a claim.

Assess Water Damage Coverage Against Local Risk

Olympia’s older condo buildings along Capitol Lake and downtown areas face elevated water intrusion risk from aging pipes, failed waterproofing, and ground-level moisture. Your policy should explicitly cover water damage from sources outside your unit, not exclude it or cap it at $5,000. Contact your agent and confirm whether your current policy includes water backup coverage or whether water damage receives exclusion entirely. If excluded, request an endorsement adding it or switch carriers if your current insurer won’t provide it. Water damage from neighbors creates the most common claim gap in Olympia’s condo market, with claims averaging $15K to $25K per incident. A single incident involving a failed pipe in the unit above can saturate flooring, drywall, cabinetry, and personal property worth far more than a $5,000 cap.

Compare Your Liability Limits to Current Market Values

Compare your liability limit against Olympia’s property values and typical dispute costs. A $100,000 liability limit made sense ten years ago when median condo values ran lower. Today, with Thurston County assessor data showing condo values ranging from $200,000 to $500,000 depending on location and condition, liability awards in neighbor disputes frequently reach $150,000 or more. Most Olympia condo owners underestimate their liability exposure because they confuse the association’s common-area liability coverage with their own personal liability protection. Your HO6 policy typically carries $100,000 to $300,000 in personal liability coverage, but disputes between neighbors over water damage, structural defects, or shared wall problems routinely exceed these limits. When a neighbor’s water damage claim reaches $150,000 and your policy maxes out at $100,000, you personally owe the difference. Upgrading from $100,000 to $300,000 in personal liability coverage costs approximately $80 to $150 annually but protects your actual financial exposure. This comparison between your current limits and Olympia’s current market values reveals whether your policy genuinely fits your building or whether you carry yesterday’s coverage for today’s risks.

Final Thoughts

Your condo insurance in Olympia, WA requires the same attention you’d give to any major financial decision. Pull your current HO6 policy declaration and your association’s master policy details side by side, then compare your personal property limit, improvement coverage, and liability limit against what you actually own and what your building requires. If gaps exist between your coverage and your real exposure, contact your agent immediately and request updated quotes-most Olympia condo owners discover their coverage falls short only after a claim, which means you operate with unnecessary financial risk right now.

A local insurance agent who understands Olympia’s condo market makes this evaluation straightforward. They know which carriers offer the best rates for water damage coverage in older buildings, which liability limits make sense given current property values, and how to structure your policy so it works seamlessly with your association’s master coverage. At Cross Insurance Agency, our licensed agents shop multiple top-rated carriers to find you the right protection at competitive rates, and we provide local claims advocacy when you need it most.

Schedule a policy review with an agent who knows condo insurance and bring your current declarations and your association’s master policy. Spend thirty minutes comparing your actual exposure against your current limits-if your liability limit sits at $100,000 while your condo’s value exceeds $300,000, upgrading costs less than $150 annually but protects your actual financial exposure. Contact Cross Insurance Agency to start your review today and stop carrying yesterday’s coverage for today’s risks.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Your homeowners and auto insurance policies have limits. When someone sues you for more than those limits cover, your personal assets are at risk.

An umbrella policy fills that gap with extra liability protection. At Cross Insurance Agency, we help Washington residents find affordable umbrella policy costs that fit their budgets without sacrificing security.

What Umbrella Policies Actually Cover

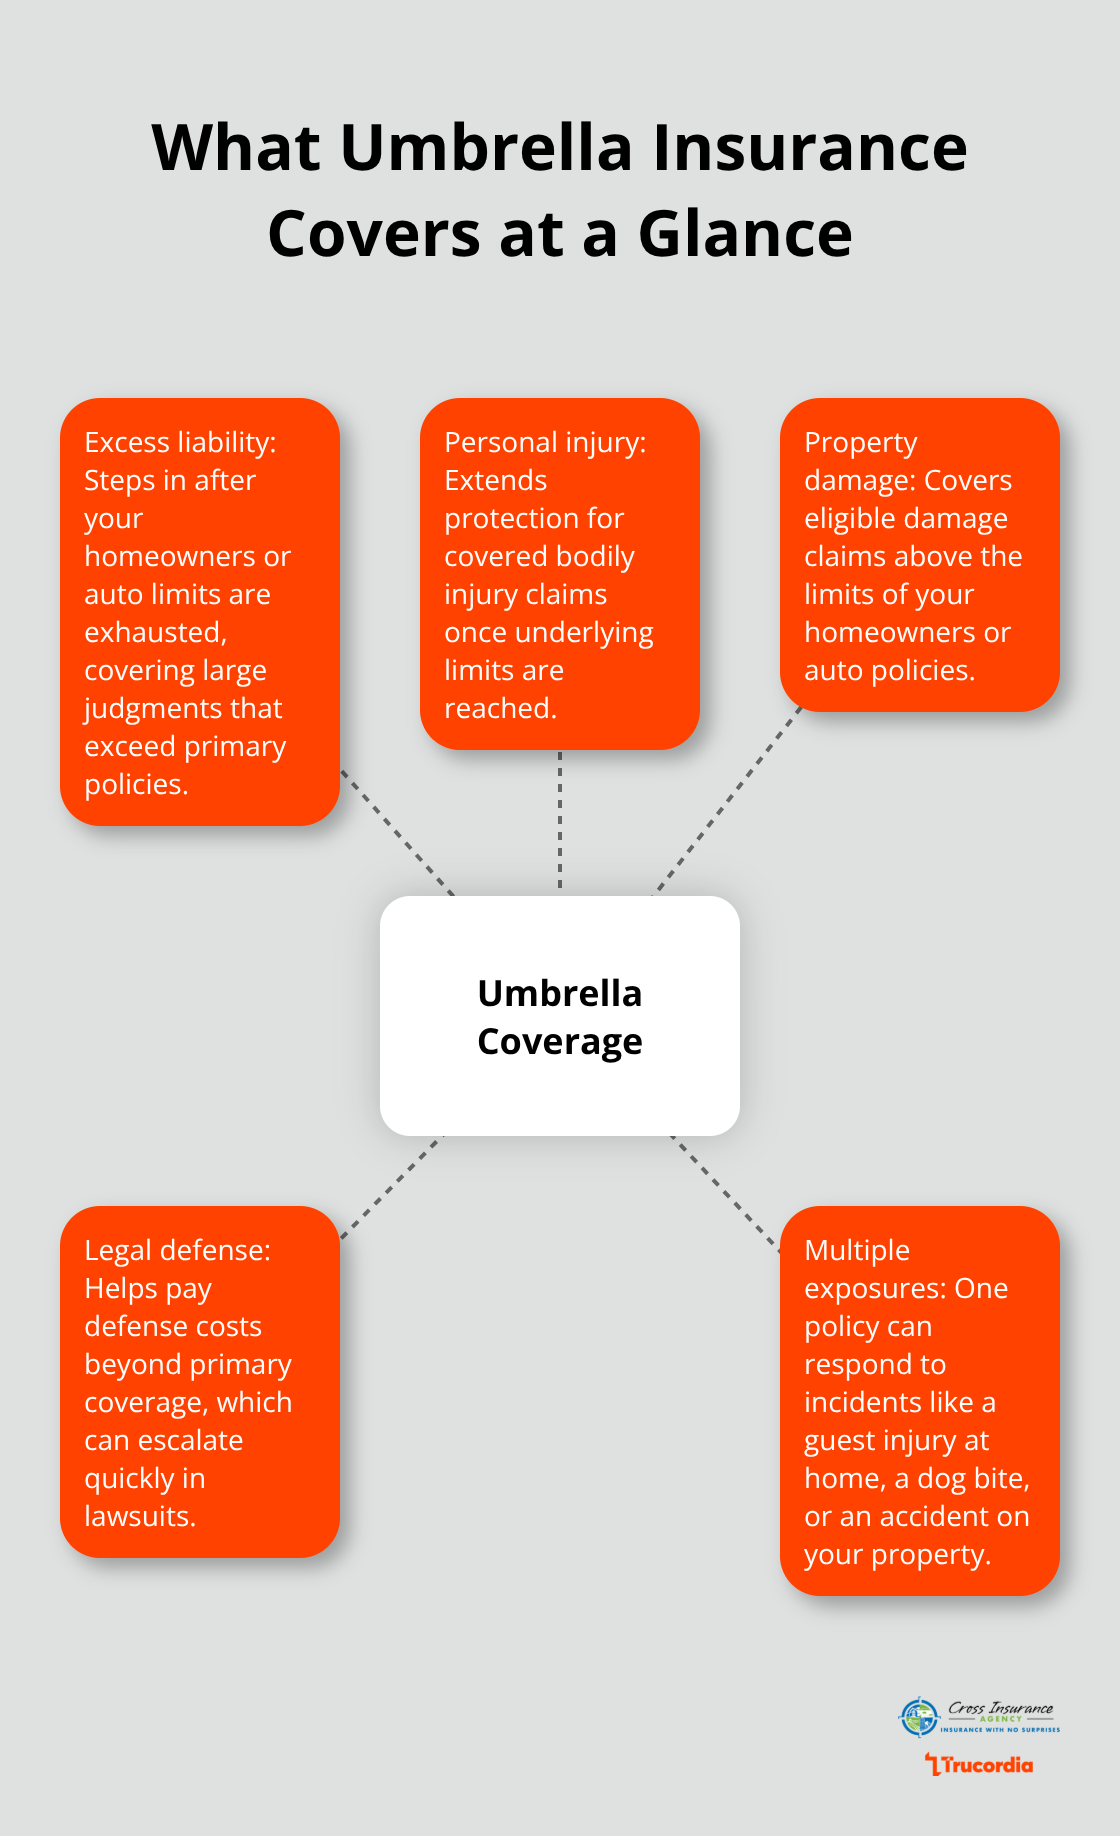
An umbrella policy sits above your homeowners and auto insurance, stepping in when a liability claim exceeds your underlying coverage limits. Washington’s median household income of $94,600 means most residents carry substantial assets worth protecting. If someone wins a lawsuit against you for $500,000 and your homeowners liability maxes out at $300,000, that $200,000 gap comes directly from your bank account, retirement savings, or wages. An umbrella policy fills exactly that gap, covering personal injury claims, property damage claims, and legal defense costs beyond what your primary policies pay. The coverage extends across multiple liability exposures simultaneously-a guest injured at your home, a dog bite incident, or an accident on your property all fall under the same umbrella.

Visual summary of what a personal umbrella policy typically covers beyond home and auto liability.

Unlike your homeowners policy, which typically caps liability at $300,000 or $500,000, umbrella policies start at $1 million and scale upward, giving you real breathing room when catastrophic events happen.

Why Your Assets Matter in Washington

Washington’s lack of personal income tax historically meant residents accumulated wealth differently, but a Millionaires Tax will introduce a 9.9% tax on households earning over $1 million annually starting in 2028. This shift makes asset protection more urgent now than ever. Combined with the state’s $16.28 minimum wage in 2024-the highest in the nation-household budgets are tight, meaning most people cannot absorb a six-figure liability judgment. Umbrella coverage costs roughly $150 to $300 annually for $1 million in protection when bundled with existing policies, a fraction of what a single lawsuit could cost. The misconception that umbrella insurance is only for wealthy people misses the reality: middle-class homeowners need it most because they have enough assets to lose but lack the legal resources to defend against major claims. Washington’s seismic and volcanic risk corridor, combined with heavy rainfall in western regions, increases property-related liability incidents-guests slip on wet decks, injuries result from falling branches-making umbrella coverage a practical necessity rather than a luxury add-on.

Matching Coverage to Your Actual Assets

Licensed agents help you match umbrella limits to your actual asset exposure. Most people underestimate what umbrella they need, thinking $1 million is excessive when they carry a $500,000 home and one vehicle. That math ignores future earnings, inherited assets, and the reality that courts award punitive damages in egregious cases. A practical approach starts with totaling your home value, vehicle equity, savings, and retirement accounts-that number guides your umbrella floor. If your assets total $750,000, a $1 million umbrella creates a reasonable buffer; if you own rental properties or run a home-based business, $2 million makes more sense.

Shopping Multiple Carriers for Better Rates

Umbrella pricing varies significantly based on your risk profile and the underlying policies carriers require. Some insurers demand higher homeowners liability limits before writing umbrella coverage, while others remain flexible. An independent agent who shops multiple carriers can compare quotes across different options rather than accepting the first offer from your existing insurer. This comparison process reveals substantial rate differences and helps you identify which carriers align with your coverage needs and budget constraints. The next step involves gathering your current policy declarations and speaking with an agent who can evaluate your specific situation.

What Drives Your Umbrella Cost in Washington

Three Factors That Shape Your Premium

Your umbrella premium hinges on three concrete factors that insurers evaluate before quoting rates. First, your underlying homeowners and auto liability limits directly impact umbrella cost-carriers require minimum underlying coverage before writing umbrella policies, and higher underlying limits typically lower your umbrella rate per million dollars of coverage. If your homeowners policy caps liability at $300,000, most insurers will ask you to raise it to at least $500,000 before they’ll issue umbrella protection. This requirement exists because umbrella policies coordinate with primary coverage; insurers won’t accept gaps between what your homeowner policy pays and where the umbrella begins.

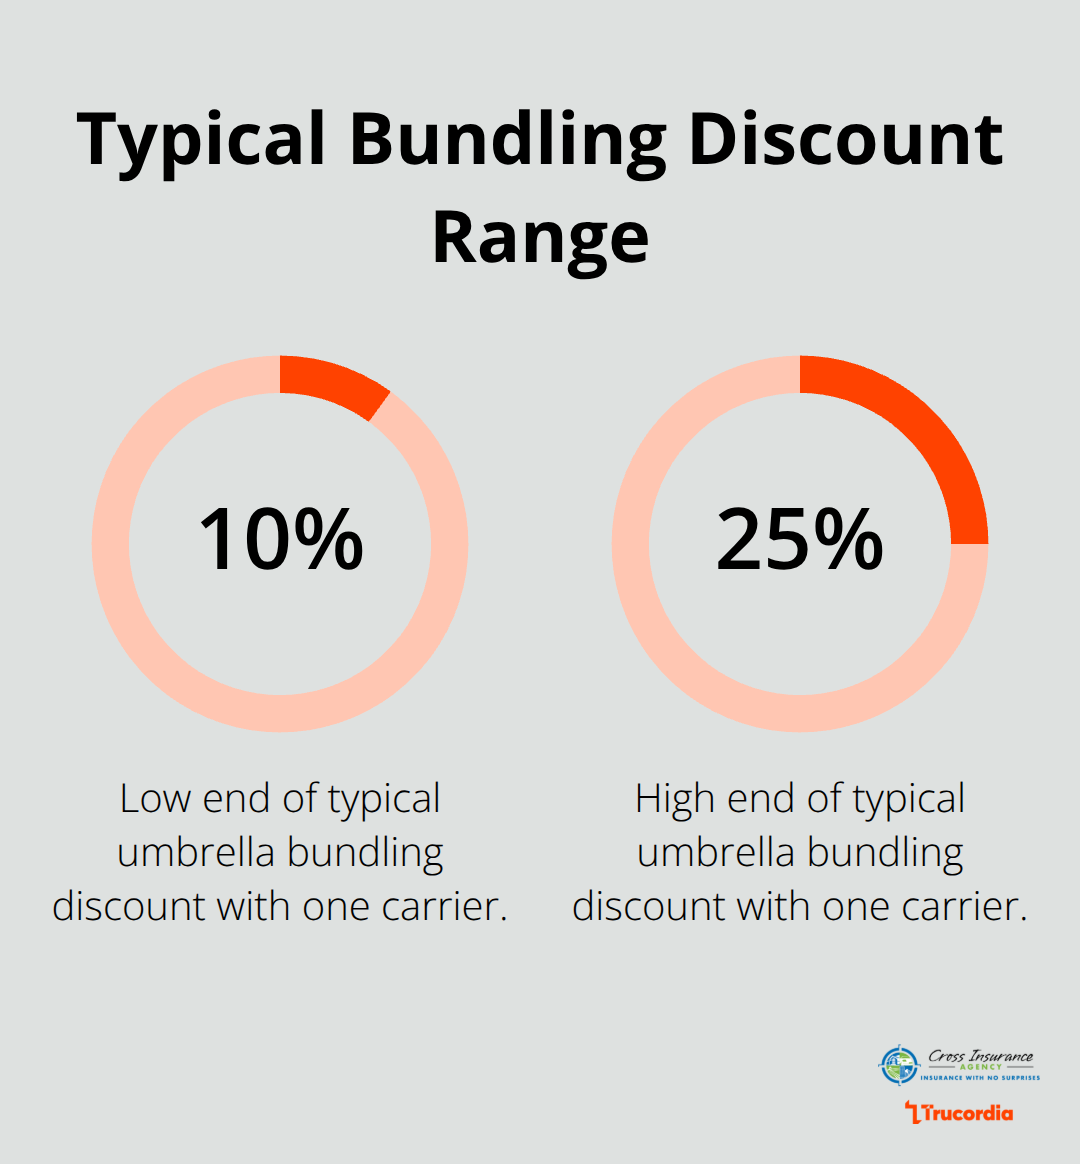
Second, your claims history and current risk profile shape pricing significantly. A clean record with no prior liability claims costs substantially less than a history of incidents. Third, bundling your umbrella with existing auto and homeowners policies generates meaningful discounts-typically 10% to 25% off umbrella premiums when you consolidate coverage with one carrier rather than shopping piecemeal.

How Washington’s Economy Affects Your Rates

Washington’s specific characteristics make these factors even more relevant to your costs. The state’s $16.28 minimum wage and $94,600 median household income create a demographic sweet spot for umbrella buyers-people with real assets but tight monthly budgets who need protection without paying premium prices. If you own a $600,000 home with $200,000 in savings and drive two vehicles, your asset base justifies $1 million to $2 million in umbrella coverage.

Raising your underlying homeowners liability from $300,000 to $500,000 costs roughly $50 to $100 annually but qualifies you for umbrella quotes from more carriers and typically reduces your umbrella rate. An independent agent shopping multiple carriers can identify which insurers offer the best rates for your specific asset profile and claims history.

Location and Risk Premiums in Washington

Carriers price differently based on whether you live in Seattle’s urban core versus rural eastern Washington, and some impose surcharges for properties near water or high-risk seismic zones. Getting multiple quotes from an independent broker reveals these variations rather than accepting one insurer’s standard rate. The umbrella itself might cost $150 to $400 annually for $1 million in coverage depending on your underlying limits, bundling discounts, location within Washington, and risk profile-a modest expense compared to the financial devastation a single lawsuit could inflict on your household.

These cost drivers matter because they show you exactly where to focus when shopping for affordable umbrella protection. Your next move involves understanding which bundling strategies actually save money and how to structure your underlying policies to qualify for the best umbrella rates available.

How to Structure Affordable Umbrella Coverage Without Overpaying

Start Small and Expand Your Protection Over Time

The smartest approach to umbrella insurance isn’t purchasing the maximum coverage you can afford-it’s building a strategy that matches your current assets while leaving room to expand later. Washington residents with tight monthly budgets often assume umbrella protection requires a large upfront commitment, but the reality is more flexible. Start with $1 million in coverage if your assets total between $500,000 and $1 million, then add another million-dollar layer in three to five years as your home appreciates or you accumulate additional retirement savings. This graduated approach costs roughly $150 to $250 annually for the first $1 million when bundled with homeowners and auto policies, then an additional $100 to $150 per million as you scale up.

The financial benefit is immediate: that initial umbrella costs far less than raising your underlying homeowners liability limit from $300,000 to $500,000, yet provides vastly superior protection. Many carriers require you to increase underlying liability limits before writing umbrella policies anyway, so consolidating all coverage with one insurer becomes the logical move.

Consolidate Your Policies for Maximum Discounts

When you consolidate homeowners, auto, and umbrella under a single carrier, discounts typically range from 10% to 25% on your umbrella premium alone. An independent agent shopping multiple carriers reveals which insurers offer the best bundling discounts for your situation-some carriers discount aggressively on umbrella when you bring them your homeowners and auto business, while others price umbrella competitively but offer minimal bundling incentives.

Chart showing typical bundling discounts on umbrella premiums when combined with home and auto policies. - umbrella policy cost WA

Obtaining quotes from at least three carriers takes roughly 30 minutes and uncovers rate differences that can save $200 to $500 annually on umbrella coverage alone. The carriers with the strongest financial ratings according to AM Best tend to price competitively in Washington’s market, so comparing quotes across carriers rated A or higher ensures you get both affordability and stability. After securing your umbrella quote, verify that your underlying homeowners and auto policies meet your carrier’s minimum requirements-this verification step prevents coverage gaps and qualifies you for the full bundling discount.

Work with an Independent Agent to Navigate Requirements

The process works best when you involve a licensed independent agent rather than contacting insurers directly. An agent already knows which carriers require $500,000 versus $1 million in underlying homeowners liability, which ones offer the steepest bundling discounts, and which impose location-based surcharges for properties near Seattle’s urban core or eastern Washington’s seismic zones. This knowledge saves you hours of phone calls and prevents the common mistake of accepting the first quote you receive.

The conversation with an agent also surfaces specific opportunities for your situation-some people lower umbrella costs by increasing auto liability limits instead of homeowners liability, since auto liability often costs less to raise. Others discover that their existing policies carry unnecessary coverage they can reduce, freeing budget for umbrella protection. Washington’s $16.28 minimum wage means most households operate on tight margins, so these adjustments matter.

Activate Coverage and Coordinate with Primary Policies

Once you’ve selected a carrier and bundled your coverage, the umbrella policy typically activates within 24 to 48 hours, providing immediate protection beyond your homeowners and auto limits. Your umbrella limit should exceed your liquid assets plus several years of income, with most policies written on a “pay on behalf” basis that streamlines claims handling between your primary coverage and the umbrella layer.

Final Thoughts

Umbrella policy cost in WA starts around $150 to $300 annually for $1 million in coverage when bundled with existing policies-a modest expense that shields you from financial catastrophe. Your home, savings, and future earnings face real risk when someone sues you for more than your standard policies cover, and Washington’s median household income of $94,600 means most residents carry substantial assets that deserve protection. Many skip umbrella policies thinking they’re unaffordable luxuries, but the truth is simpler: protection costs far less than the financial devastation a single lawsuit could inflict on your household.

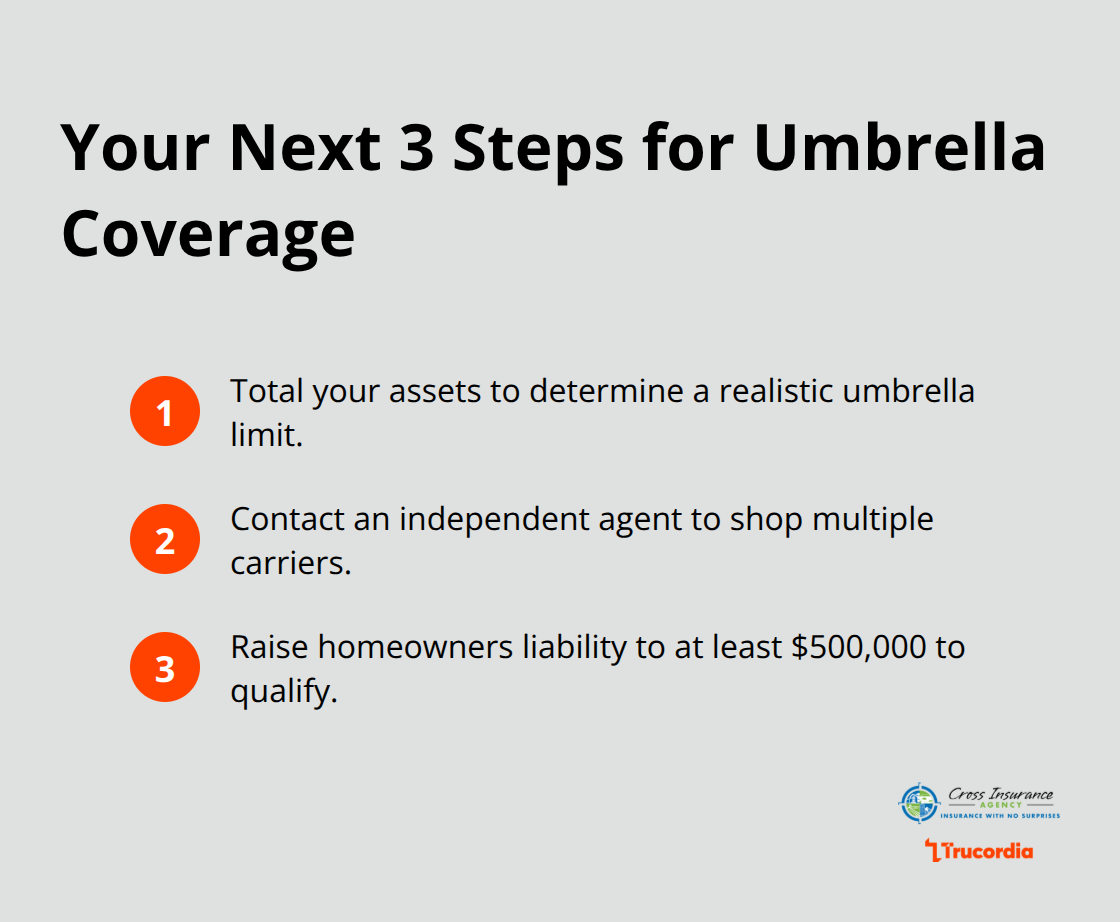
Three concrete steps move you forward. First, total your home value, vehicle equity, savings, and retirement accounts to determine how much umbrella coverage actually makes sense for your situation (most Washington residents need between $1 million and $2 million in protection based on their asset base and income trajectory). Second, contact an independent agent who can shop multiple carriers rather than accepting a single quote from your current insurer, since rate differences across carriers often exceed $200 to $500 annually. Third, raise your underlying homeowners liability limit to at least $500,000 before applying for umbrella protection, as carriers coordinate umbrella coverage with primary policies and won’t write umbrella without adequate underlying limits.

Compact checklist of three concrete steps to get affordable umbrella insurance in Washington. - umbrella policy cost WA

Contact Cross Insurance Agency to discuss your coverage needs and receive quotes from carriers competing for your business. Our licensed agents shop multiple top-rated carriers to deliver choice, bundling discounts, and personalized guidance tailored to your Washington situation. Your assets are worth protecting, and affordable umbrella coverage makes that protection realistic.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
Insuring a teen driver in Olympia comes with real costs and real risks. Parents face higher premiums because statistics show drivers under 20 have crash rates three times higher than drivers aged 20 and older.

At Cross Insurance Agency, we help families find teen driver insurance in Olympia that protects their budget without cutting corners on coverage. The right policy combines affordability with the liability protection your family needs.

Why Your Teen Needs Different Insurance Than You Do

Teen drivers represent a measurable risk that standard auto insurance policies simply don’t address. The Insurance Institute for Highway Safety reports that teen drivers have crash rates over 4 times those of drivers 20 and older per mile driven, and this isn’t a minor statistical variance. When a teenager gets behind the wheel, insurance companies know the probability of a claim increases dramatically. This reality shapes everything about teen driver coverage, from the premiums you’ll pay to the specific protections you need in place. Standard policies written for experienced drivers leave gaps that can expose your family to serious financial consequences.

The Cost of Teen Driver Accidents

Washington state doesn’t require separate teen driver policies, but the data shows why you need one anyway. According to the National Highway Traffic Safety Administration, motor vehicle crashes are the leading cause of death for teenagers in the United States. A single accident involving your teen can trigger medical bills exceeding $50,000, vehicle repair costs in the thousands, and potential liability claims from other parties. If your teen causes an injury to someone else, your liability coverage becomes critical protection. Without adequate limits tailored to teen driving patterns, a serious accident could threaten your family’s assets and future income. This isn’t theoretical-it’s why insurance companies charge more for teen drivers and why you need to structure that coverage carefully.

Legal Protection and Liability Exposure

Washington requires minimum liability coverage of 25/50/10, meaning $25,000 per person and $50,000 per accident for bodily injury, plus $10,000 for property damage. These minimums sound adequate until you consider what a serious injury actually costs. A teenager who causes a crash that injures another person faces medical expenses, lost wages, and pain-and-suffering claims that far exceed these state minimums. Your homeowner’s policy won’t cover auto-related liability, so your auto insurance becomes your only financial shield. Many parents in Olympia find that increasing liability limits to 100/300/100 or higher makes sense when a teen driver enters the household (this protects not just your vehicle, but your savings, home equity, and future wages if someone pursues a judgment against you).

Why Standard Coverage Falls Short

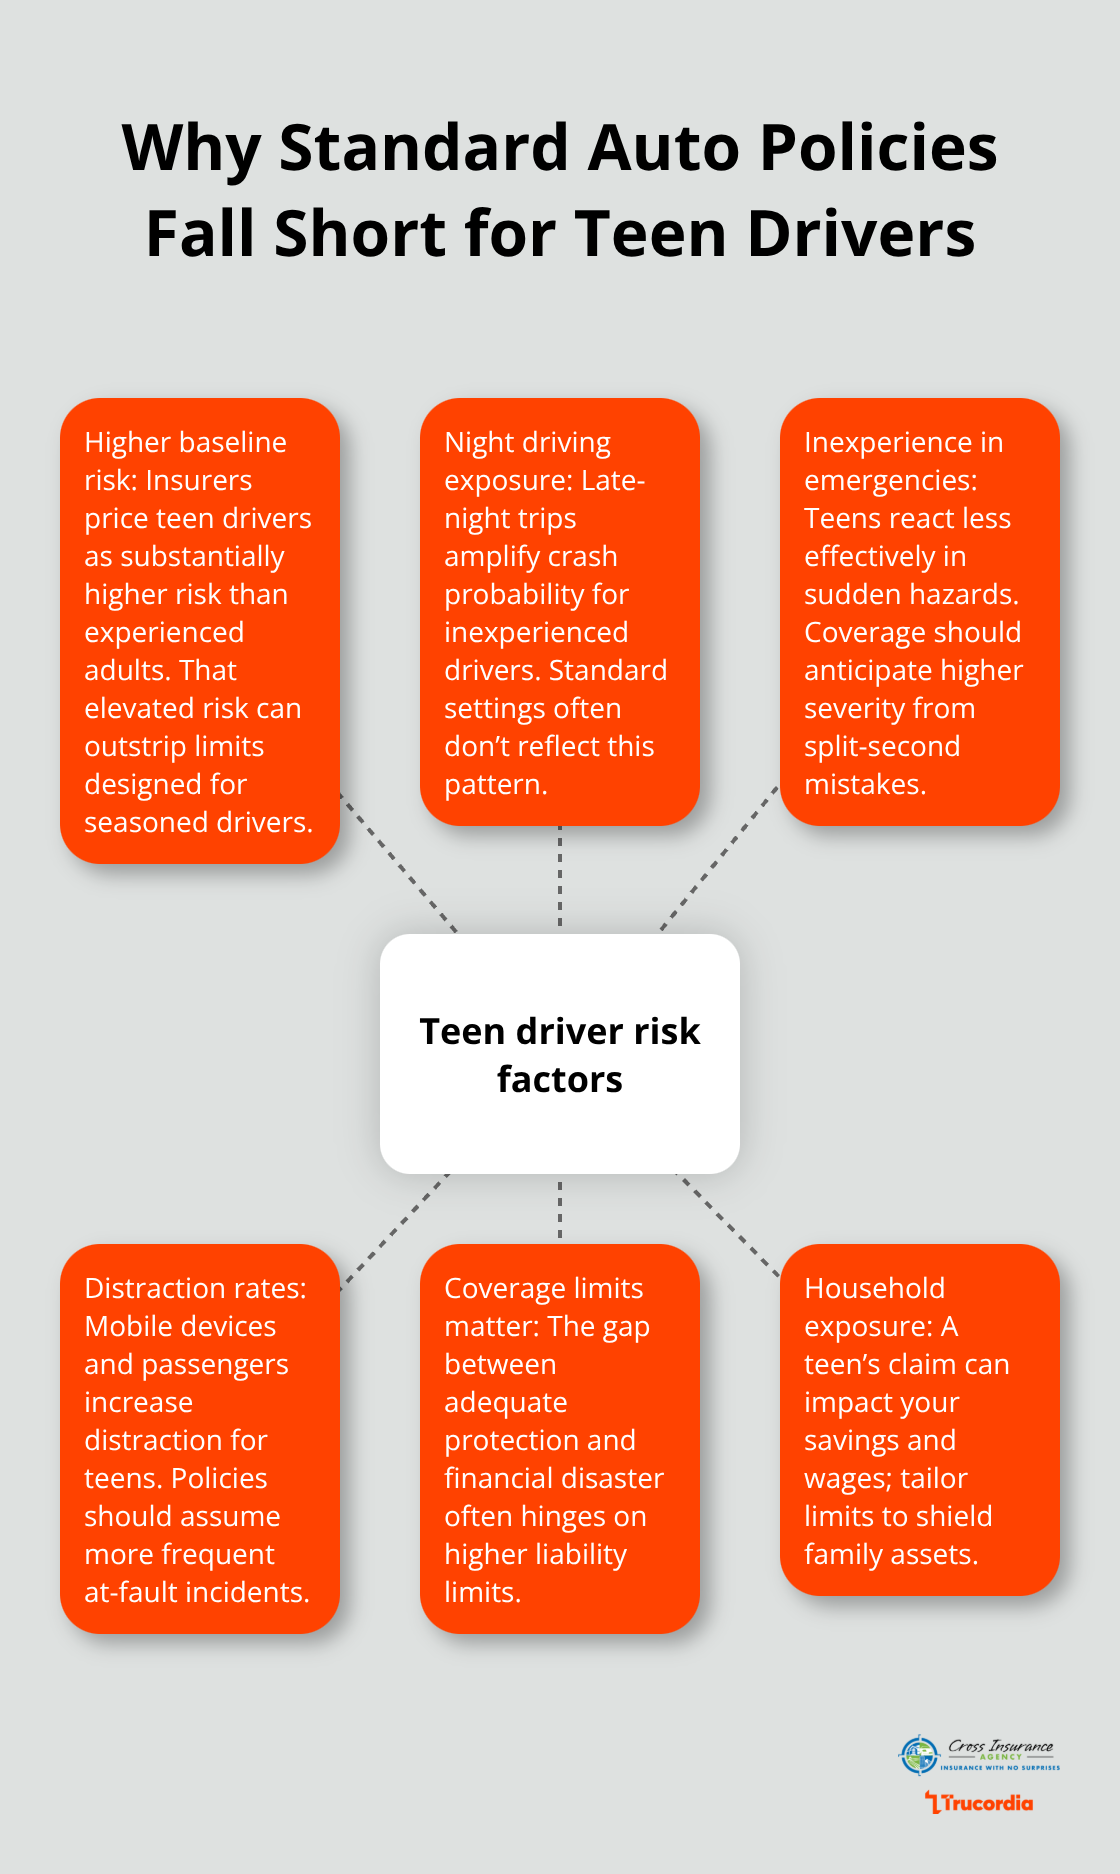
A standard auto policy treats all drivers the same way, which creates a dangerous blind spot when your teen takes the wheel. Insurance companies price policies based on risk, and teen drivers represent substantially higher risk than experienced adults. Your existing coverage may not account for the specific patterns of teen driving-late-night trips, inexperience in emergency situations, and higher rates of distraction. Adding a teen to your policy without reviewing your limits leaves your family exposed (the difference between adequate protection and financial disaster often comes down to coverage limits, not just the policy itself).

Hub-and-spoke graphic showing teen-specific risks and why standard auto policies can leave coverage gaps in the United States. - teen driver insurance Olympia

The next step involves understanding how to find affordable coverage that actually matches your teen’s risk profile.

Finding Affordable Teen Driver Coverage in Olympia

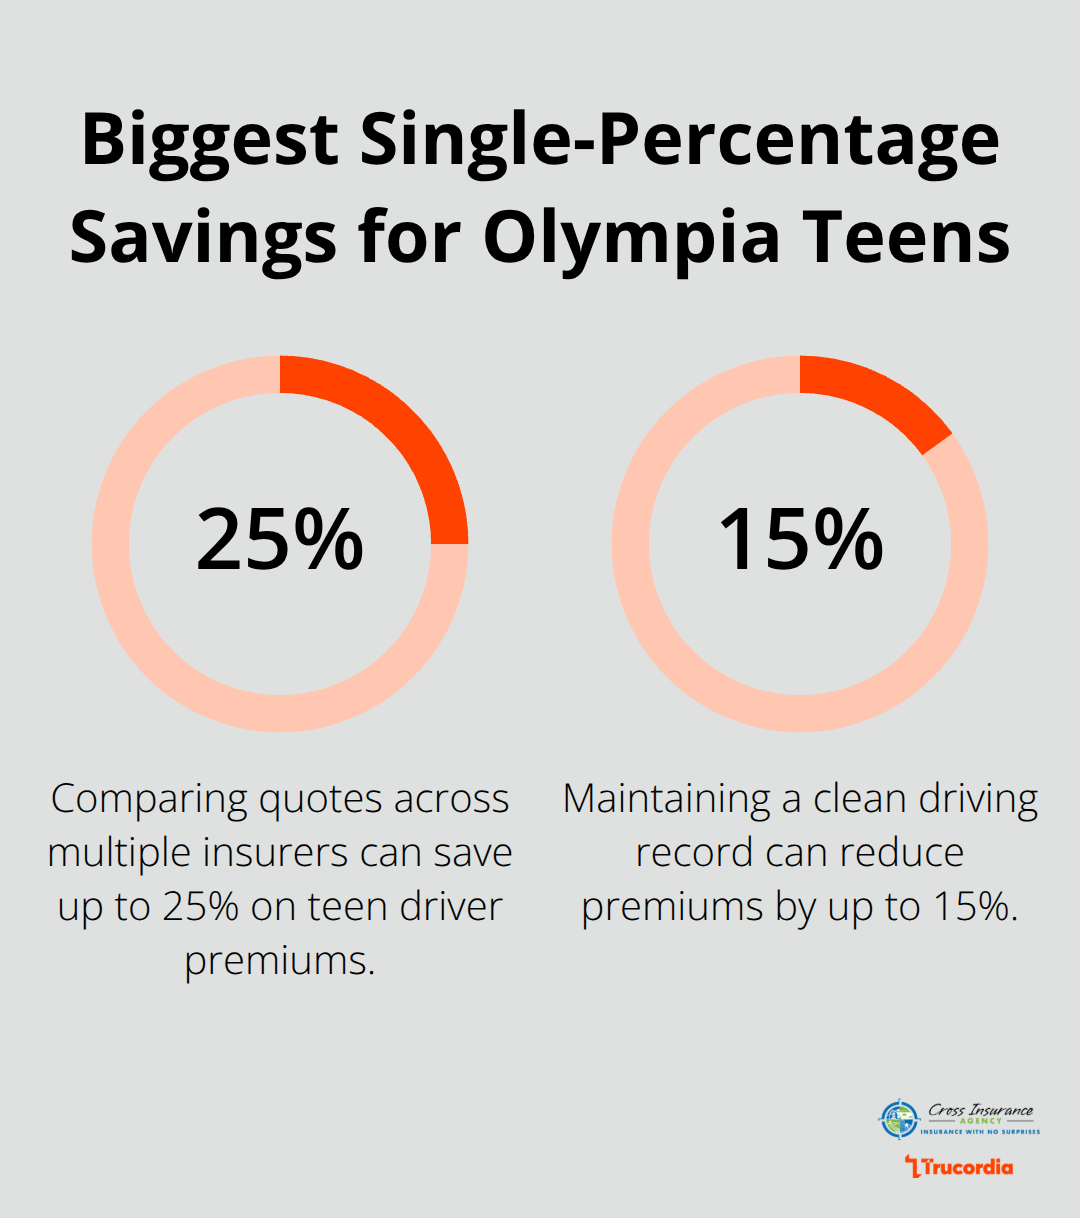
Getting quotes from multiple insurers takes roughly 30 minutes but saves up to 25% on teen driver premiums. Insurance companies price teen drivers differently based on their underwriting models, so State Farm, Allstate, GEICO, and regional carriers like Pemco all weigh teen risk factors through different formulas. Your teen might qualify for better rates at one company versus another. When you request quotes, provide identical information across all carriers-same vehicle, same coverage limits, same deductibles-so you’re comparing apples to apples.

Two percentage-based savings opportunities for teen driver insurance in the United States.

The difference between the highest and lowest quote for the same coverage often exceeds $1,000 over six months, which makes shopping non-negotiable rather than optional.

Stacking Discounts Cuts Premiums Significantly

Insurance companies offer discounts specifically for teen drivers that most parents never claim. Good student discounts typically run 3 to 5 percent off premiums when your teen maintains a B average or higher, and this applies at virtually every major carrier. Driver safety courses approved by Washington State can reduce premiums another 5 to 10 percent-courses from National Safety Council or Defensive Driving.com qualify at most insurers.

Compact list of common teen driver discounts and typical savings ranges in the United States. - teen driver insurance Olympia

Bundling your teen’s auto policy with your homeowners or renters coverage generates 15 to 25 percent savings across the entire bundle, according to data from the National Association of Insurance Commissioners. If your teen maintains a clean driving record for six to twelve months, most carriers offer accident-free discounts that lower rates further. The combination of three or four discounts can cut your teen driver premium by 30 to 40 percent, transforming an expensive line item into something manageable.

Local Agents Access Carriers Online Tools Miss

An independent agent in Olympia has access to carriers that online quote tools don’t display, which matters significantly for teen drivers. Regional carriers sometimes offer better teen rates than national companies because they price based on local accident data and driving patterns specific to Washington. Independent agents connect families with multiple carriers simultaneously rather than forcing you to visit individual company websites, saving time while expanding your options. Local agents also handle the claims process differently-when your teen has an accident, a neighborhood agent advocates on your behalf rather than treating you as a ticket number. Agents know which carriers in the Olympia area respond fastest to claims and which ones dispute coverage questions. This local knowledge prevents costly mistakes like discovering mid-claim that your coverage has a gap.

Moving Forward With Your Teen’s Coverage

The quotes you collect and the discounts you stack form the foundation of affordable teen driver insurance, but the real protection comes from matching coverage limits to your family’s actual exposure. Your next step involves reviewing what liability limits make sense for your situation and understanding how monitoring devices can lower premiums while keeping your teen safer on the road.

How to Actually Lower Your Teen’s Insurance Premium

Good grades and driver safety courses sound like obvious ways to reduce premiums, but the numbers tell a different story about which strategies actually move the needle. A B-average good student discount saves roughly 3 to 5 percent on your teen’s premium, which on a $2,000 annual policy amounts to $60 to $100 annually. Driver safety courses approved by Washington State generate 5 to 10 percent discounts, adding another $100 to $200 in savings. Combined, these two strategies might reduce your premium by $200 to $300 per year-meaningful money, but not transformative. The real leverage comes from what happens after your teen gets behind the wheel. Insurance companies care far more about actual driving behavior than credentials on a diploma.

Clean Driving Records Deliver the Biggest Savings

A teen who maintains a clean driving record qualifies for accident-free discounts that can reduce premiums by up to 15 percent. This is where the substantial reductions happen: when your teen proves through months of safe driving that they represent lower risk than the average sixteen-year-old. Insurance companies replace statistical assumptions with documented evidence of safe habits.

Telematics Devices Replace Guessing With Data

Telematics devices and monitoring apps shift the insurance equation in your favor because carriers base teen driver premiums partly on assumptions about behavior. When your teen uses a monitoring app like Snapshot from Progressive or Allstate’s Drivewise, the insurer collects real data about acceleration, braking, speed, and time of day your teen drives. Teens who use these apps average 10 to 15 percent premium reductions because insurers replace statistical guessing with actual driving patterns. Some carriers like Pemco offer usage-based programs specifically marketed to teen drivers, pricing based on documented safe behavior rather than age alone.

Restricted Driving Privileges Cut Risk and Costs

The most effective approach combines monitoring with restricted driving privileges during high-risk periods. Crash data from the National Highway Traffic Safety Administration shows teen crash rates spike between 9 PM and midnight, so limiting your teen’s driving to daytime hours during the first six to twelve months of licensure dramatically reduces accident probability. Restricting nighttime driving during this critical early period costs nothing but saves 5 to 10 percent on premiums while cutting actual crash risk substantially.

Stacking Strategies Produces Real Savings

Parents who implement both monitoring devices and graduated driving restrictions see cumulative discounts reaching 25 to 35 percent, transforming a $2,000 annual premium into something closer to $1,300 to $1,500. This combination works because insurers reward measurable risk reduction, not just paperwork. The strategies that produce the largest premium cuts all share one characteristic: they provide insurers with concrete evidence that your teen represents lower risk than typical teen drivers.

Final Thoughts

Affordable teen driver insurance in Olympia comes down to three actions: comparing quotes across multiple carriers, stacking every available discount, and implementing monitoring devices or driving restrictions that prove your teen represents lower risk than statistics suggest. Families who pay the least don’t sacrifice coverage-they match their protection to actual exposure and provide insurers with evidence of safe driving behavior rather than relying on age-based assumptions. Local agents access carriers that online quote tools never display, and regional companies often price teen coverage differently than national competitors.

When your teen has an accident, a local agent advocates on your behalf during the claims process instead of treating you as a policy number. Install a monitoring app like Snapshot or Drivewise and restrict nighttime driving during the first six to twelve months of licensure-these two actions combined typically reduce premiums by 25 to 35 percent while cutting actual crash risk substantially. If your teen maintains a B average or completes a driver safety course approved by Washington State, claim those discounts before your policy starts.

Contact Cross Insurance Agency to connect with independent agents who shop multiple top-rated carriers for teen driver insurance in Olympia and handle claims with the responsiveness your family deserves. Our licensed agents find the coverage that fits your budget while protecting your assets and future income. Get quotes from at least three carriers this week to start lowering your teen’s premium today.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
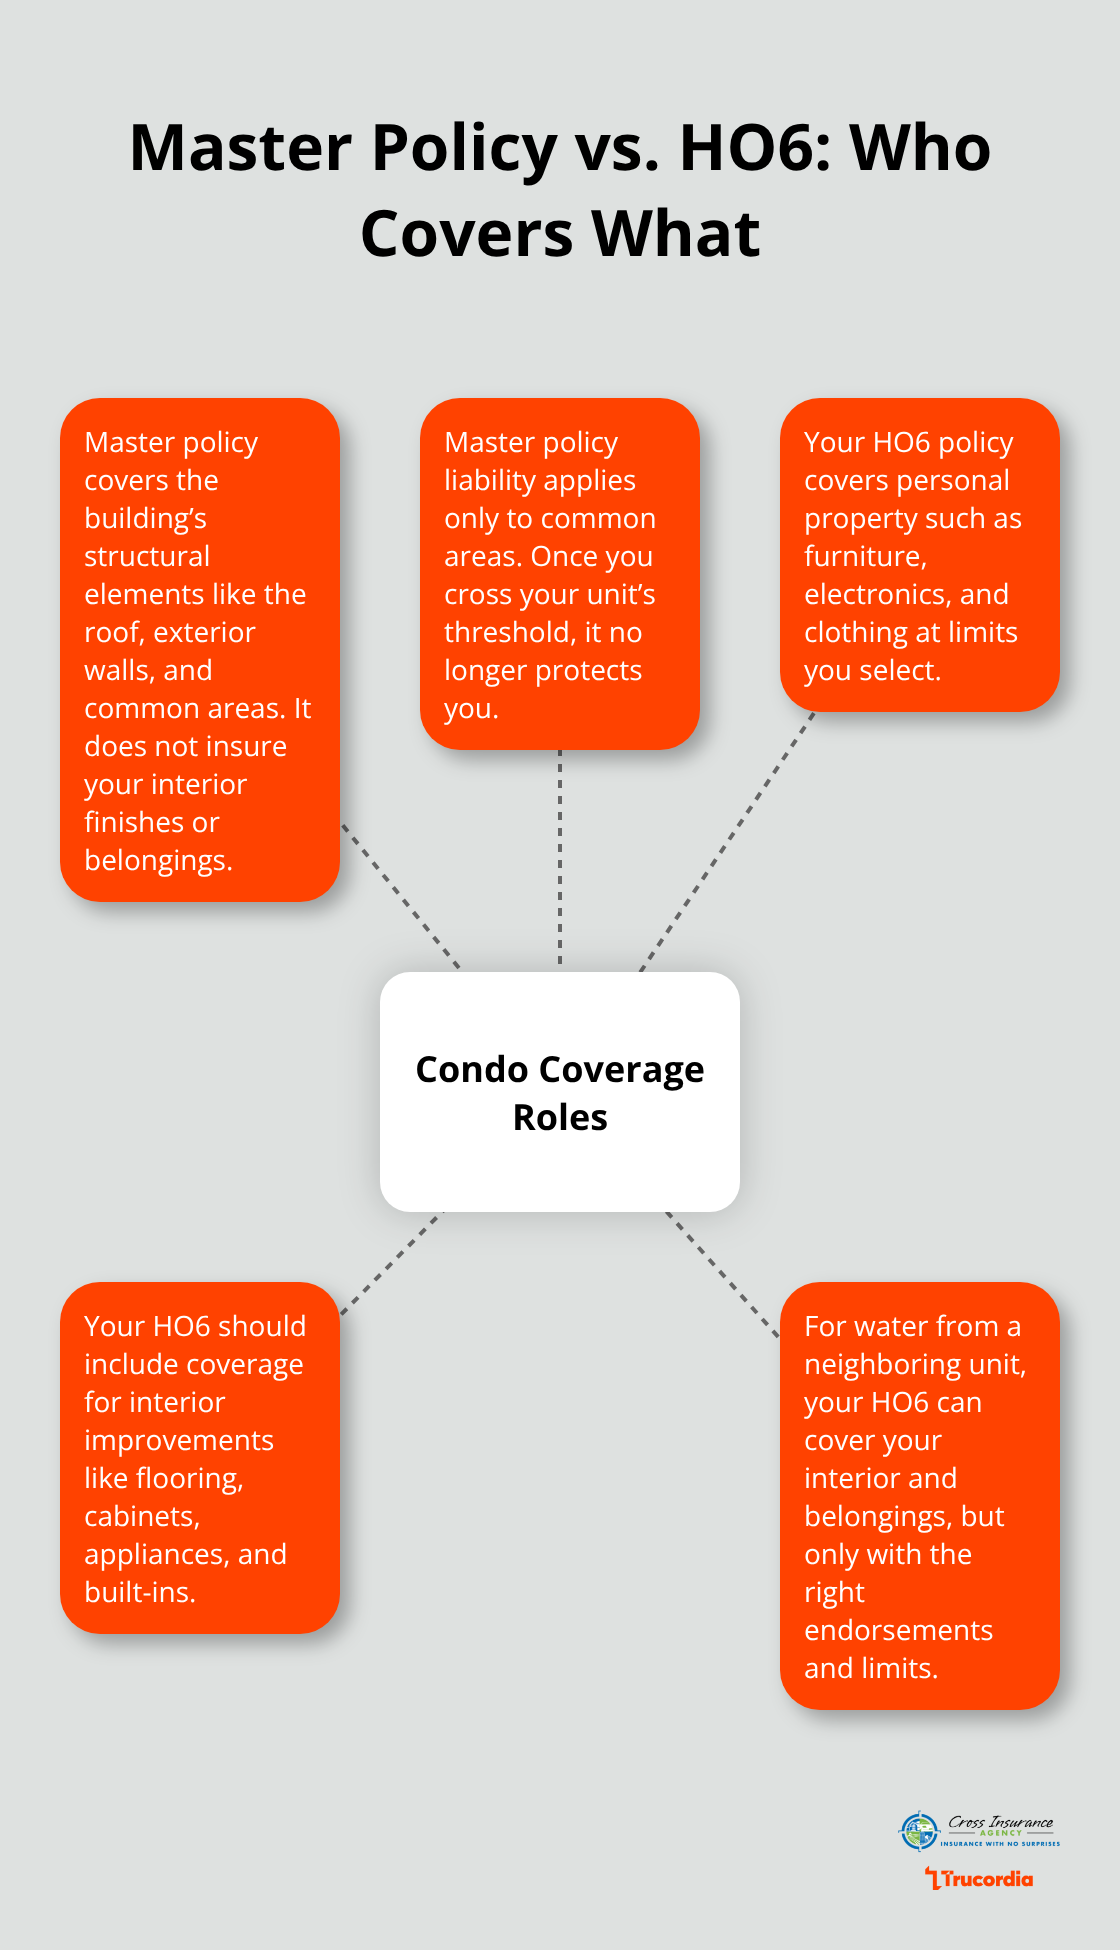
Owning rental property in Washington comes with real financial risk. Your standard homeowners policy won’t cover tenant-related losses or liability claims that landlords face every day.

At Cross Insurance Agency, we help Washington landlords build rental property insurance WA policies that actually protect their investment. This guide walks you through the coverage types you need, how to spot gaps in your protection, and how to choose the right policy for your specific situation.

What Landlords Actually Face in Washington

Washington’s Legal Requirements for Landlords

Washington State doesn’t mandate landlord insurance by law, but your mortgage lender almost certainly does-most require it as a condition of financing. Washington’s Residential Tenancy Act gives tenants substantial legal protections, which means your liability exposure is real and significant. The state allows tenants to withhold rent for uninhabitable conditions, file complaints with local housing authorities, and pursue damages through small claims court or civil lawsuits. A single liability claim from a tenant injury can easily exceed $100,000, and your standard homeowners policy explicitly excludes rental properties.

Why Your Homeowners Policy Fails You

Your homeowners insurance is designed for owner-occupied properties only. It won’t cover liability claims from tenants, damage caused by tenants, or income loss when a tenant stops paying rent. If a tenant is injured on your property and sues, your homeowners insurer can deny the entire claim because the property generates income. Rental property insurance fills these gaps by covering tenant-caused damage, loss of rent during disputes or extended vacancies, and liability specific to landlord situations. It also covers landlord-specific perils like malicious damage beyond normal wear and tear. The cost difference is modest-rental property insurance typically runs 15-25% more than standard homeowners coverage but protects against losses that could bankrupt an unprepared landlord.

Three Coverage Gaps That Hurt Most

Landlords commonly face three major protection failures. First, they lack loss of rent coverage, which means if a tenant damages the property and you must evict them, you absorb months of lost income while repairs happen. An eviction in Washington takes 30-90 days minimum, and during that time your mortgage, taxes, and maintenance bills don’t pause. Second, they underestimate liability exposure-a tenant slip-and-fall, a guest injury on the property, or a code violation injury can trigger claims exceeding their policy limits. Third, they don’t cover tenant-caused damage adequately, assuming their security deposit covers everything.

Three common rental property insurance gaps Washington landlords face and why they matter - rental property insurance WA

Security deposits in Washington are capped at one month’s rent, but a tenant can cause $10,000 in damage in days. Proper rental property insurance covers these scenarios with specific protections that homeowners policies simply don’t address.

What Rental Property Insurance Actually Covers

The right rental property insurance policy protects you against the specific risks that come with tenant-occupied properties. Building and structure protection covers damage to the physical property from fire, theft, vandalism, and weather events. Liability coverage protects you when a tenant or their guest is injured on your property and files a claim against you. Loss of rent coverage replaces your income during evictions, extended vacancies, or when the property becomes temporarily uninhabitable.

Hub-and-spoke chart showing building protection, liability coverage, and loss of rent for Washington landlords - rental property insurance WA

These three components work together to address the gaps that leave unprepared landlords exposed. Understanding what each type of coverage does helps you make informed decisions about your protection level and policy limits.

Essential Coverage Types for Your Washington Rental Property

Building and Structure Protection

Building and structure protection covers the physical property itself-the walls, roof, foundation, built-in appliances, and permanent fixtures. This protection applies to damage from fire, theft, vandalism, weather events, and other named perils, depending on your policy form. In Washington, where winter storms and heavy rain are common, this coverage matters significantly.

You must insure the property for its full replacement cost, not just the current market value. Many landlords underestimate replacement costs and end up underinsured. A professional property appraisal or reconstruction estimate from a contractor determines the actual replacement value accurately. Don’t rely on what you paid for the property years ago-construction costs have risen substantially.

If your property costs $400,000 to replace but you only insure it for $300,000, your insurer will pay claims proportionally, leaving you responsible for the gap. This is called coinsurance, and it’s a costly mistake. Try insuring to at least 100% of replacement cost, and some landlords benefit from extended replacement cost coverage that pays up to 125% if reconstruction costs exceed estimates.

Liability Coverage for Tenant-Related Claims

Liability coverage protects you when a tenant, tenant’s guest, or even a trespasser is injured on your property and sues you for damages. Washington courts have awarded substantial judgments in landlord liability cases-slip-and-fall claims frequently exceed $50,000, and serious injuries can reach $200,000 or more. Your liability coverage pays legal defense costs, medical expenses, and court judgments up to your policy limit.

Standard limits start at $300,000, but many landlords carrying multiple properties or properties in higher-risk areas need $500,000 to $1,000,000 in protection. The right limit depends on your property type, location, and tenant profile. A single serious injury claim can wipe out years of rental income, making adequate liability limits non-negotiable.

Loss of Rent Coverage During Evictions and Repairs

Loss of rent coverage replaces your monthly income during specific situations: when a tenant damages the property and you must evict them while repairs happen, when the property becomes uninhabitable due to a covered peril, or during extended vacancies you couldn’t have prevented. Washington evictions take 30 to 90 days minimum, and during that time your mortgage, property taxes, insurance, and maintenance costs continue.

Loss of rent coverage typically reimburses 30 days of lost rent per claim, though you can purchase extended periods if needed. If your property rents for $2,000 monthly, a 60-day eviction and repair cycle means $4,000 in lost income you’d otherwise absorb alone. This coverage is inexpensive relative to the protection it provides, usually adding only $15 to $40 monthly to your premium.

Understanding these three coverage types helps you move forward with confidence when selecting your policy limits and protection level. The next step involves assessing your specific property value and risk factors to determine exactly how much coverage you actually need.

How to Choose the Right Rental Property Insurance Policy

Calculate Your True Replacement Cost

Start with an honest assessment of what your property would actually cost to rebuild from scratch. This number determines your entire protection strategy, and most landlords get it wrong by relying on outdated valuations or guesswork. Contact a local contractor in Washington and request a detailed reconstruction estimate that accounts for current labor costs, materials, and local building codes. Replace your property’s value based on actual reconstruction costs-this means determining what it would cost to rebuild your home at today’s construction prices, rather than relying on market value.

Many landlords overlook additional structures like detached garages, storage sheds, or fences-these add to your replacement cost and need separate coverage. Once you have the reconstruction estimate, add 10-15% as a buffer for cost inflation and unexpected complications during rebuilding. This gives you a realistic insurance-to-value ratio that prevents coinsurance penalties when you file a claim.

Evaluate Your Property’s Risk Profile

Your property’s specific risk profile shapes which coverage options matter most. A single-family home in a quiet neighborhood has different exposure than a multi-unit building in an urban area or a property with a history of tenant turnover. Walk through your property and document condition issues-deferred maintenance, outdated electrical systems, older roofing, or problematic drainage all increase claim frequency and affect your premium.

Properties with previous water damage or theft claims will face higher rates or coverage restrictions. Request quotes from at least three carriers because rates for identical coverage vary significantly based on each insurer’s appetite for your specific risk profile. One carrier might specialize in older homes and offer competitive rates while another charges substantially more.

Compare Quotes Accurately

When comparing quotes, verify that all three include identical coverage limits, deductibles, and protection types-comparing a $500 deductible quote against a $1,000 deductible quote tells you nothing about actual value. Document your property’s square footage, construction type, year built, roof condition, and any recent upgrades or repairs, as these details directly impact pricing across carriers.

Checklist of items to match and document when comparing rental property insurance quotes in Washington

An independent insurance broker shops multiple top-rated carriers for each client, which reveals pricing variations and prevents you from overpaying for the same protection.

Work With a Local Agent Who Specializes in Landlords

Not all insurance agents understand landlord-specific risks or Washington’s tenant laws. An agent who specializes in rental properties knows which carriers offer competitive rates for loss of rent coverage, which ones provide adequate liability limits for multi-unit properties, and how to structure coverage that actually works when you need to file a claim.

Interview potential agents and ask specifically about their experience with Washington eviction timelines, tenant damage claims, and liability disputes. A strong local agent provides claims advocacy when something goes wrong-they understand your policy language, know which carriers handle claims efficiently, and push back when an insurer tries to deny a legitimate claim. This advocacy saves money and stress during the worst moments of property ownership.

Final Thoughts

Rental property insurance WA protects your income, your assets, and your peace of mind when tenant disputes or property damage strike. The three coverage types we’ve covered-building protection, liability coverage, and loss of rent-address the specific risks that homeowners policies ignore completely. Without them, a single tenant injury claim or property damage incident can eliminate years of rental income and force you into financial hardship.

Your next step is straightforward: get your property professionally appraised for replacement cost, document its current condition, and request quotes from multiple carriers. Rates vary significantly between insurers, and the cheapest option often leaves dangerous gaps in your protection (a $50 monthly premium difference compounds to $600 annually). Washington’s tenant laws give renters substantial protections, which means your liability exposure is real and demands adequate coverage limits.

Contact our team at Cross Insurance Agency to get quotes tailored to your specific rental property and situation. Our licensed agents shop multiple top-rated carriers to find coverage that actually fits your property and your budget. We handle the comparison work, explain what each policy covers, and provide claims advocacy when you need it most.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
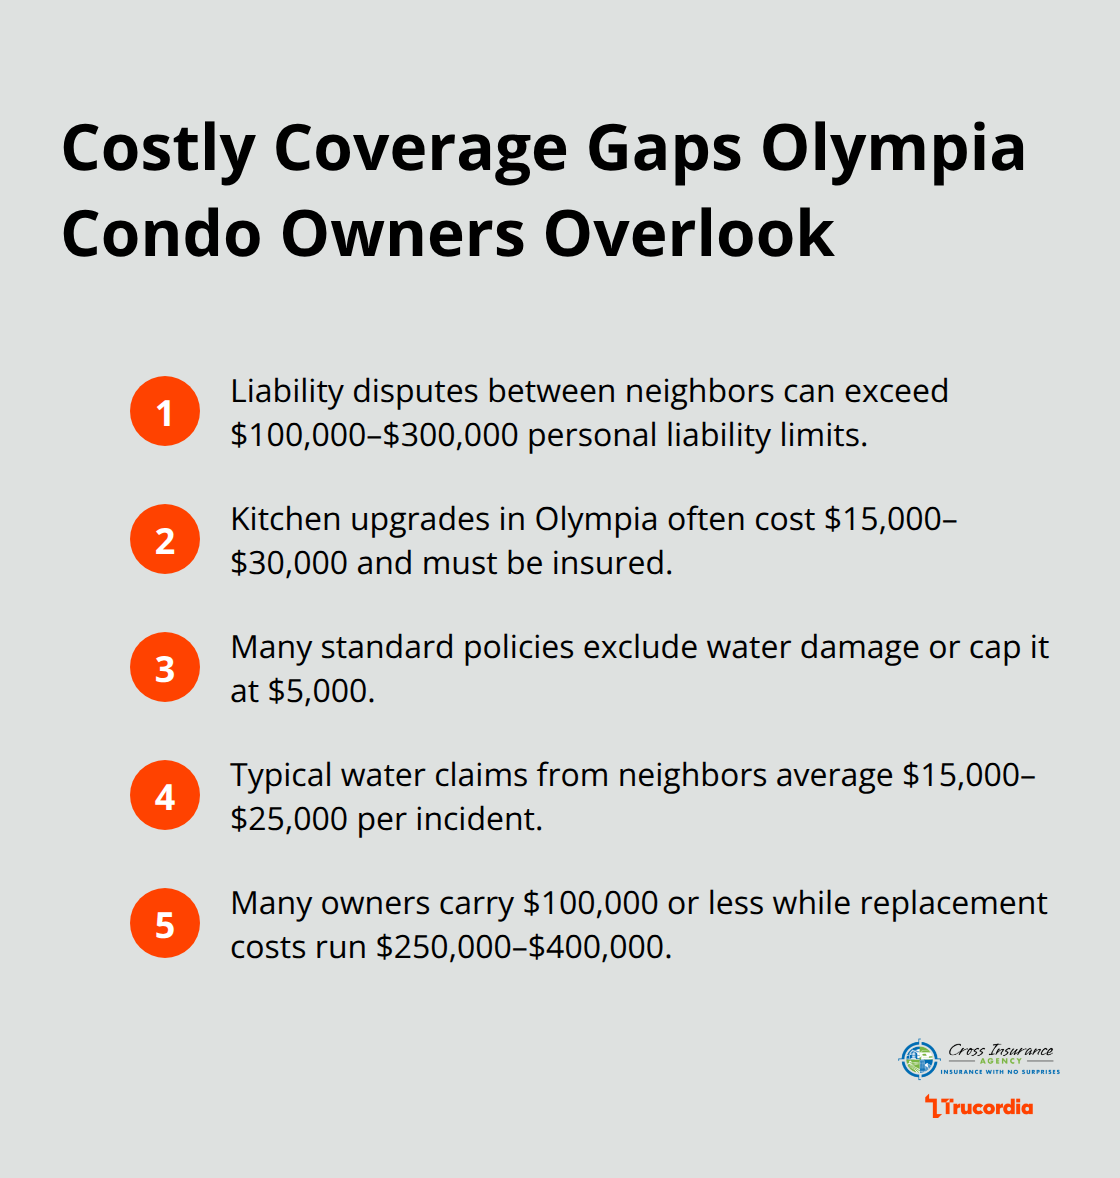
Standard homeowners insurance won’t cover your vacation rental business. Most policies explicitly exclude short-term rental income and guest-related liability, leaving your investment exposed.

At Cross Insurance Agency, we see this gap repeatedly. Vacation rental insurance in WA fills those holes with coverage designed specifically for your rental operation.

Why Standard Homeowners Insurance Fails Vacation Rentals

Your Policy Excludes Rental Activity

Your standard homeowners policy treats your property as a primary residence, not a revenue-generating asset. The moment you list your property on Airbnb or VRBO, most major carriers will either cancel your coverage or deny claims related to rental activity. This isn’t theoretical-it’s how the insurance industry actually works. Homeowners policies exclude short-term rental income, guest injuries, and damage caused by transient occupants. If a guest slips on your stairs and sues for $50,000 in medical bills, your homeowners insurer will likely refuse to defend you because the injury occurred during a rental period. That gap between what you think you’re covered for and what you actually are covered for is where vacation rental owners in Washington face real financial exposure.

Short-Term Rentals Create Different Risk Profiles

Short-term rentals create risk profiles that standard homeowners policies simply don’t account for. Your property experiences constant turnover-new guests arrive every few days or weeks, which means more people move through your space, more opportunities for accidents, and higher wear-and-tear on furnishings and appliances. Furnished properties face significantly higher loss frequency than owner-occupied homes, particularly around theft, accidental damage, and liability claims. A guest who damages your kitchen during a week-long stay represents a different risk than a family living there permanently.

Income Loss and Liability Gaps

If your property sits vacant between bookings or if a major incident forces you to cancel reservations, you lose rental income-something your homeowners policy won’t replace. Vacation rental insurance in Washington specifically addresses these gaps with coverage for guest liability, loss of rental income during property damage, and protection against vandalism and theft of furnished contents. The liability exposure alone justifies making this switch. A single guest injury claim can reach tens of thousands of dollars, and without proper coverage, you’re personally liable for amounts far exceeding your homeowners policy limits.

Visual map of essential coverages for a Washington vacation rental property. - vacation rental insurance WA

These coverage gaps mean you need a policy built for your actual business model. The right vacation rental insurance protects both your property and your income stream-two things standard homeowners coverage simply cannot do.

What Coverage You Actually Need for Your Washington Rental

Host Protection Liability Shields You from Guest Injuries

Guest liability claims represent the most immediate financial threat to your vacation rental operation. When a visitor slips on wet flooring, suffers a fall from a balcony, or gets injured by a defective appliance, you face personal liability that extends far beyond typical homeowners coverage limits. A serious injury claim can easily reach $100,000 or more in medical expenses, lost wages, and pain-and-suffering damages.

Vacation rental insurance in Washington provides host protection liability specifically designed to defend you against these guest-related claims and cover legal fees if litigation occurs. This coverage typically includes bodily injury liability for guests and third parties, as well as property damage liability if a guest accidentally damages a neighboring unit or someone else’s belongings.

The liability limit matters tremendously. Most Washington properties need minimum coverage of $300,000 to $500,000, though high-value homes or those with swimming pools warrant $1,000,000 or higher. Standard policies cap liability at $300,000 to $500,000, which leaves you dramatically underprotected once rental activity begins.

Loss of Rental Income Coverage Protects Your Cash Flow

Loss of rental income coverage protects your cash flow when your property becomes temporarily uninhabitable due to a covered loss. A kitchen fire, severe water damage from burst pipes, or damage from a severe storm could force you to cancel bookings for weeks or months. Without this coverage, you absorb the full financial impact-potentially thousands of dollars per week in lost reservation income.

This coverage reimburses you for lost rental income during the repair period, typically up to your average daily rental rate multiplied by the number of days needed for repairs. The protection activates when a covered peril makes your property unrentable, ensuring your business survives unexpected disruptions.

Furnished Contents and Theft Protection Address High-Risk Losses

Furnished properties face elevated theft and vandalism risks compared to owner-occupied homes. Guest turnover creates opportunities for theft of electronics, artwork, and high-value furnishings, while careless guests or intentional damage can destroy your décor and fixtures. Vacation rental insurance includes specific protection for furnished contents and theft coverage tailored to short-term rental environments.

Document your property’s contents with photos and estimated values to establish adequate coverage limits. Most insurers allow coverage limits between $10,000 and $50,000 for furnished contents depending on your property’s quality and amenities. This documentation becomes essential if you file a claim, as it proves what you owned and its replacement cost.

Selecting the Right Coverage Limits for Your Property

Your property type, location, and guest volume all influence the coverage limits you need. A modest two-bedroom cottage in a rural area requires different protection than a luxury waterfront home in a popular tourist destination. Properties with pools, hot tubs, or other attractive nuisances warrant higher liability limits because they increase injury risk significantly.

The next step involves comparing how different carriers structure their policies and what endorsements they offer to fill remaining gaps in your protection.

How to Choose the Right Vacation Rental Insurance Policy

Your property type, rental frequency, and guest volume determine which policy structure makes sense for your situation. A three-bedroom home rented 200 nights per year operates under different risk conditions than a studio apartment rented year-round, and your insurance needs to reflect that distinction. Start by calculating your actual rental days annually-this number directly influences both your premium and the coverage options available to you. Properties rented fewer than 90 days per year sometimes qualify for standard homeowners policies with short-term rental endorsements, which cost significantly less than dedicated vacation rental policies. Properties rented more than 180 days annually almost always require full vacation rental coverage because the risk profile shifts from occasional rental to primary business operation.

Compact checklist of steps to select the right vacation rental insurance policy in Washington.

Your property location matters equally. A beachfront home in a high-tourism area faces different theft and liability exposure than an inland property, and coastal properties require separate earthquake or wind coverage depending on their specific geographic risk. Document your property’s square footage, construction year, number of bedrooms and bathrooms, and any special features like pools or hot tubs-carriers use this information to calculate accurate premiums and appropriate liability limits.

Coverage Limits Must Match Your Actual Exposure

Standard vacation rental policies typically offer liability coverage starting at $300,000, but this number represents a floor, not a recommendation. A serious guest injury claim routinely exceeds this amount-medical expenses alone for a spinal cord injury or permanent disability can reach $500,000 to $1,000,000. Most Washington properties need minimum $500,000 liability coverage, with $1,000,000 limits for homes with pools, hot tubs, or properties in high-traffic tourist areas. Your deductible choice directly affects your premium-selecting a $2,500 deductible instead of $500 can reduce your annual premium by 15 to 25 percent, but you must have that cash available when a loss occurs. Most owners benefit from choosing the highest deductible they can comfortably cover out of pocket, since frequent small claims rarely happen in vacation rentals.

Bar chart showing 15% to 25% potential premium reduction from selecting a higher deductible. - vacation rental insurance WA

For loss of rental income coverage, calculate your average nightly rate and multiply it by the typical repair timeline for common disasters in your area-water damage repairs typically require 30 to 60 days, so coverage should reimburse at least 60 days of lost income. Furnished contents coverage should equal your actual replacement cost for all furnishings, electronics, and décor-underestimating this amount leaves you personally liable for replacement costs exceeding your policy limits.

Specialized Carriers Understand Short-Term Rental Risk Better Than Generalists

Not all insurance carriers treat vacation rentals equally. Standard homeowners insurers either exclude vacation rentals entirely or price them at punitive rates because they lack specific underwriting expertise. Carriers specializing in short-term rentals employ underwriters who understand guest turnover, seasonal occupancy patterns, and the specific loss history of furnished properties. These specialists typically offer broader coverage options, more flexible endorsements, and faster claims processing than traditional carriers. When evaluating carriers, ask specifically about their claims response time for vacation rental properties-a 24-hour initial response and same-day adjuster assignment matters when you lose rental income daily. Request sample policies from at least three carriers and compare not just the premium but the actual coverage terms, exclusions, and endorsement costs. Some carriers bundle crime coverage and cyber liability at reasonable rates, while others charge significant add-on fees for protection against guest data theft or payment processor fraud. Verify that any carrier you consider has A.M. Best financial ratings of A or higher, confirming they can actually pay claims if a major loss occurs. Ask about loss-mitigation credits-many carriers reduce premiums 10 to 20 percent if you install security systems, fire extinguishers, or implement guest screening procedures that reduce claim frequency.

Final Thoughts

Vacation rental insurance in WA protects your investment against three critical threats that standard homeowners policies ignore: guest liability claims that reach $100,000 or more, loss of rental income during property repairs, and theft or vandalism of furnished contents. A single serious injury claim or major property damage event can eliminate years of rental profits if you lack proper protection. The coverage gaps are real, and they cost money when claims happen.

Specialized vacation rental insurers understand your actual risk profile far better than traditional homeowners carriers. They process claims faster because they handle vacation rentals constantly, they offer endorsements designed specifically for short-term rental operations, and they provide loss-mitigation credits that reward you for implementing safety measures. When you compare carriers, focus on claims response time, financial stability ratings, and whether they offer discounts for security systems or guest screening procedures.

We at Cross Insurance Agency work with multiple top-rated carriers to find vacation rental coverage that matches your specific property and rental operation. Our licensed agents shop the market on your behalf, compare actual policy terms and exclusions, and help you select coverage limits that protect your investment without overpaying. Contact us to discuss your vacation rental insurance needs and get quotes from carriers that specialize in Washington short-term rentals.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.
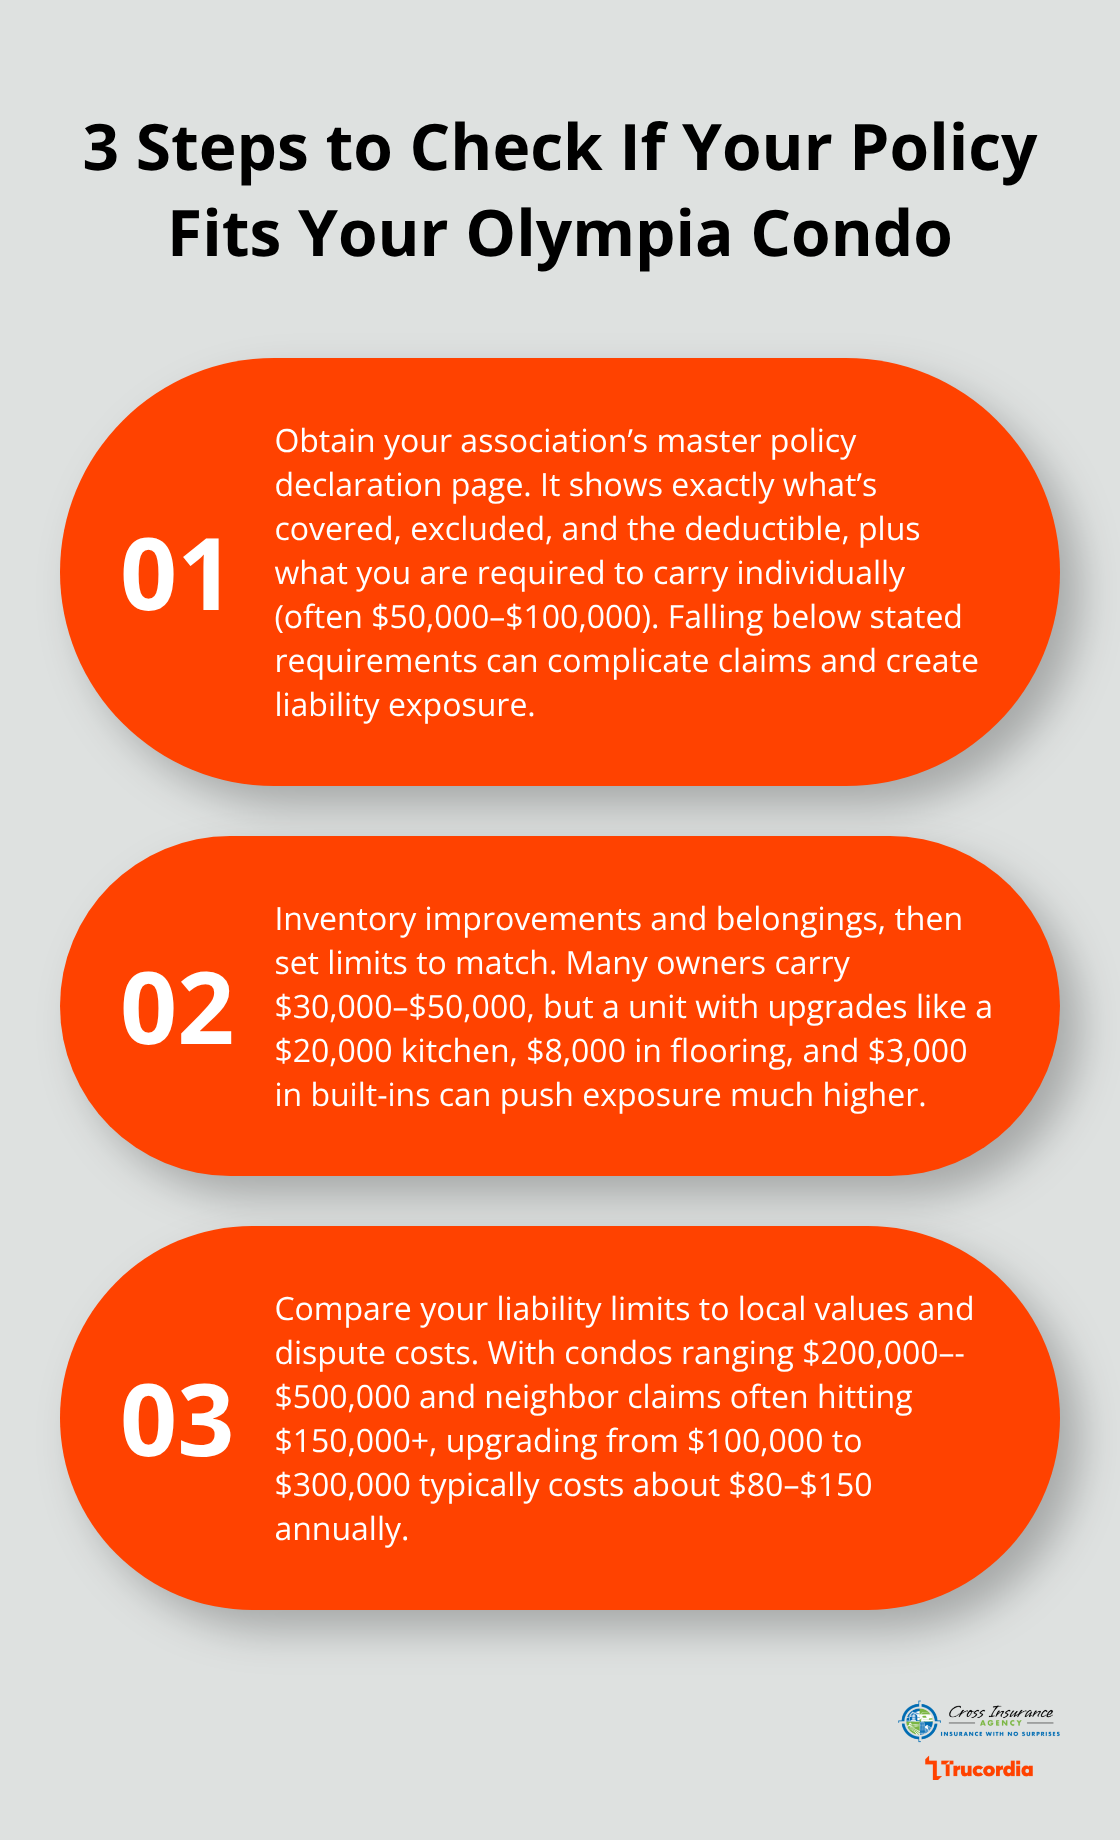
Property managers in Washington face real liability risks every day. From tenant disputes to property damage claims, one mistake can cost thousands.

At Cross Insurance Agency, we’ve helped hundreds of property managers find the right coverage. Property manager insurance in WA isn’t one-size-fits-all-it depends on your specific operations and exposure.

This guide walks you through the coverage types that actually matter, how to spot dangerous gaps, and how to work with a broker who understands Washington’s market.

What Property Managers Actually Need to Insure in Washington

Washington’s Insurance Requirements for Property Managers

Washington doesn’t mandate a single insurance product for property managers, but that doesn’t mean you can operate without coverage. The state requires that property damage liability be addressed, typically through your landlord or commercial property policy. Many property managers mistakenly think their personal auto or homeowners insurance covers business activities-it doesn’t. Washington courts have consistently ruled against coverage claims when property managers operated without proper commercial policies. The Washington State Department of Licensing doesn’t prescribe specific insurance minimums for property managers, which creates a dangerous gray area where managers assume they’re protected when they’re not.

Visual map of key insurance types Washington property managers should consider - property manager insurance WA

Your tenants’ security deposits alone create exposure. If a tenant sues over deposit handling or property condition disputes, personal policies exclude business-related claims entirely. Washington’s Residential Tenancy Act establishes strict rules about deposit accounting, and violating these rules opens you to lawsuits that your personal coverage won’t touch.

General Liability Coverage

General liability insurance protects property managers from bodily injury claims when someone gets hurt on your managed property-a tenant slips on stairs, a visitor sustains injury due to negligent maintenance. Washington property managers typically carry $1 million in general liability limits, though managers handling multiple units or high-value properties often go to $2 million. This coverage is non-negotiable for anyone managing residential or commercial properties in the state.

Property and Umbrella Insurance

Property insurance covers the building structure and contents you’re responsible for, and this is where many managers create gaps by underinsuring. Commercial property coverage costs roughly $500 to $1,500 annually depending on property value and location, but skipping it means paying out-of-pocket for fire, theft, or weather damage. Umbrella insurance sits above your general liability and property coverage, providing additional protection. For a property manager handling five or more rental units, umbrella coverage of $1 million to $2 million costs between $300 and $600 annually and protects against catastrophic claims that exceed your base policy limits.

Management Liability Insurance

Management liability insurance specifically covers employment practices liability, which protects you if a tenant or employee claims discrimination or wrongful termination-this is increasingly important in Washington’s employment-focused legal environment. This coverage addresses gaps that general liability policies leave open. Understanding which coverage types work together helps you build a protection strategy that actually matches your operation.

Essential Coverage Types for Property Managers and Landlords

General Liability Insurance: Your First Line of Defense

General liability insurance protects property managers when a tenant or visitor gets injured on a managed property due to negligent maintenance or unsafe conditions. Washington property managers shouldn’t treat this coverage as optional, and the National Association of Residential Property Managers reports that property managers typically carry $1 million in general liability limits-the practical minimum for managing multiple units. A slip-and-fall claim in Washington averages $40,000 to $100,000 in legal costs alone before any settlement, which means inadequate limits ($300,000 or $500,000) leave you exposed to catastrophic personal liability.

If you manage five or more residential properties, you need $2 million in general liability coverage. This higher limit protects you against the compounding risk that comes with managing multiple properties and multiple tenants across different locations.

Property Insurance: Closing the Coverage Gap

Property insurance for buildings and contents creates dangerous gaps when managers underinsure or assume their landlord’s policy covers their liability. Commercial property coverage runs $500 to $1,500 annually depending on property value and location, but skipping it means you personally pay for fire, theft, weather damage, or vandalism. Washington’s seasonal weather patterns-heavy rain, wind damage, occasional snow-make property insurance non-negotiable for anyone managing residential or commercial properties in the state.

Many managers mistakenly believe their landlord’s policy protects their management liability. That assumption costs thousands when claims arise. You need your own commercial property policy to cover your specific exposure.

Umbrella Coverage for Catastrophic Protection

Umbrella coverage sits above your general liability and property policies, providing additional protection when claims exceed your base limits. A $1 million umbrella policy costs between $300 and $600 annually and protects against catastrophic claims that could otherwise wipe out your personal assets. For property managers handling high-value properties or managing ten or more units, $2 million in umbrella coverage becomes standard practice.

The combination of $1 million general liability, adequate property coverage, and $1 million to $2 million umbrella protection creates a solid foundation that matches real exposure in Washington’s competitive rental market. This layered approach means that when one policy reaches its limit, the next policy activates to cover additional damages.

Compact list outlining a layered insurance setup for Washington property managers

Management Liability: Employment and Discrimination Protection

Management liability insurance specifically covers employment practices liability, protecting you if a tenant or employee claims discrimination or wrongful termination. This coverage addresses gaps that general liability policies leave open, and it’s increasingly important in Washington’s employment-focused legal environment. Without this protection, you face legal defense costs and settlements that your standard policies won’t cover.

Understanding which coverage types work together helps you build a protection strategy that actually matches your operation. The next step involves identifying which carrier and broker can deliver these policies at competitive rates while providing local expertise.

Finding the Right Insurance Partner in Washington

Property managers in Washington have three ways to buy insurance: online direct carriers, national brokers with local offices, and independent brokers who focus on Washington markets. Online carriers offer cheap quotes but won’t understand your specific exposure as a property manager handling multiple units or mixed residential-commercial properties. National brokers with local offices employ agents who work for the carrier first and your interests second, which means they’ll push their own products rather than shopping competitive options. Independent brokers operate differently-they represent you, not the insurance company, and they shop multiple carriers to find coverage that matches your actual operation and budget.

Shopping Carriers Requires Identical Information

Shopping carriers means you provide the same information to multiple insurers so you can compare apples to apples. Request quotes for identical coverage limits (general liability $1 million or $2 million, property coverage matching your building values, and umbrella limits) from at least three carriers. You’ll notice dramatic price differences-sometimes $800 to $1,200 annually for identical coverage-which happens because carriers price risk differently based on their underwriting philosophy and claims history with property managers.

Some carriers specialize in residential property management and offer better rates than carriers focused on commercial real estate. Others charge premiums for managing properties in certain Washington zip codes or neighborhoods. Don’t pick the lowest quote automatically. A carrier quoting $600 annually might deny a claim because their underwriters excluded your specific management activities, while a carrier charging $900 delivers claims support when you need it. Request references from the carrier about their claims process for property managers, not just their premium price.

Local Brokers Know Washington’s Market Realities

A broker who understands Washington’s rental market knows which carriers offer competitive rates for property managers in Seattle versus Spokane, which insurers accept older apartment buildings without charging massive premiums, and which carriers move quickly on claims when a tenant injury lawsuit arrives. Local brokers also understand Washington’s employment laws, which affect your management liability coverage needs-discrimination claims in Washington carry higher costs than in other states because Washington courts award larger settlements.

When you work with an independent broker in Washington, they handle the paperwork, follow up with carriers on quotes, and advocate for you if a claim gets denied. This costs nothing extra because brokers earn commissions from insurers, not from you. National brokers and online platforms don’t provide this advocacy, which means you’re alone if a carrier disputes your claim.

Bundling Saves Money Without Sacrificing Coverage

Property managers who bundle commercial property, general liability, umbrella coverage, and management liability with one carrier typically save 15 to 25 percent compared to buying policies separately from different insurers. A property manager paying $1,200 for general liability, $800 for property coverage, and $400 for umbrella from three different carriers might pay $1,800 to $2,000 total when bundling everything with one carrier. That’s real savings-$400 to $600 annually-without reducing coverage limits.

Percentage chart showing typical bundling discounts for property managers in Washington - property manager insurance WA

However, bundling only makes sense if the bundled rates remain competitive with what you’d pay shopping separately. If a carrier offers a bundled price of $2,400 when you can get identical coverage for $2,100 by mixing carriers, skip the bundle. Some property managers also bundle their personal auto or homeowners insurance with their commercial policies, which can unlock additional discounts of 5 to 10 percent. Just verify that bundling doesn’t lock you into a carrier with weaker property management experience-the discount isn’t worth it if claims handling suffers.

Final Thoughts

Property manager insurance in WA protects your business from the liability risks that come with managing residential or commercial properties. The coverage types we’ve outlined-general liability, property insurance, umbrella protection, and management liability-work together to address the real exposures you face daily. Without these policies, a single tenant injury claim or property damage incident costs you tens of thousands in legal fees and settlements that your personal insurance won’t cover.

Getting properly protected requires three concrete steps. First, count the number of properties you manage, their values, and the types of tenants you work with to determine your actual exposure. Second, request quotes for identical coverage limits from at least three carriers so you can compare pricing without confusion. Third, work with a broker who understands Washington’s rental market and advocates for you if a claim gets denied.

Local expertise matters in Washington because carriers price risk differently based on neighborhood, property age, and management practices specific to our state. A broker operating in Washington knows which insurers offer competitive rates for property managers in Seattle versus Spokane and how Washington’s employment laws affect your management liability needs. Contact Cross Insurance Agency to discuss your property manager insurance WA needs and get competitive quotes for the coverage that matters.

Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.