
Renters Insurance Olympia WA: Affordable Protection for Renters and Landlords
Renters in Olympia, WA often overlook one critical gap in their protection: a landlord’s insurance policy doesn’t cover your personal belongings or liability. We at Cross Insurance Agency see this mistake repeatedly, and it leaves renters vulnerable to significant financial loss.
The good news is that renters insurance in Olympia, WA is affordable and straightforward to obtain. This guide walks you through what coverage you actually need and how to find the best rates for your situation.
Why Your Landlord’s Insurance Won’t Protect Your Stuff
Your landlord’s insurance policy covers the building structure, the roof, and the walls-nothing more. It does not cover your personal belongings, and it absolutely does not cover your liability if you cause damage or someone gets injured in your apartment. This is the fundamental reason renters insurance exists, and it’s non-negotiable in Olympia. Renter insurance usually only covers your property’s actual cash value at the time it was damaged, destroyed, or stolen, which means a fire, theft, or water damage can wipe out thousands of dollars of your possessions with zero recovery. Many Olympia landlords now require proof of renters insurance as a lease condition, often asking for at least $100,000 in liability coverage, which tells you how serious this gap is. If a guest slips on your kitchen floor and breaks their leg, your landlord’s policy will not pay their medical bills or legal fees-yours will, if you have liability coverage. Without it, you could face a lawsuit that attaches your wages or bank account.
What Your Personal Property Actually Costs
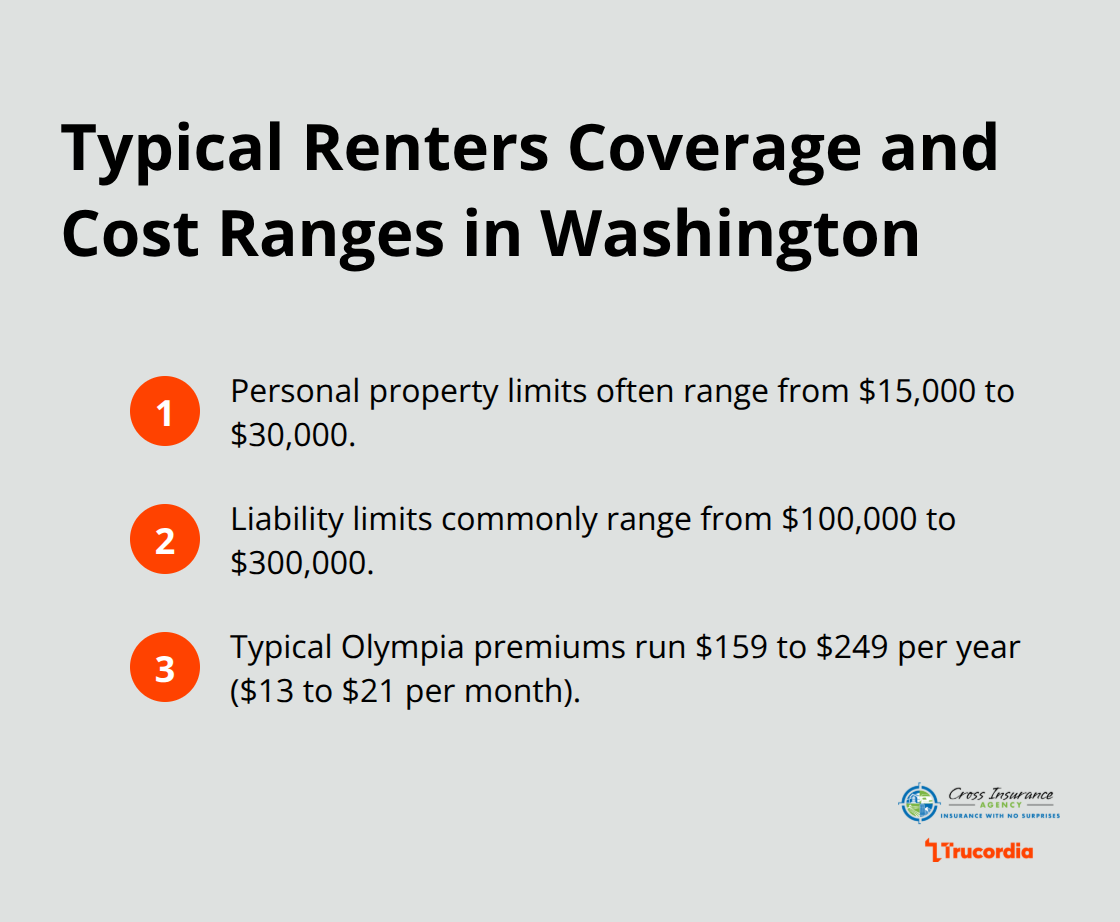
Most renters dramatically underestimate the value of their belongings. Furniture, electronics, clothing, kitchen items, and bedding add up fast. A standard renters policy in Washington typically starts around $15,000 to $30,000 for personal property and $100,000 to $300,000 for liability. If a kitchen fire destroys your apartment, you’ll want replacement cost coverage, not actual cash value, because depreciation will leave you short. In Olympia, renters insurance costs between $159 and $249 per year, placing your monthly cost around $13 to $21, which is less than a coffee subscription.
When You Can’t Stay in Your Apartment
If a covered loss makes your rental uninhabitable, additional living expenses coverage pays for temporary housing, meals, and other reasonable costs while repairs happen. This coverage has saved renters thousands of dollars when a burst pipe, electrical fire, or other disaster forces them out for weeks or months. Without it, you absorb hotel costs, restaurant meals, and storage fees entirely out of pocket. Most policies cover these expenses up to your policy limit, so confirm what your limit is when you obtain a quote. This coverage matters most in scenarios like a kitchen fire in Spokane or a burst pipe in Seattle-real situations that happen to Washington renters regularly. Olympia renters should treat this as a non-negotiable part of their policy, not an optional add-on.
How Liability Coverage Protects Your Financial Future
Liability coverage protects you when someone sues you for injuries or property damage you caused. A guest trips on your stairs and fractures their arm; they file a claim against your renters policy instead of taking you to court personally. Your liability coverage pays their medical expenses and legal fees (up to your policy limit), which shields your paycheck and savings account from attachment. Without this protection, a single lawsuit can cost you tens of thousands of dollars in legal defense alone, even if you win. Olympia renters who host friends, family, or colleagues should view liability coverage as essential protection, not a luxury. The cost to add substantial liability limits remains remarkably low-often just a few dollars more per month than a bare-bones policy.
Taking the Next Step Toward Protection
Now that you understand what your landlord’s policy won’t cover and what renters insurance actually protects, the next step is to compare quotes from multiple carriers and find the coverage limits that match your actual belongings and risk profile.
What Washington Renters Insurance Actually Covers
Personal Property Protection Reimburses Your Belongings
Washington renters policies protect three core areas of your financial life, and understanding exactly what falls under each one prevents nasty surprises when you file a claim. Personal property coverage reimburses you for belongings damaged, destroyed, or stolen up to your policy limit, whether the loss occurs inside your apartment or anywhere else. If your laptop gets stolen from a coffee shop in downtown Olympia or your suitcase gets damaged during a move, this coverage handles it.
Most Washington policies start at $15,000 to $30,000 for personal property, but according to Mosaic Insurance Alliance, many renters underestimate their actual belongings value at $20,000 to $40,000. You should inventory your furniture, electronics, clothing, and kitchen items before you choose a limit. The choice between actual cash value and replacement cost matters significantly: actual cash value pays depreciated amounts, while replacement cost pays what you’d spend today to replace items, costing roughly $2 to $5 more per month but delivering far better protection when major losses occur.
Liability Coverage Shields You from Lawsuits
Liability coverage protects your finances when someone is injured in your rental or you damage their property, and this is where most Olympia renters face their biggest exposure. If a guest slips on your stairs and breaks their leg, your liability coverage pays their medical bills and legal fees up to your policy limit instead of forcing them to sue you personally. Standard policies offer $100,000 to $300,000 in liability limits, and many Olympia landlords now require at least $100,000 as a lease condition, so meeting that threshold is non-negotiable.
Medical Payments Coverage Acts Independently
Medical payments coverage for guests fills a different role than liability: it pays eligible medical expenses for injuries guests sustain in your rental regardless of fault. You don’t have to prove you were responsible for the accident. This coverage typically covers medical treatment up to a set limit per person and per incident, and it moves quickly without requiring the injured person to file a lawsuit.
Additional Living Expenses Keep You Afloat
Additional living expenses coverage rounds out the core protections by paying for temporary housing, meals, and related costs if a covered loss makes your rental uninhabitable while repairs happen. Olympia renters should verify their personal property limit actually matches what they own, because underinsuring leaves you absorbing the gap yourself when disaster strikes.
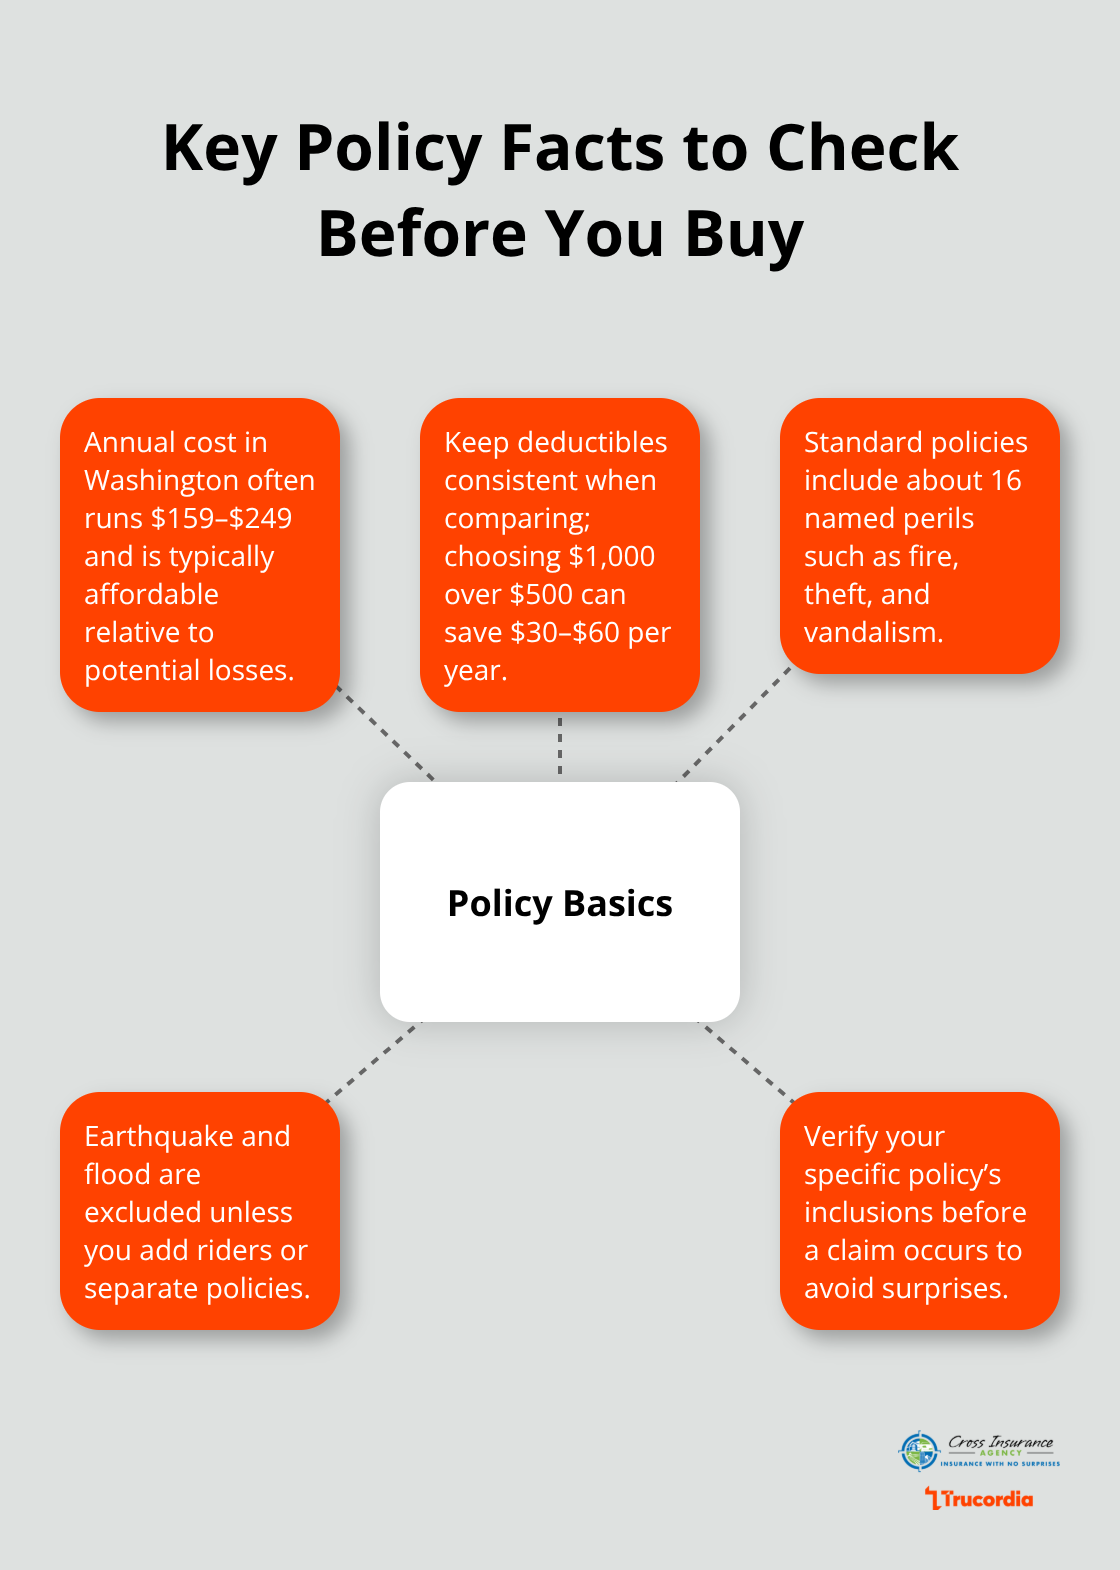
Washington renters insurance costs between $159 and $249 per year according to Mosaic Insurance Alliance, making these three core protections remarkably affordable compared to the financial devastation they prevent. When you compare quotes, keep your deductible consistent across carriers so premiums stay comparable, and choosing a $1,000 deductible instead of $500 typically saves $30 to $60 annually. Standard renters policies cover approximately 16 named perils including fire, theft, and vandalism, but earthquake and flood damage require separate riders or policies. Before you assume you’re covered for every scenario, confirm what your specific policy includes-this distinction becomes critical when you actually need to file a claim.
How to Find the Best Renters Insurance Price in Olympia
Compare Quotes from Multiple Carriers
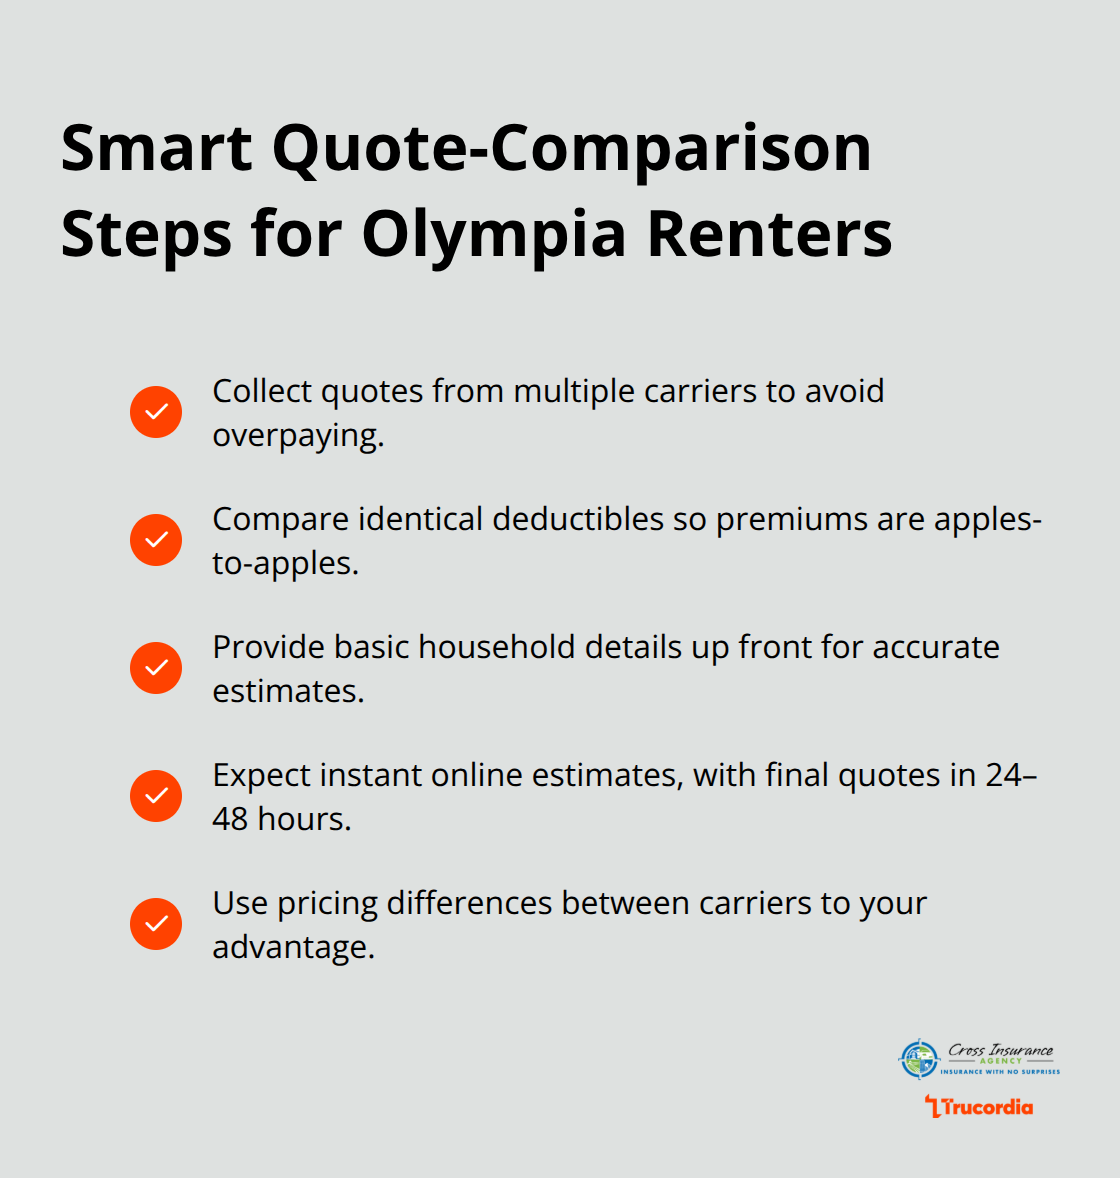
Olympia renters who accept the first quote they receive typically pay 20 to 30 percent more than necessary. Premiums vary dramatically based on how each insurer calculates risk, so a policy costing $18 per month with one carrier might cost $24 with another despite nearly identical coverage. Start your quotes with basic information: your name, date of birth, address, and details about others living with you full-time. Most carriers now offer online quotes that provide estimates immediately, though the full quote process typically takes 24 to 48 hours after submission.
Don’t rely on advertised headline prices, as that $5-per-month figure floating around usually doesn’t apply to your specific Olympia situation. Regional price differences within Washington are substantial; according to Mosaic Insurance Alliance, Seattle-area renters often pay significantly more than Eastern Washington renters due to higher claim frequency and property values. Your credit-based insurance score also matters considerably, so mention recent credit improvements when you compare quotes.
Bundle Auto and Renters Insurance for Substantial Savings
The fastest way to cut your premium is combining renters insurance with auto insurance, which typically saves 10 to 25 percent on both policies. Many Olympia renters overlook this option and purchase renters insurance alone, leaving significant money on the table. When you compare quotes across carriers, keep your deductible consistent so the numbers stay comparable. Choosing a $1,000 deductible instead of $500 usually saves $30 to $60 per year, so calculate what you could actually afford to pay out-of-pocket if a claim occurred.
Select Coverage Options That Match Your Situation
Your choice between actual cash value and replacement cost coverage affects your monthly payment; replacement cost costs roughly $2 to $5 more per month but delivers significantly better payouts when major losses occur (making it worth the small premium increase for most renters). Buying online rather than through an agent typically unlocks an additional discount. Once you narrow your options to two or three carriers, contact an independent agent in Washington who can access multiple insurers and potentially uncover discounts you wouldn’t find shopping alone. These agents work with top-rated carriers and can help you assemble documents needed to show proof of coverage to landlords.
The quote comparison process requires effort, but saving $50 to $100 per year on a policy you’ll carry for years makes that investment worthwhile.
Final Thoughts
Renters insurance in Olympia, WA protects you against the exact financial disasters that landlord policies ignore, and you can obtain comprehensive coverage for $13 to $21 per month. A kitchen fire, a guest’s injury lawsuit, or a burst pipe that forces you out for weeks can cost thousands of dollars in damages, medical bills, and temporary housing expenses-protection that costs less than a streaming subscription. The three core coverages (personal property, liability, and additional living expenses) address real gaps in your financial security, and Washington’s competitive market means you have genuine options to customize coverage around your actual situation.
Your next move is to stop accepting the first quote you receive and instead compare options across multiple carriers, since regional price differences within Washington are substantial and your credit score, deductible choice, and bundling decisions can shift your annual premium by $50 to $100 or more. An independent agent can access multiple top-rated carriers and help you find discounts you wouldn’t discover shopping alone, plus they can assist with assembling proof of coverage documents your landlord requires. We at Cross Insurance Agency connect Olympia renters with tailored coverage from multiple carriers and provide ongoing claims advocacy when you actually need it.
Contact us today to compare quotes and find the right renters insurance policy for your situation.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


