
Property Insurance Centralia WA: Tailored Coverage for Local Homes and Businesses
Property insurance in Centralia, WA protects what matters most-your home or business. Weather threats, fire, theft, and liability risks are real concerns for local property owners.
At Cross Insurance Agency, we help Centralia residents and business owners find coverage that fits their specific needs. The right policy can make the difference between financial security and devastating loss.
Why Property Insurance Matters in Centralia
Centralia property owners face real financial exposure that standard homeowners or business policies often leave unprotected. Median property values in Centralia reached $318,200, which means replacement costs have climbed significantly. A fire, theft, or weather event that damages a property without adequate coverage creates a catastrophic loss that most households cannot absorb.
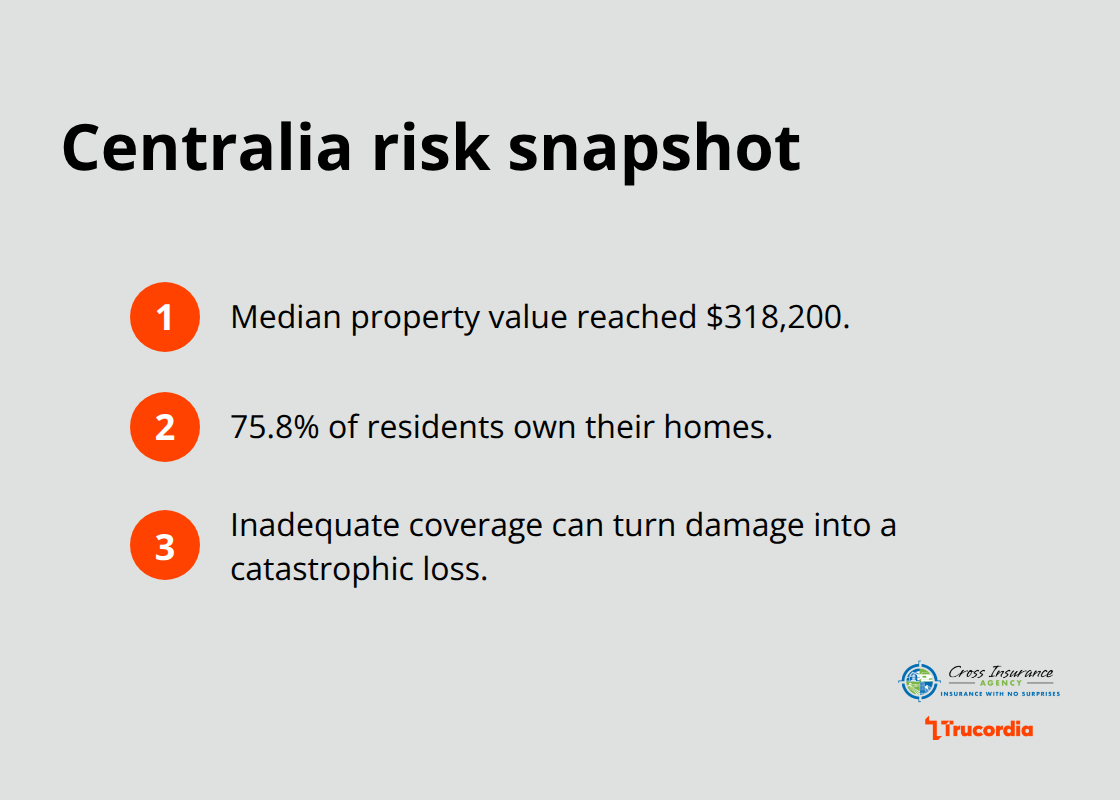
The stakes are particularly high in Centralia because 75.8% of residents own their homes, according to Data USA, making property protection a central financial concern for three out of four households in the community.
Weather and Natural Disaster Risks Are Increasing
Centralia’s location in Washington exposes properties to wind damage, heavy rainfall, and occasional severe storms that compromise roofs, foundations, and structural integrity. Standard homeowners policies cover wind and hail damage, but many property owners underestimate repair costs. A single roof replacement in Washington costs between $15,000 and $25,000 depending on square footage and materials, and deductibles of $1,000 to $2,500 mean you pay that amount out of pocket before coverage activates. Flood damage presents a separate problem entirely-homeowners policies explicitly exclude flood coverage, yet Centralia’s proximity to waterways and seasonal precipitation patterns create genuine flood risk. If you live in or near a flood zone, you must purchase a separate flood insurance policy through the National Flood Insurance Program or a private carrier. Without it, water damage from heavy rain or nearby creek overflow leaves you completely unprotected.
Fire and Theft Protection Secures Your Assets
Fire remains one of the most destructive property threats, and Centralia experiences structure fires that cause six-figure losses. Your homeowners or commercial property policy must include dwelling coverage at full replacement cost, not market value. Many property owners make the mistake of insuring their home at $300,000 when replacement cost actually totals $400,000, which triggers coinsurance penalties that force you to pay a portion of claims out of pocket. For businesses, commercial property insurance covers the building structure and its contents separately, and underinsuring either component creates a dangerous gap. Theft and burglary coverage protects against break-ins and stolen property, but limits vary widely-some policies cap coverage at $2,500 for jewelry or $5,000 for cash, which may not match your actual assets. You should document your possessions with photos and receipts to prove the value of items during a claim.
Legal and Mortgage Requirements Mandate Coverage
Mortgage lenders in Washington require homeowners insurance as a condition of financing, and if you fail to maintain a policy, the lender can force-place coverage on your behalf-which is typically more expensive and offers less protection than a policy you choose yourself. For rental properties, Washington landlords face additional legal exposure because the state’s Residential Tenancy Act strengthens tenant protections, raising liability exposure significantly. A tenant injury claim can exceed $100,000, and standard homeowners policies do not cover rental income loss or tenant-caused damage. If you own rental properties in Centralia, you must carry landlord insurance with adequate liability limits and loss-of-rent coverage. Business owners also face legal mandates-general liability insurance is often required by local permits, lease agreements, or contracts with clients, and skipping this coverage leaves your business vulnerable to lawsuits that can bankrupt the operation.
Understanding these legal requirements and real-world risks shapes what coverage you actually need. The next section examines the specific types of property insurance available in Centralia and how each one addresses different ownership situations.
Coverage Options That Match Your Centralia Property
Homeowners Insurance Fits Your Owner-Occupied Residence
Centralia homeowners access standard homeowners insurance that protects owner-occupied residences with dwelling coverage, personal property protection, and liability limits that typically range from $300,000 to $500,000. The median property value in Centralia is $385,800 according to Data USA, which means many homeowners must verify their dwelling coverage sits at or above full replacement cost rather than market value. You should obtain a professional replacement-cost appraisal or contractor reconstruction estimate before finalizing your policy-this step prevents the coinsurance penalty that strikes when your insured amount falls short of actual replacement costs. If your home’s true replacement cost is $450,000 but you insure it at $350,000, a total loss claim triggers a coinsurance clause that forces you to absorb a percentage of the loss yourself.
Condo owners in Centralia need a different approach entirely because the building structure is typically covered by the condo association’s master policy, leaving you to insure only interior walls, fixtures, and personal property through an HO-6 condo policy. This policy includes liability coverage for accidents that occur within your unit and protects against theft and damage to your belongings.
Commercial Property Insurance Protects Business Assets Separately
Commercial property insurance for Centralia businesses operates on a separate framework that splits building coverage and contents coverage into distinct protection buckets. Many small business owners make the mistake of insuring only the building structure while leaving inventory, equipment, and fixtures severely underinsured, which creates a dangerous gap when a fire or theft occurs. The three largest employers in Centralia are Health Care & Social Assistance with 4,784 jobs, Retail Trade with 4,242 jobs, and Manufacturing with 3,361 jobs according to Data USA, and each sector faces different property risks-hospitals need protection for expensive medical equipment, retail stores need inventory coverage with seasonal fluctuations, and manufacturing facilities require machinery and production-line asset protection.
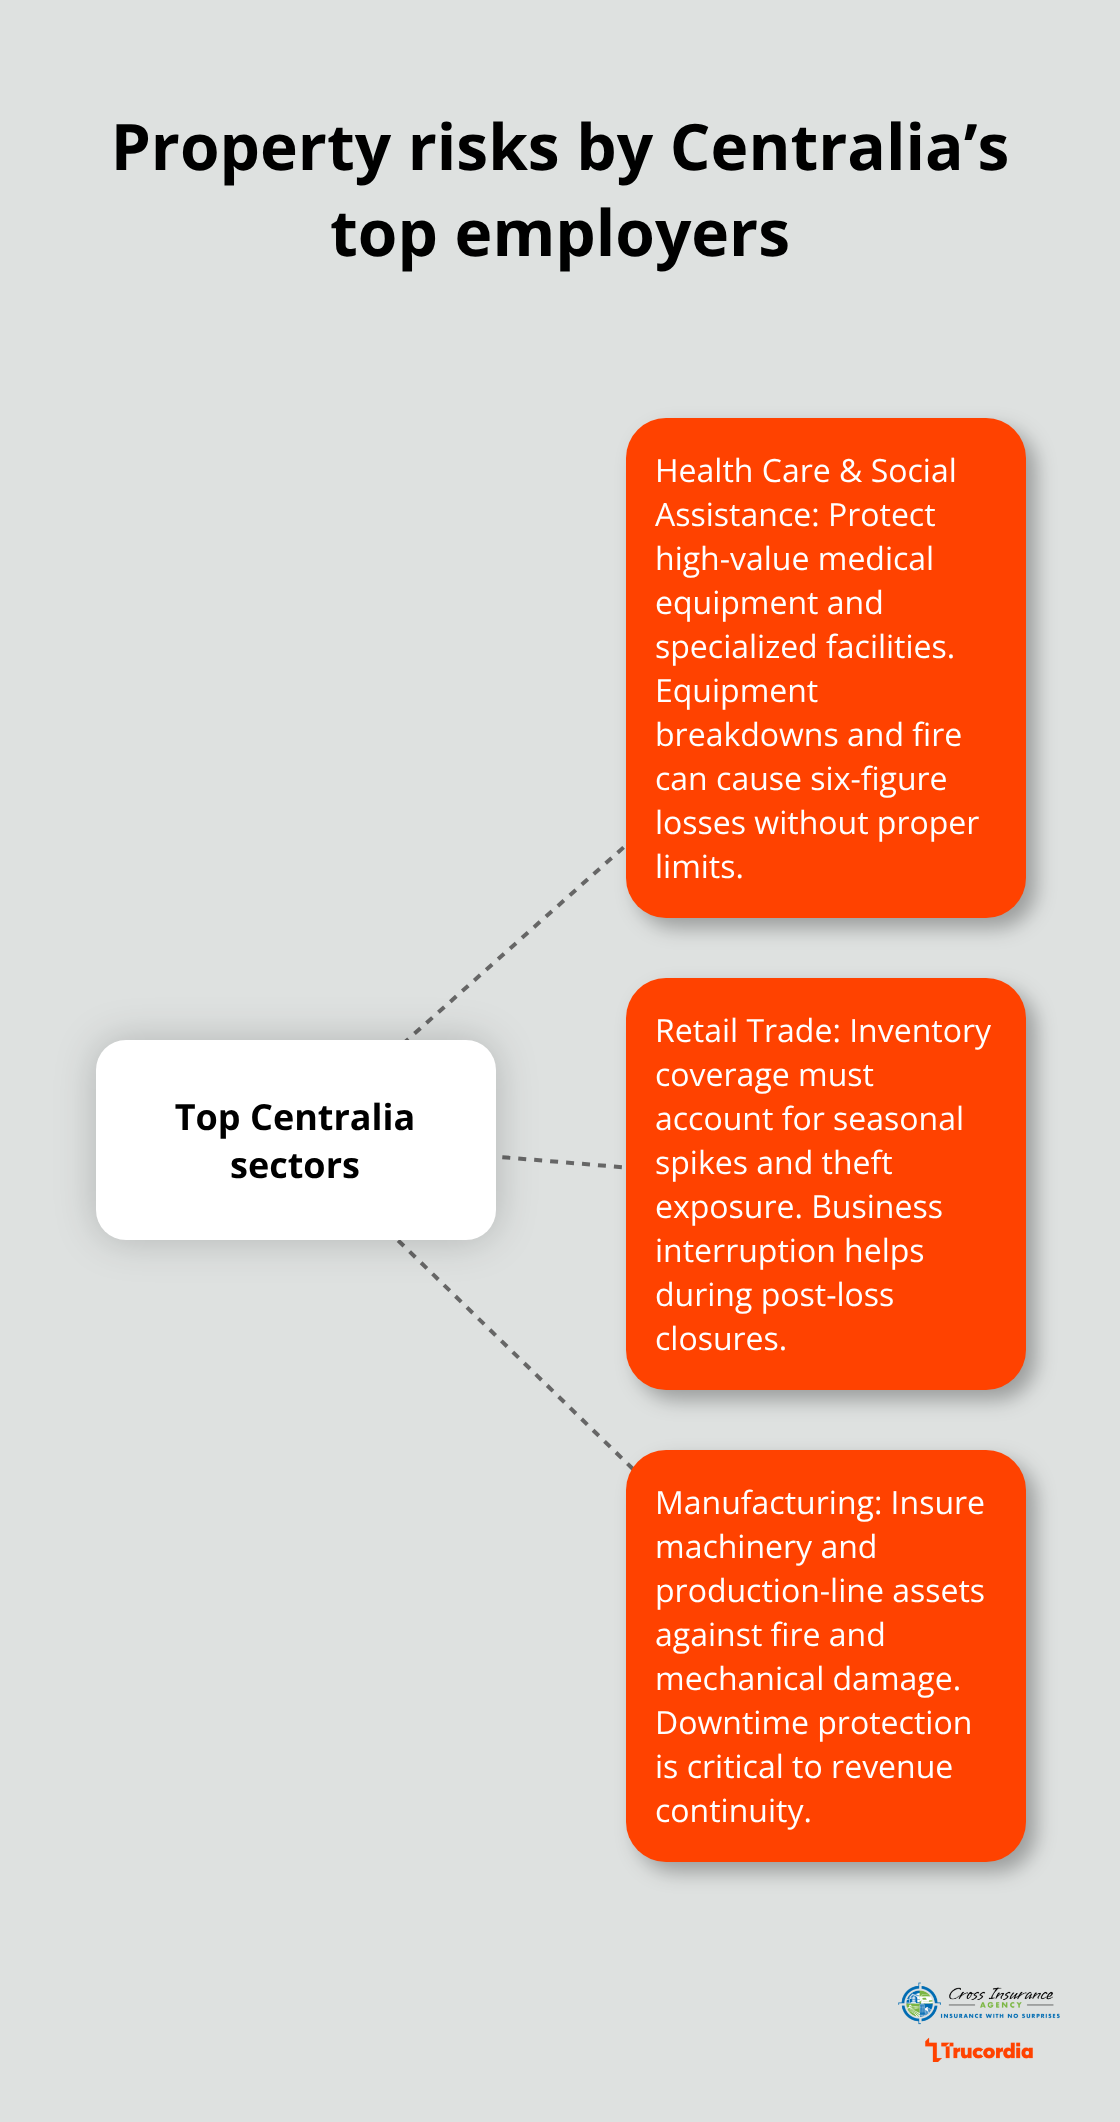
A commercial property policy should include business interruption coverage that reimburses lost income when fire, theft, or weather damage forces you to close temporarily, which becomes critical during the 30 to 90 day repair periods that are common in Washington.
Scheduled Coverage Protects High-Value Assets
For high-value assets like jewelry collections, fine art, or expensive equipment, standard homeowners or commercial policies impose sublimits that cap coverage far below actual value-jewelry might be limited to $2,500 and cash to $5,000. Scheduled personal property endorsements remove these sublimits for specifically listed items, and insurers typically require appraisals or receipts for items valued above $5,000 to establish proof of value before a claim occurs. Centralia business owners with specialized equipment or inventory should request quotes that include agreed-value provisions, which lock in the replacement cost at policy inception and prevent disputes over value during claims.
Comparing Carriers Reveals Your Best Protection Match
The independent agency model allows agents to compare these coverage variations across multiple top-rated carriers, ensuring you pay for protection that actually matches your assets rather than overpaying for unnecessary coverage or accepting dangerous gaps. When you request quotes from different carriers, you’ll notice that building coverage, contents limits, and business interruption options vary significantly-some insurers offer extended replacement cost up to 125% of your insured amount, while others cap it at 100%. You should document your property details (square footage, construction type, year built, roof condition, upgrades) because these factors directly affect pricing and coverage needs. Obtaining quotes from at least three carriers with identical coverage limits and deductibles reveals which insurers offer the best value for your specific situation.
The next section walks you through the process of selecting the right policy by assessing your actual coverage needs and understanding how deductibles and limits work together to protect your financial security.
How to Choose the Right Property Insurance Policy
Start with a Professional Replacement-Cost Appraisal
A professional replacement-cost appraisal for your Centralia home or business beats guessing at coverage needs. The median property value in Centralia reached $385,800 according to Data USA, yet market value and replacement cost diverge significantly-a home worth $385,000 on the market might cost $420,000 to rebuild after a total loss because construction labor and materials exceed what you’d receive selling the property. Contact local contractors or use the replacement-cost calculator from the National Association of Insurance Commissioners to document square footage, construction type, roof condition, and any recent upgrades. Many Centralia property owners insure their homes at 80% of replacement cost to save on premiums, but this strategy backfires through coinsurance penalties that force you to pay a percentage of claims yourself.
If your actual replacement cost is $400,000 and you insure it at only $300,000, the insurer calculates your loss reimbursement based on the shortfall-a $100,000 fire damage claim might result in you absorbing $25,000 out of pocket. For commercial properties, document building square footage separately from contents value, then request quotes that specify building coverage at full replacement cost and contents coverage based on your inventory turnover and seasonal fluctuations. Small manufacturers in Centralia with 3,361 jobs in the sector according to Data USA should photograph equipment and machinery to establish agreed values before a claim occurs, preventing disputes over replacement cost later.
Compare Quotes from Multiple Carriers with Identical Terms
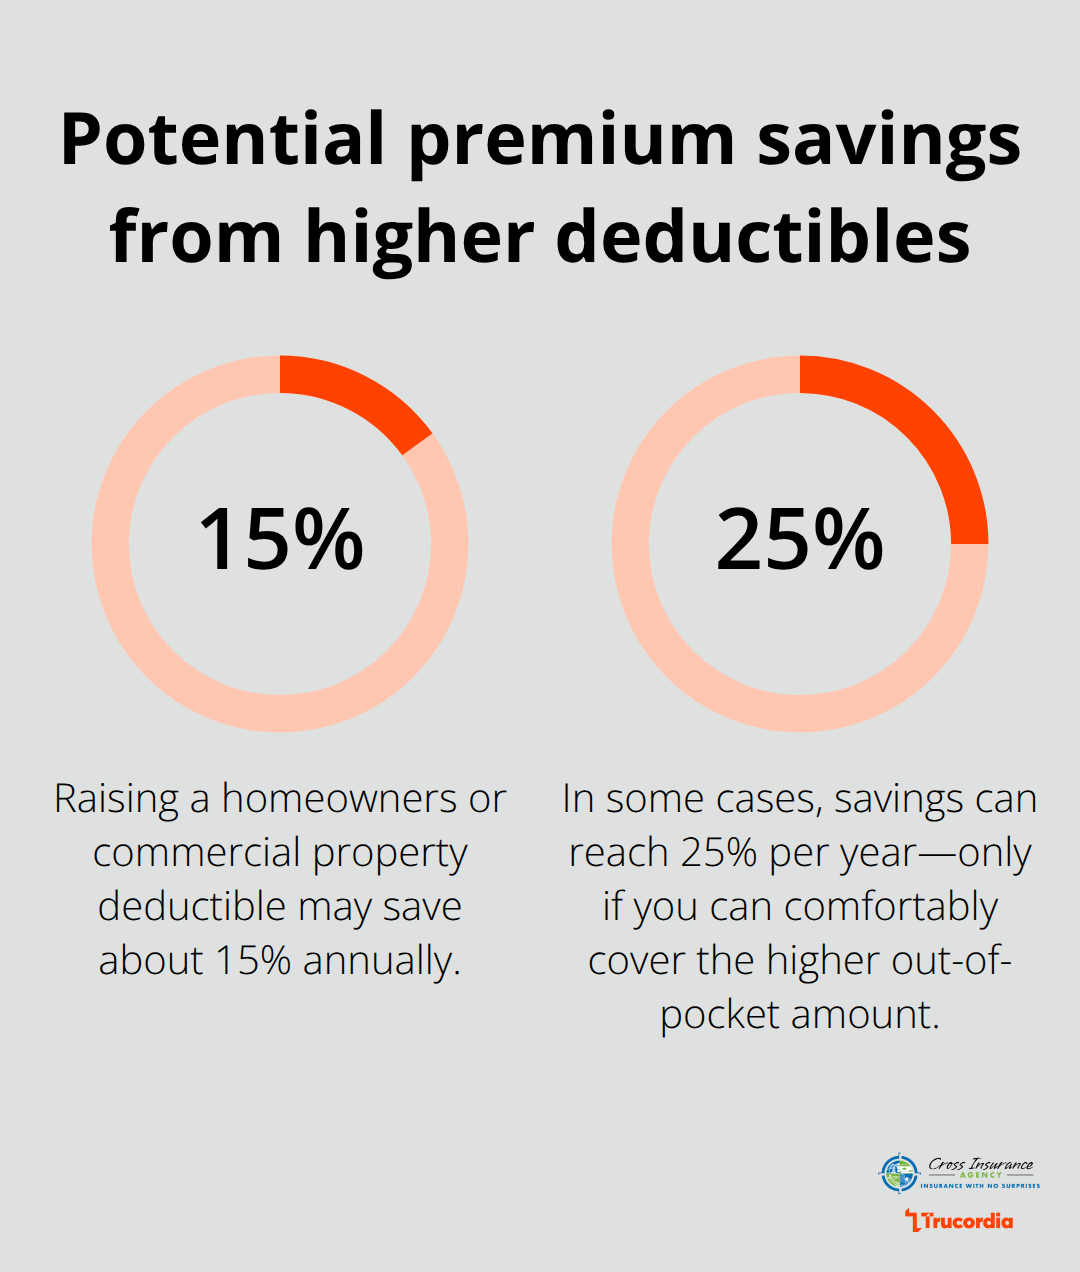
Quotes from at least three carriers with identical coverage limits, deductibles, and protection types reveal pricing differences that reflect actual carrier variation rather than coverage gaps. Request that each quote include standard homeowners or commercial property coverage plus optional protections like extended replacement cost up to 125%, business interruption coverage that extends beyond 30 days, and scheduled endorsements for high-value items. Deductibles typically range from $500 to $2,500 for homeowners policies and $1,000 to $5,000 for commercial properties-raising your deductible from $1,000 to $2,500 might save 15% to 25% annually, but only if you can absorb that amount from emergency savings without financial strain.
Washington landlords should demand loss-of-rent coverage that extends 60 days minimum since evictions in the state typically consume 30 to 90 days, and a two-month rent loss on a $2,000 monthly rental equals $4,000 in unprotected income. An independent agent who shops multiple top-rated carriers can identify bundling discounts that reduce overall premium costs when you combine auto, home, and business coverage with one carrier or across multiple insurers.
Evaluate Carrier Strength and Claims Performance
Financial strength ratings from A.M. Best or J.D. Power matter more than you might think-an inexpensive policy from a carrier with weak claims-handling reputation becomes worthless when you file a claim and face delays or denials. Review these ratings before finalizing your choice to confirm the insurer can actually pay claims when disaster strikes. Centralia residents benefit from working with independent agents who maintain relationships with top-rated carriers and can advocate for you during the claims process, ensuring faster resolution and fair treatment when you need it most.
Final Thoughts
Property insurance in Centralia, WA protects your financial future when fire, theft, weather, or liability strikes. You must obtain a professional replacement-cost appraisal to avoid coinsurance penalties, compare quotes from multiple carriers with identical coverage terms, and verify that your policy covers all protection gaps that standard homeowners or commercial policies typically miss. Centralia’s median property value of $385,800 and 75.8% homeownership rate mean most residents carry significant financial exposure, and underinsurance forces you to absorb losses out of pocket when claims occur.
Document your property details including square footage, construction type, roof condition, and any recent upgrades, then request quotes from at least three carriers. For homeowners, verify dwelling coverage sits at full replacement cost, not market value. For rental properties, demand loss-of-rent coverage extending 60 days minimum since Washington evictions typically consume 30 to 90 days, and for businesses, split building and contents coverage into separate protection buckets while including business interruption coverage that reimburses lost income during repairs.
Local expertise matters because Centralia property owners face specific risks that generic national policies often miss-an independent agent who understands Washington’s Residential Tenancy Act, local eviction timelines, seasonal weather patterns, and the unique exposures facing health care, retail, and manufacturing businesses identifies coverage gaps that cost you thousands during claims. At Cross Insurance Agency, we shop multiple top-rated carriers to deliver choice, bundling discounts, and personalized guidance tailored to your actual situation. Contact us today to secure property insurance Centralia WA that protects what matters most.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


