
Smart Ways to Find Cheap Auto Insurance Olympia
Auto insurance in Olympia doesn’t have to drain your budget. We at Cross Insurance Agency know that finding cheap auto insurance in Olympia means knowing where to look and what questions to ask.
The right strategy combines comparison shopping, smart discounts, and understanding what actually drives your rates. This guide walks you through proven methods to lower your premiums without sacrificing coverage.
How to Compare Auto Insurance Quotes the Right Way
Getting quotes from multiple insurers is the fastest way to cut your Olympia auto insurance bill, but most people stop too early in the process. Customers often grab the first three quotes they find and call it done, leaving hundreds of dollars on the table each year. The real work happens when you examine what each quote actually covers and why the prices differ so dramatically. Insurance companies price policies differently based on how they weigh risk factors, so a quote that looks cheap from one carrier might exclude coverage you need or apply stricter underwriting standards that affect future claims.
You need at least three quotes to spot real savings, but more importantly, you need to understand what makes each one different. Start with online quote tools from major carriers like State Farm, Geico, and Progressive to gather baseline numbers quickly, then add quotes from regional carriers that often compete aggressively on price in Washington state. This process takes roughly 20 to 30 minutes total, and the time investment pays off immediately when you see price variations of $400 to $800 annually for identical drivers and vehicles.
Coverage levels determine your actual protection
Once you have your quotes lined up, stop comparing just the premium amounts. The real comparison happens when you compare auto insurance quotes at identical coverage levels. A deductible may apply when you use collision coverage or comprehensive coverage, which will reimburse you for loss due to theft or damage caused. A quote that’s $50 cheaper per month often comes with a $1,500 deductible instead of $500, which means you’ll pay more out-of-pocket when you actually need to file a claim.
Washington state requires minimum liability coverage of 25/50/25 (meaning $25,000 bodily injury per person, $50,000 total per accident, and $25,000 property damage), but that bare minimum leaves you exposed if you cause serious injuries. Most Olympia drivers should carry at least 100/300/100 coverage, and comparing quotes at the same coverage level reveals which insurers actually offer the best rates for protection you’ll use.
Add-ons and bundled features shift the real cost
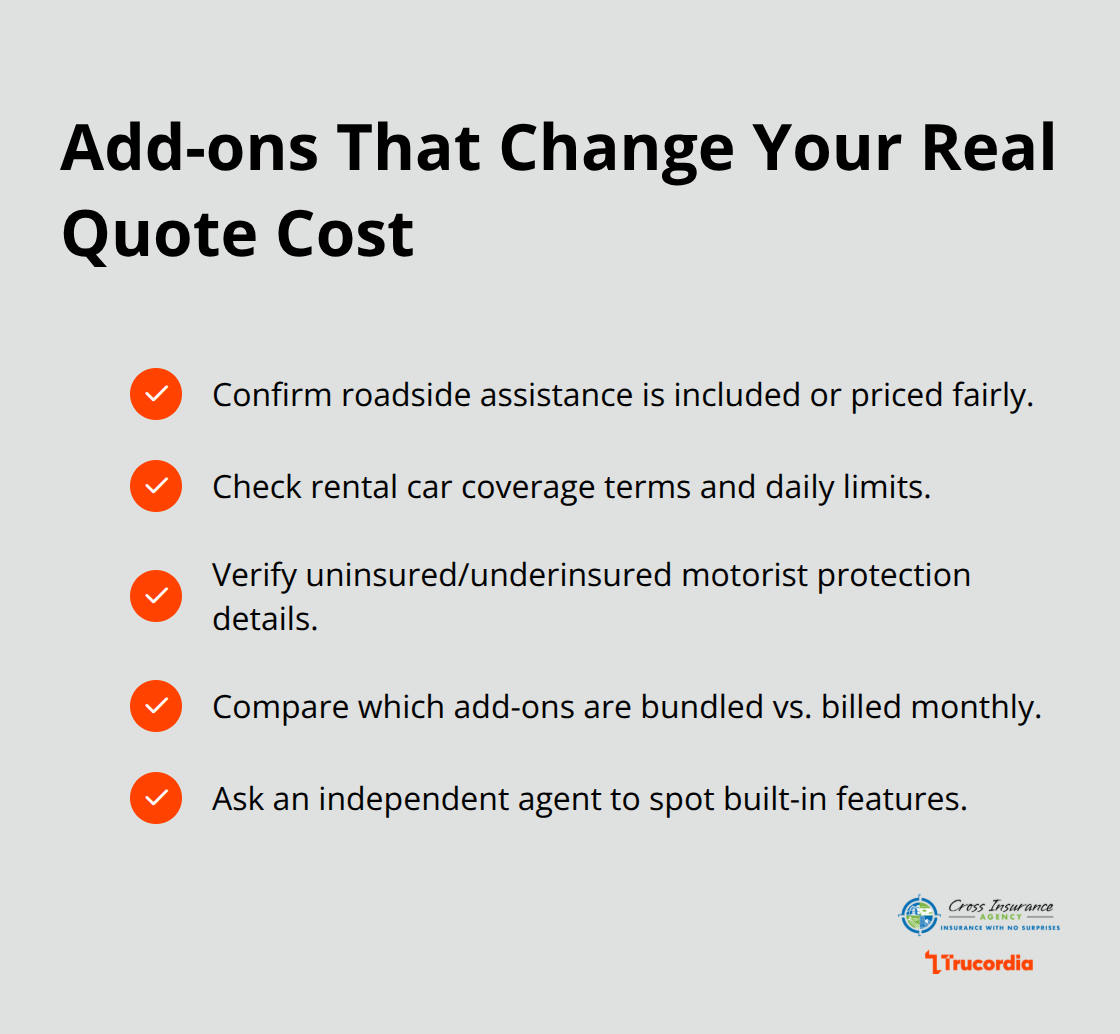
Look at whether quotes include roadside assistance, rental car coverage, and uninsured motorist protection, since some carriers bundle these at no extra cost while others charge $10 to $20 monthly for each add-on. The cheapest quote means nothing if it forces you to add $30 in optional coverages to match what competitors include in their base packages. This is where independent agents who shop multiple carriers become valuable-they identify which insurers bundle features that match your actual needs without padding your bill.
Where Hidden Discounts Add Up Fast
Stack Multiple Policies for Maximum Savings
Bundling policies remains the single most effective way to slash your Olympia auto insurance costs, yet most drivers leave this money on the table. Insurance companies offer bundle discounts when you combine auto, homeowners, or renters coverage with the same carrier. A driver paying $1,200 annually for auto insurance alone could save $180 to $300 by adding homeowners coverage to the same policy.
Carriers reward customer loyalty across multiple products because it reduces their administrative costs and locks you in as a long-term client. When you shop for quotes, ask each insurer what their bundle discount percentages are, then calculate the total household premium rather than just the auto insurance line item. This single step often reveals that a carrier appearing expensive for auto alone becomes the cheapest option overall once bundling is factored in.
Target Discounts Based on Your Driving Habits
Low-mileage discounts apply if you drive fewer than 10,000 to 15,000 miles annually, and some carriers offer usage-based programs that track your actual driving patterns and reward safe behavior with discounts up to 30%. These programs work by monitoring acceleration, braking, and time of day you drive, then translating that data into real premium reductions. If you commute short distances or work from home several days weekly, this discount alone could cut 10% to 15% from your annual bill.
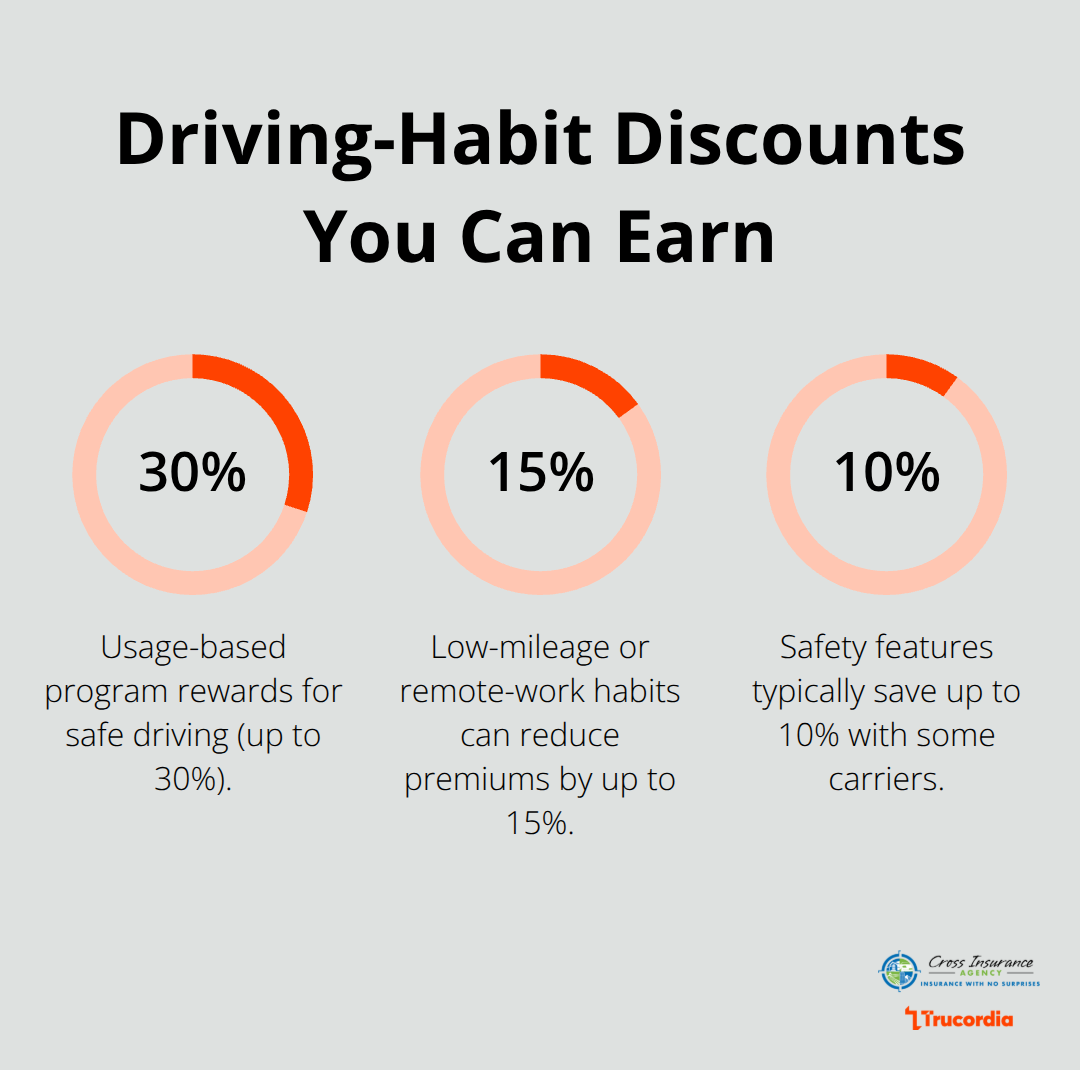
Safety feature discounts reward you for having anti-theft devices, anti-lock brakes, or electronic stability control, typically saving 5% to 10% on your premium. Modern vehicles often come equipped with these features standard, so verify that your insurer recognizes them and applies the discount automatically. If your vehicle qualifies for multiple safety discounts, some carriers stack them while others cap the total benefit, so requesting a detailed breakdown prevents overpayment.
Loyalty Rewards and Stacking Strategies
Ask your current insurer about loyalty discounts after three to five years of continuous coverage, as many carriers offer 10% to 15% reductions for customers who stay put. These discounts accumulate quietly on your policy unless you specifically request them, which means thousands of Olympia drivers miss out simply because they never asked.
The critical difference between drivers who pay too much and those who get genuinely cheap insurance comes down to this: they actively ask about every discount their carrier offers and verify which discounts stack together. Some insurers cap stacking while others allow multiple discounts to combine, so requesting a detailed breakdown of available discounts before committing to any policy prevents surprise overpayment. Independent agents who shop multiple carriers identify which insurers bundle features that match your actual needs without padding your bill and ensure you capture every available discount.
Understanding what actually drives your rates matters just as much as finding discounts, since some factors you can control while others you cannot.
What Actually Drives Your Insurance Costs
Your Driving Record Sets Your Rate Foundation
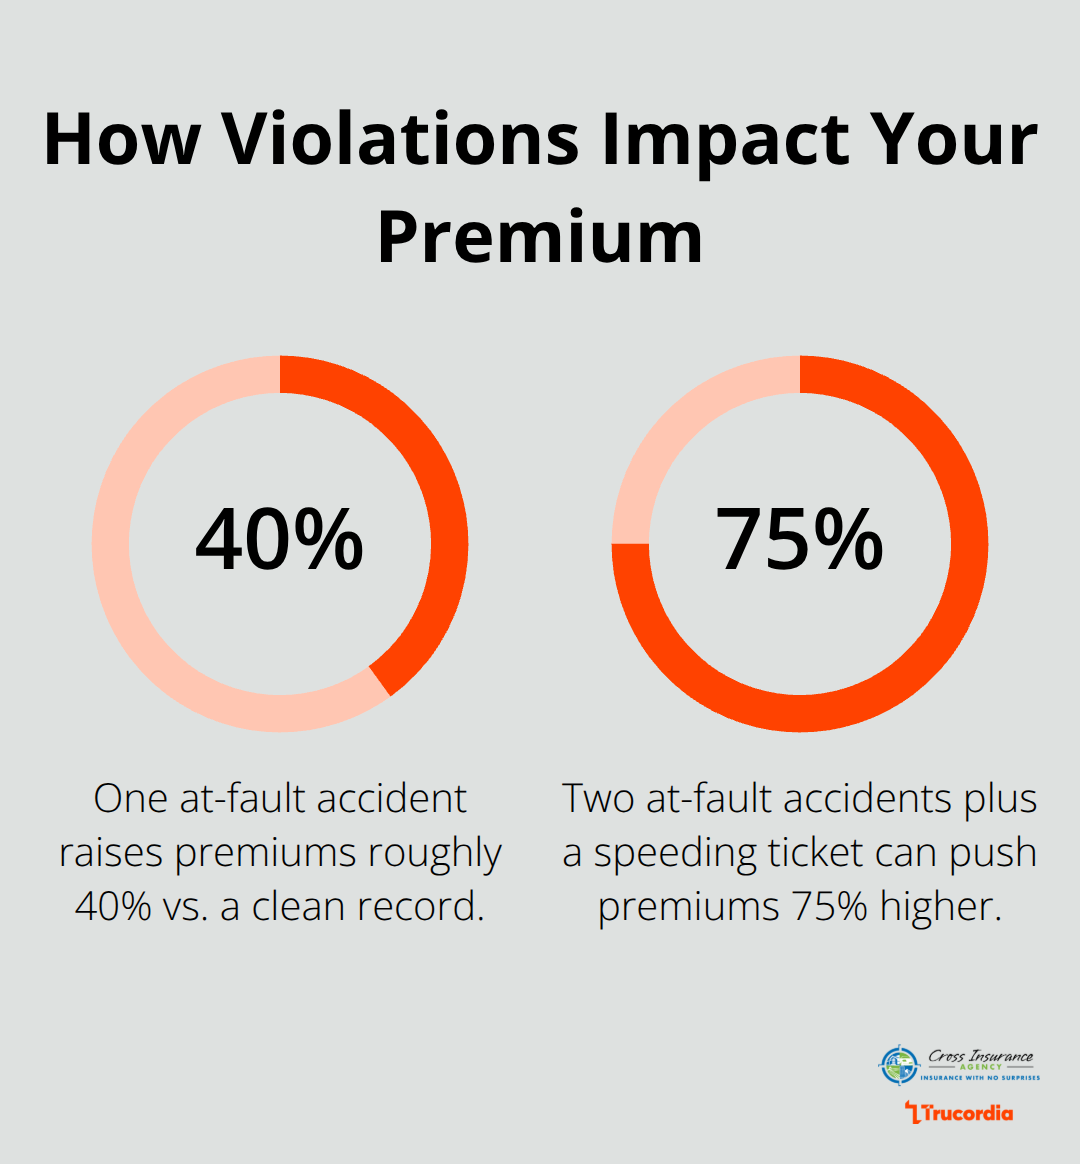
Your driving record remains the single largest factor controlling your Olympia auto insurance rate, and the impact is severe enough that it should shape your driving decisions today. Insurance companies assign rates based on your claims history and violations over the past three to five years, with a single at-fault accident typically adding $400 to $600 annually to your premium, while a speeding ticket costs $150 to $300 per year depending on the violation severity. According to the Insurance Information Institute, drivers with one accident pay roughly 40% more than drivers with clean records, and multiple violations compound dramatically-a driver with two at-fault accidents and a speeding ticket could face premiums 75% higher than baseline rates.
The harsh reality is that your driving record impacts your insurance rate directly determines what you pay today, which means the cheapest insurance strategy involves not getting tickets or causing accidents rather than hunting for discounts.
Vehicle Type and Age Impact Your Premium
Your vehicle choice matters almost equally, since insurance companies charge significantly more for sports cars, luxury vehicles, and models with expensive repair costs compared to sedans and economy vehicles. A 2024 Honda Accord costs roughly 30% less to insure than a 2024 Dodge Charger, and older vehicles often become cheaper to insure despite higher repair costs because replacement value decreases as the car ages. Comprehensive and collision coverage specifically ties directly to your vehicle’s market value, which means a five-year-old Toyota costs considerably less to insure comprehensively than a brand-new model. Age of your vehicle matters more than most drivers realize because insurance companies tie repair expenses to current replacement parts availability and labor costs.
Coverage Limits and Deductibles Give You Control
Coverage limits and deductible selection represent the only rate factors you control directly, and these choices determine what you actually pay versus what the insurance company pays when you file a claim. Raising your deductible from $500 to $1,000 typically cuts your collision and comprehensive premiums by 15% to 25% annually, yet this strategy only works if you maintain an emergency fund to cover the higher out-of-pocket cost when damage occurs. Calculate your actual emergency savings before raising deductibles, since saving $200 per year means nothing if an accident forces you into credit card debt because you cannot afford the $1,500 deductible.
Liability coverage limits operate differently-increasing from state minimum 25/50/25 to 100/300/100 costs only $10 to $20 more monthly but protects your assets far better if you cause serious injuries. A lawsuit following a severe accident can exceed $500,000 in damages, and state minimum coverage leaves you personally liable for everything above that threshold, making higher liability limits genuinely inexpensive protection rather than optional extras. Your coverage decisions should reflect your actual situation rather than generic advice, which means comparing total out-of-pocket risk against premium savings before finalizing any deductible or coverage limit changes.
Final Thoughts
Finding cheap auto insurance in Olympia requires three concrete actions: comparing quotes at identical coverage levels across multiple carriers, stacking every discount your situation qualifies for, and understanding which rate factors you can actually control. The drivers who pay the least aren’t necessarily the safest or wealthiest-they’re simply the ones who took time to shop properly and asked their insurers direct questions about bundling, loyalty rewards, and safety feature discounts. Your driving record and vehicle choice set your baseline rate, but your deductible and coverage limit decisions determine whether you’re actually protected or just paying for a policy number.
Gather quotes from at least three different carriers this week, then compare them side-by-side at the same coverage levels rather than just looking at the cheapest monthly premium. Request specific discount percentages from each insurer, calculate your total household cost if you bundle multiple policies, and verify which discounts stack together before committing to any carrier. This process takes roughly 30 minutes and typically saves $300 to $600 annually compared to renewing your current policy without shopping.
We at Cross Insurance Agency work with multiple top-rated carriers on your behalf, which eliminates the legwork while helping you capture discounts you might miss on your own. Our licensed agents understand Washington’s specific insurance requirements and local market rates, so we identify which carriers offer the best combination of price and coverage for your actual situation. Contact Cross Insurance Agency to get personalized quotes tailored to your Olympia location and driving profile-we handle the comparison shopping so you get genuine savings without the hassle.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


