
Olympia Car Insurance Quotes: Local Rates From Trusted Agents
Finding the right Olympia car insurance quotes takes time, but it doesn’t have to be complicated. We at Cross Insurance Agency work with drivers every day to match them with coverage that fits their needs and budget.
Local agents understand Washington’s specific requirements and can spot discounts you might miss online. Let’s walk through how to find the best rates and get the protection your vehicle deserves.
How Your Olympia Quote Gets Built
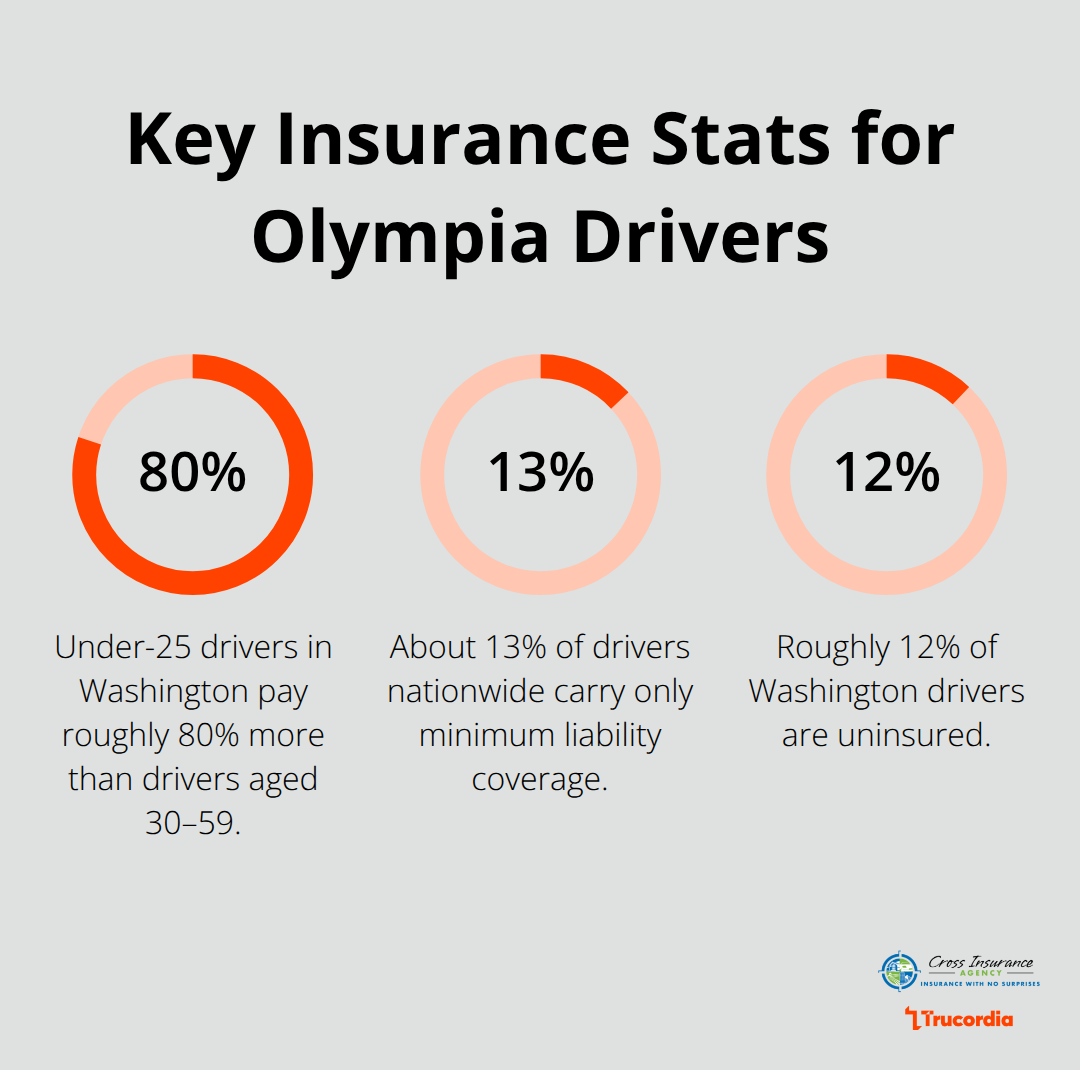
Insurance companies calculate quotes based on specific data points about you and your vehicle. Your age, driving history, and the type of car you drive carry the most weight. Washington state data shows that drivers under 25 pay roughly 80% more than drivers aged 30-59, simply because younger drivers file claims at higher rates.
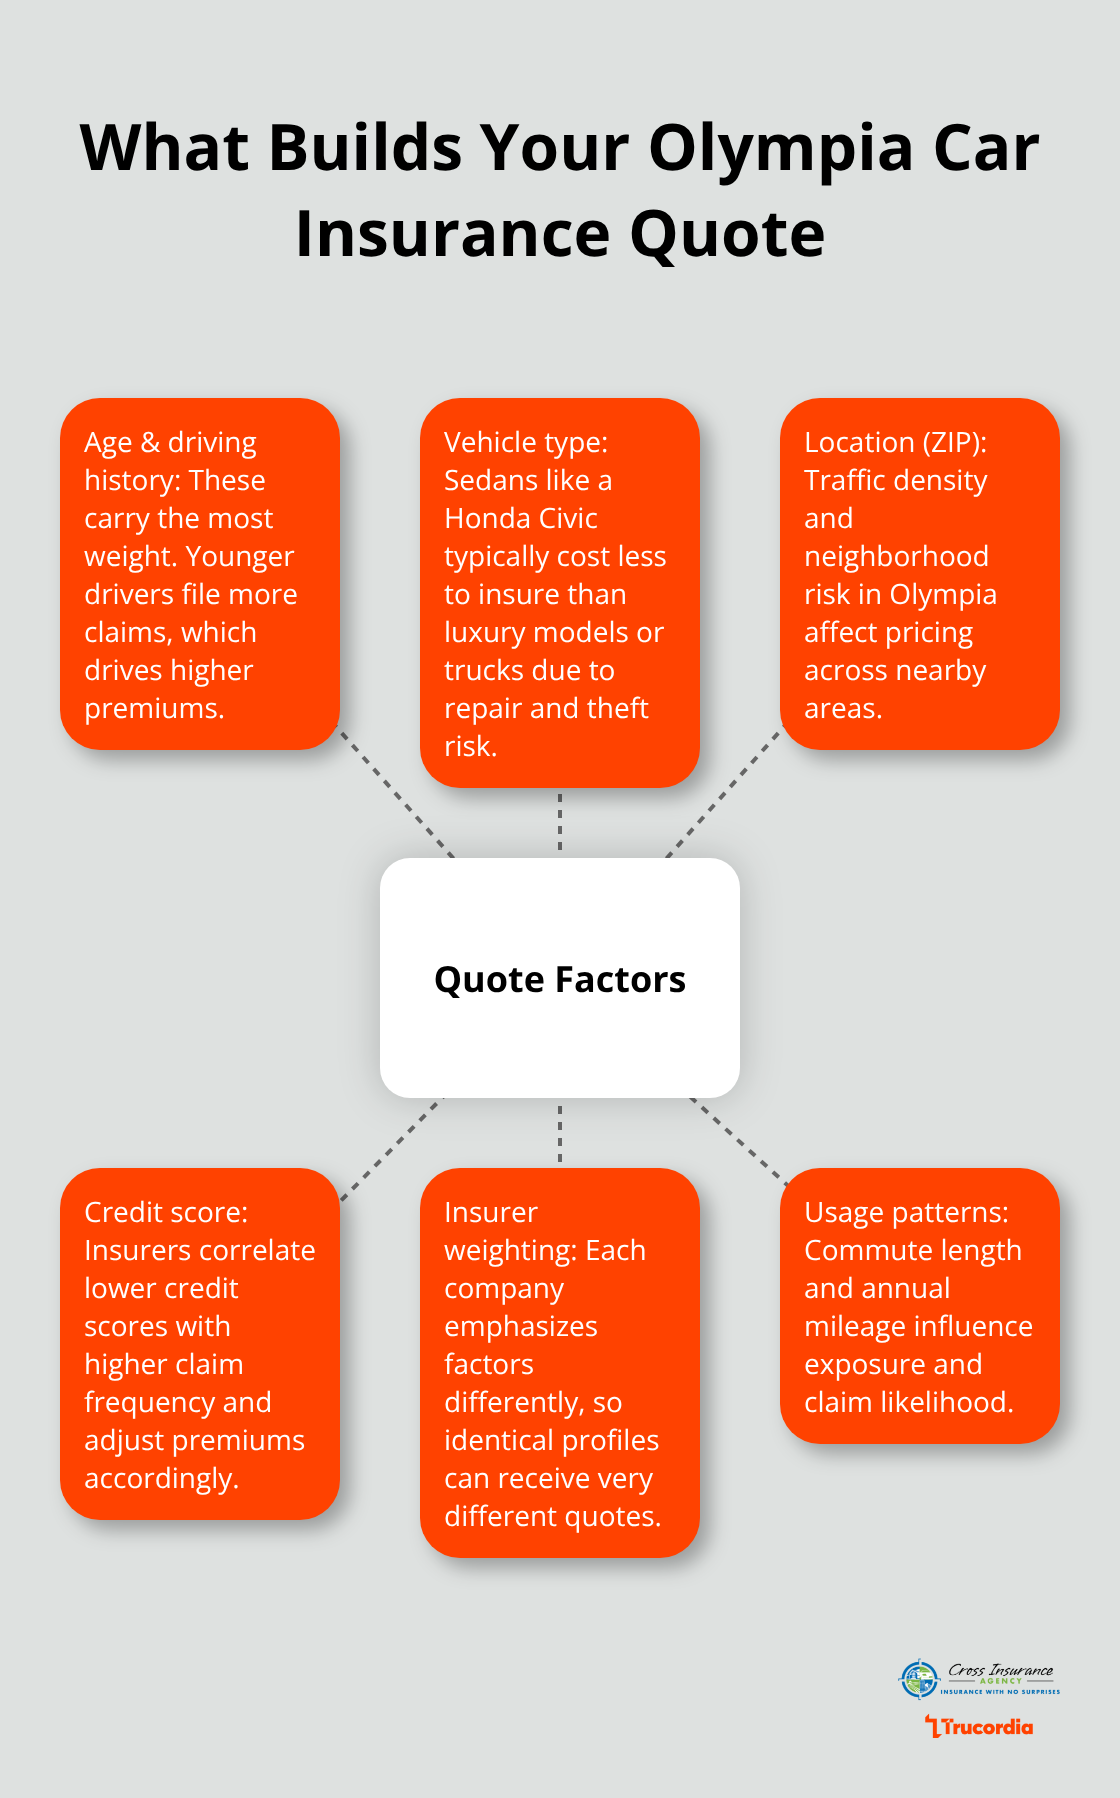
Your zip code matters too-Olympia drivers in higher-traffic areas pay different rates than those in quieter neighborhoods. The type of vehicle you insure affects your premium significantly (a Honda Civic costs less to insure than a BMW or a truck). Credit score plays a role as well; insurers have found that drivers with lower credit scores file more claims, so they adjust premiums accordingly. When you request quotes, each insurer weights these factors differently, which is why you’ll see wildly different numbers from company to company.
Shopping Multiple Quotes Reveals Real Price Differences
Three to five quotes are non-negotiable if you want competitive rates. The National Association of Insurance Commissioners found that price variation between insurers for identical coverage can exceed 300% for the same driver. That means one company might charge $1,200 annually while another charges $4,000. When you compare quotes, look at the same coverage levels across all of them-liability limits, deductibles, and additional coverages must match or the comparison fails. Local agents have access to carriers that online-only platforms don’t represent, which often means better pricing for Olympia drivers. The time you spend comparing quotes directly translates to money in your pocket (sometimes hundreds of dollars annually).
Why Local Knowledge Changes Your Quote
A local agent knows Washington’s specific insurance landscape in ways national websites never will. They understand how Olympia’s weather patterns, road conditions, and traffic density influence risk assessment. They also know which carriers offer the best rates for your particular situation and which ones have strong claims support in your area. An agent identifies discounts you’d never find on your own-bundling your auto and home policies, safety features in your vehicle, or low-mileage discounts if you work from home. They advocate for you if you need to file a claim, rather than leaving you to navigate the process alone with a faceless corporation. National insurers processed over 26 million auto insurance claims in 2024, and having someone in your corner who knows the local claims process matters when things go wrong.
What Happens Next in Your Quote Journey
Once you understand how quotes work and why local agents matter, the next step involves looking at what coverage options actually exist in Washington state. Different policies protect different risks, and Olympia drivers need to know which types of coverage are required by law and which ones make sense for their situation.
Types of Coverage Available in Washington State
Washington state mandates liability coverage, which means you must carry it whether you want to or not. The state requires a minimum of $25,000 for bodily injury per person, $50,000 for bodily injury per accident, and $10,000 for property damage. These minimums are dangerously low. A serious accident involving multiple vehicles or injuries can easily exceed $50,000 in damages, leaving you personally liable for amounts far beyond your policy limits.
Why Minimum Liability Coverage Falls Short
Insurance Information Institute data shows that approximately 13% of drivers nationwide carry only minimum liability coverage, and many of them face financial devastation when accidents exceed those limits. A single lawsuit can target your wages and property for years. We recommend carrying at least $100,000 in bodily injury coverage and $50,000 in property damage, which costs only marginally more than minimums but protects your assets substantially better. Olympia drivers who own homes or have meaningful savings should try $250,000 or higher in liability limits.
Collision and Comprehensive: Protecting Your Vehicle
Collision and comprehensive coverage protects your vehicle itself, but these coverages are optional if your car is paid off. Collision covers damage from accidents with other vehicles or objects, while comprehensive covers theft, weather, vandalism, and animal strikes. If you financed or leased your vehicle, your lender requires both. For owned vehicles, the math is straightforward: if your car’s value is less than five times your annual deductible cost, skip these coverages. A 2015 Honda Civic worth $8,000 with a $500 deductible makes sense to insure; a 2005 vehicle worth $2,000 does not.
Additional Coverage Options for Olympia Drivers
Additional coverage options matter for Olympia drivers specifically. Uninsured motorist protection shields you if an uninsured driver causes an accident, and Washington state has roughly 12% uninsured drivers on the road. Medical payments coverage covers immediate medical expenses regardless of fault.
Roadside assistance helps with towing and lockouts. Gap insurance protects financed vehicles if they’re totaled and you still owe money to the lender. Rental reimbursement covers car rental costs while yours is being repaired (most Olympia drivers benefit from uninsured motorist coverage and medical payments, which add minimal cost but address real risks in Washington’s driving environment).
Now that you understand what coverage options exist and which ones make sense for your situation, the next step involves learning how to actually lower your rates through discounts and smart policy decisions.
Lower Your Olympia Car Insurance Costs
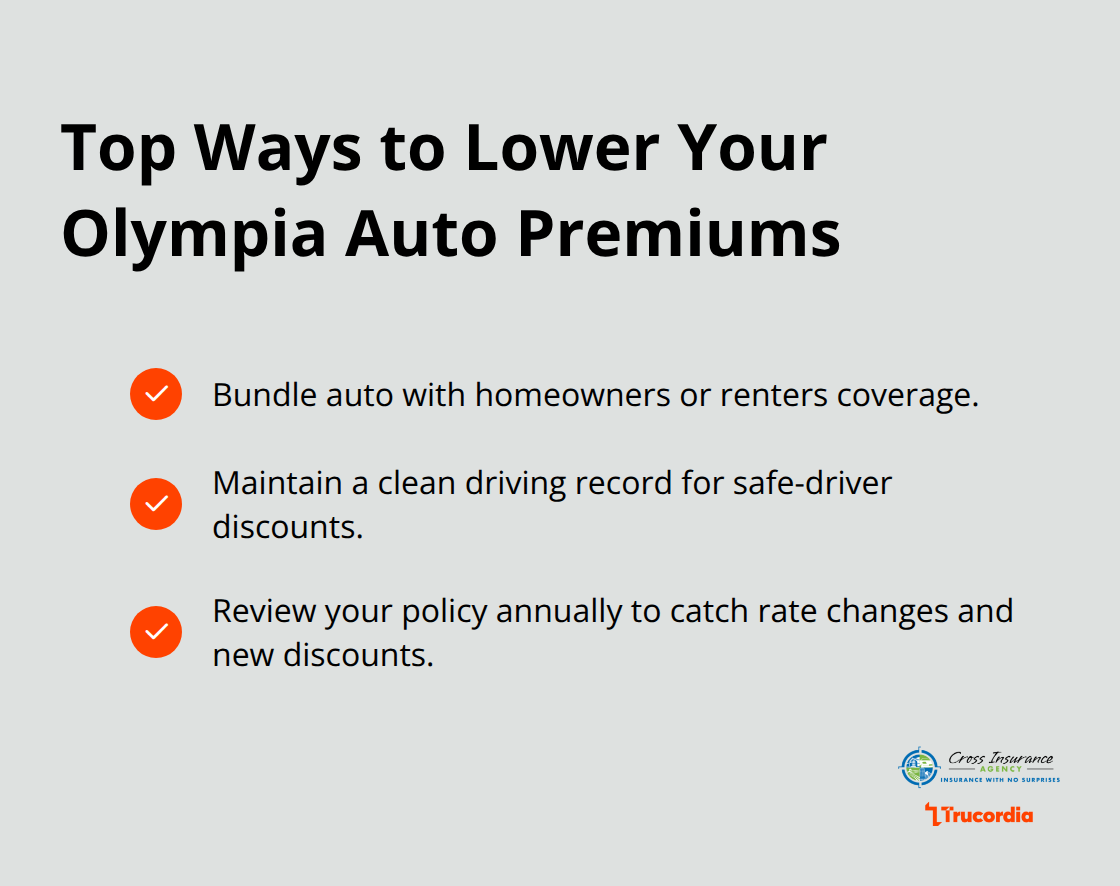
Lowering your insurance costs requires action, not patience. The difference between a passive driver who accepts the first quote and an active one who pursues discounts can easily reach $500 to $1,000 annually. We see this gap repeatedly when we review policies that have been sitting unchanged for years. The three most effective ways to reduce your premiums involve combining policies strategically, maintaining a clean driving record, and conducting regular policy reviews that actually catch rate changes and new discounts.
Bundle Your Policies for Significant Savings
Combining your auto insurance with homeowners or renters coverage typically saves 5% to 25% on your auto policy alone, according to the Insurance Information Institute. If you carry a mortgage, you already have homeowners insurance, which means bundling is available immediately. The math is simple: a driver paying $1,200 annually for auto coverage saves $60 to $300 just by combining policies with the same insurer. Some carriers offer even steeper discounts for bundling three or more policies together.
The catch is that bundling only works if the combined rate is genuinely lower than shopping each policy separately, so compare the bundled quote against standalone quotes before committing. A local agent can show you exactly what bundling saves versus what you’d pay elsewhere, eliminating the guesswork.
Maintain a Clean Driving Record
Your driving record directly impacts your rates, and this is where most Olympia drivers miss opportunities. A single accident or traffic violation can increase your premium by 20% to 40% for three to five years, according to the Insurance Institute for Highway Safety. Conversely, maintaining a clean record for three consecutive years often qualifies you for a safe driver discount worth 10% or more.
If you received a ticket years ago, ask your agent when it stops affecting your rates-violations typically drop off after three years in Washington state, but some carriers maintain longer lookback periods. Defensive driving courses can also reduce your premium by 5% to 10%, and many courses qualify you for the discount immediately after completion.
Review Your Coverage Annually
Reviewing your coverage annually prevents you from overpaying for protection you don’t need or underinsuring against real risks. Rate changes happen constantly-carriers adjust their pricing models, new discounts emerge, and your personal circumstances shift. The average driver who reviews their policy annually saves between $200 and $400 compared to those who never revisit their coverage, according to consumer research from the Consumer Federation of America.
During your review, confirm that your vehicle’s value has changed (older cars depreciate, which might mean dropping collision coverage), check if you’ve qualified for new discounts based on job changes or home improvements, and verify that your coverage limits still match your assets. Annual reviews take thirty minutes and often uncover rate reductions that your current insurer doesn’t advertise automatically.
Final Thoughts
Local agents who understand Olympia deliver better Olympia car insurance quotes than online platforms ever will. We at Cross Insurance Agency shop multiple carriers simultaneously, comparing rates and discounts across options you’d never find on your own. That 300% price variation between insurers disappears when someone advocates for your specific situation instead of leaving you to navigate the process alone.
Your next step is straightforward: contact Cross Insurance Agency to request quotes from multiple carriers. Bring your current policy if you have one, your vehicle information, and your driving history, and our licensed agents will walk you through your coverage options and show you exactly what bundling, discounts, and policy adjustments can save. The conversation takes less time than you’d spend comparing quotes online, and you’ll walk away with actual numbers instead of estimates.
Choosing a trusted insurance partner means selecting someone who prioritizes your protection over commission and understands Olympia’s specific risks. Your vehicle deserves coverage that fits your life, and you deserve an agent who makes that happen without the runaround.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.


